What’s moving now
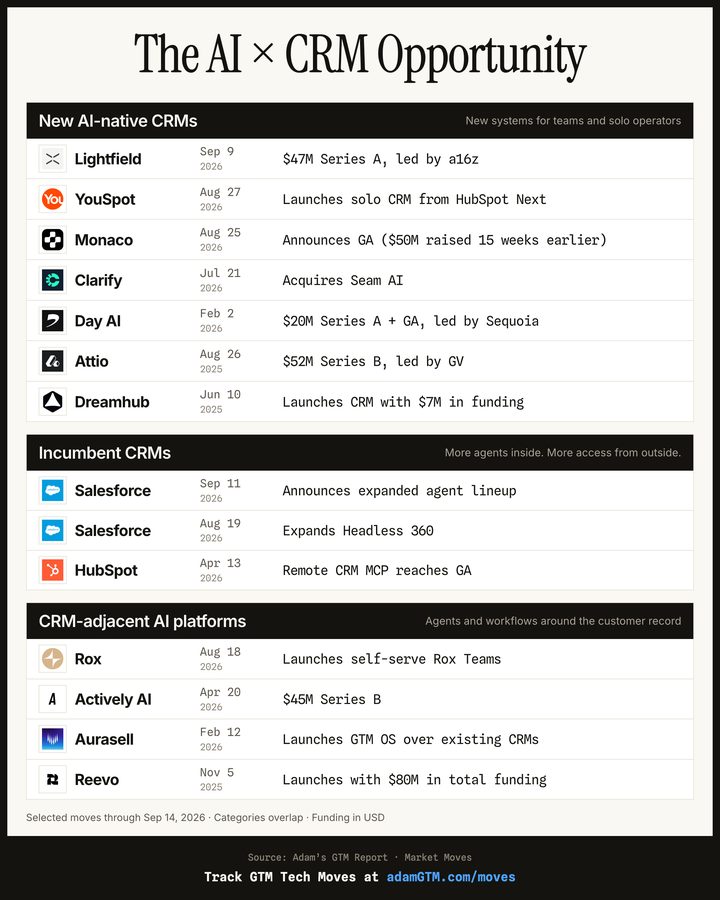 CRM got interestingSep 17 · Lightfield's $47M, AIforce, YouSpot, and the growing pie w
 63.2× the usual response · 6,798 engagements
 30.4× the usual response · 972 engagements
 11.6× the usual response · 29 engagements
 9.5× the usual response · 483 engagements
 8.8× the usual response · 624 engagements
 Devin↑5 places in Coding Agents & Harnesses for GTM
 OpenCode↑2 places in Coding Agents & Harnesses for GTM
 Neon↑27 places in GTM Developer Tools
 Together AI↑25 places in GTM Developer Tools
 LeanData↑22 places in Traditional SaaS Going Headless
Trending Topics
Market Moves
 S756 engagementsPost ↗
 253 engagements · 4.4× usualPost ↗
 234 engagements · 1.7× usualPost ↗
 622 engagements · 1.8× usualPost ↗
 Post ↗
 1,436 engagements · 6.4× usualPost ↗
 52 engagements · 2.3× usualPost ↗
GTM Tech Index
Latest Posts
Sep 17CRM got interestingLightfield's $47M, AIforce, YouSpot, and the growing pie with headless CRMs + agents.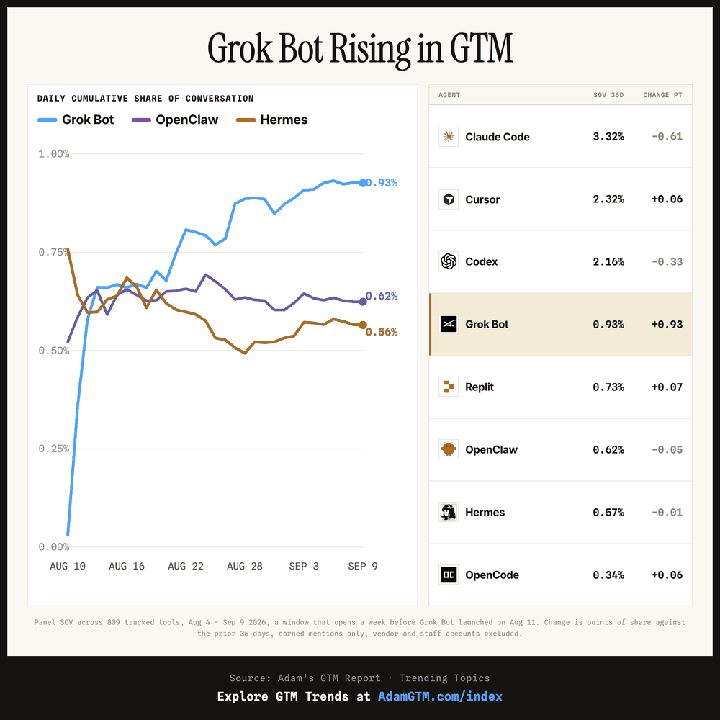 Sep 10Grok Bot or NotMy tests, the hype cycle, and why I'm not pivoting.
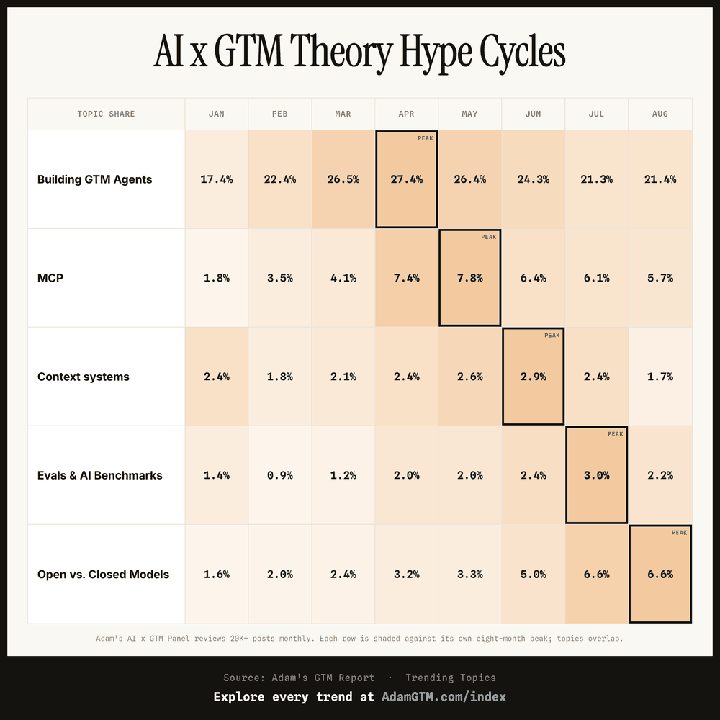 Sep 3Everything I measured in AI x GTM -- August readoutfull EOM report: 47 market moves, SaaSpocalypse fading, signal-based slowdown, AI theory hype cycles, and the AI slop conversation shift.
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
All topics
BetaFigures move as the panel grows and definitions sharpen.
+60.8%vs prior 30d-20.1%vs prior 30d >16×vs prior 30d+2.0%vs prior 30d+9.4%vs prior 30d-14.6%vs prior 30d
 +37.3%vs prior 30d+372%vs prior 30d-17.2%vs prior 30d+11.1%vs prior 30d+8.5%vs prior 30d+28.8%vs prior 30d-23.7%vs prior 30d-7.7%vs prior 30d
 +80.2%vs prior 30d+48.4%vs prior 30d-12.4%vs prior 30d-18.6%vs prior 30d
 -72.7%vs prior 30d+10.9%vs prior 30d+44.8%vs prior 30d-9.1%vs prior 30d-6.2%vs prior 30d-31.7%vs prior 30d-19.9%vs prior 30d+28.3%vs prior 30d
 +111%vs prior 30d
 -23.6%vs prior 30d-18.6%vs prior 30d
 -17.4%vs prior 30d-19.8%vs prior 30d+18.7%vs prior 30d-15.7%vs prior 30d-45.4%vs prior 30d-7.8%vs prior 30d+41.4%vs prior 30d-21.8%vs prior 30d
 +38.9%vs prior 30dNEWvs prior 30d-8.3%vs prior 30d+1.6%vs prior 30d-26.0%vs prior 30d
 -61.2%vs prior 30d
 +0.9%vs prior 30d-67.2%vs prior 30d-33.9%vs prior 30d
 -59.9%vs prior 30d-29.4%vs prior 30d
 -20.6%vs prior 30d
 -16.1%vs prior 30d
 +29.5%vs prior 30d-20.1%vs prior 30d
 +4.7%vs prior 30d
 -37.0%vs prior 30d
 -40.7%vs prior 30d
 -35.7%vs prior 30d
 -44.8%vs prior 30d
 -17.1%vs prior 30d-9.8%vs prior 30d-38.4%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
Share climbed from 22.9% in February to a 27.4% peak in April, then fell every month through August to 21.2%. The last 30 days are down another 3.5%, so the decline is still running, just slower. Builders are still shipping harnesses and benchmarks, but the conversation peaked five months ago.
Posts to understand this · as of Sep 17
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 81 |
| 3 | Grok Bot | 61 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 87 |
| 6 | Salesforce | 91 |
| 7 | Lovable | 57 |
| 8 | HubSpot | 85 |
| 9 | Replit | 54 |
| 10 | OpenClaw | 50 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO has held a band between 10% and 14% all year, peaking at 14.2% in June and easing since. A plateau this high is the story. HubSpot shipped an AEO product and claimed the top CRM visibility spot, while Eli Schwartz and Daydream both argue the acronym is just SEO. Large, contested, and not going anywhere.
Posts to understand this · as of Sep 17
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 51 |
| 2 | Ahrefs | 49 |
| 3 | Semrush | 48 |
| 4 | HubSpot | 85 |
| 5 | Clay | 87 |
| 6 | Webflow | 47 |
| 7 | Claude Code | 99 |
| 8 | AirOps | 37 |
| 9 | Lovable | 57 |
| 10 | Codex | 81 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
This cluster sat in a narrow band between 3.5 and 4.8 percent every month this year. The last 30 days doubled it, and the September evidence is all Dreamforce: Docusign recapping booth 106, Richard Harris walking the floor asking vendors what their agent decided without a human. Conference week, not a new argument.
Posts to understand this · as of Sep 17
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Clay | 87 |
| 4 | Claude Code | 99 |
| 5 | Grok Bot | 61 |
| 6 | Nooks | 48 |
| 7 |  Clarify | 29 |
| 8 | Gamma | 42 |
| 9 |  Rox | 31 |
| 10 | Ahrefs | 49 |
How software exposes its data and actions so agents can use it directly.
Share has sat between 7% and 9.4% since April, up 9.5% in the last 30 days and down 13.8% over 90. The plateau holds because the work keeps getting more concrete. ElevenLabs shipped an MCP inside Claude, Cloudflare opened a waitlist to charge for MCP tools over x402, and Anthropic bought Stainless outright.
Posts to understand this · as of Sep 17
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | Clay | 87 |
| 4 | Codex | 81 |
| 5 | HubSpot | 85 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Instantly | 60 |
| 8 | Grok Bot | 61 |
| 9 | Lovable | 57 |
| 10 | Nooks | 48 |
The people, tools and operating model behind custom go-to-market systems.
The cluster peaked near 9.6 percent in May and has eased every month since, down 9 percent in the last thirty days. The tooling kept shipping while the talk cooled. Clay moved its engine into the terminal, Unify opened 40-plus data sources to reps through chat, and Clay's own team published what it builds versus buys.
Posts to understand this
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 85 |
| 4 | Prospeo | 51 |
| 5 | Codex | 81 |
| 6 | Instantly | 60 |
| 7 | Salesforce | 91 |
| 8 | Lemlist | 49 |
| 9 | HeyReach | 51 |
| 10 |  FullEnrich | 41 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Peaked at 9.4% in May and has drained since, down 24% over 90 days, with L30 nearly flat at minus 6%. The idea is not dying, it is being absorbed into AI visibility. Rand Fishkin still asks whether the website matters; Wil Reynolds asks who is inside the consideration set AI answers already picked.
Posts to understand this · as of Sep 18
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 51 |
| 2 | Ahrefs | 49 |
| 3 | Semrush | 48 |
| 4 | HubSpot | 85 |
| 5 | Clay | 87 |
| 6 | Webflow | 47 |
| 7 | Claude Code | 99 |
| 8 | AirOps | 37 |
| 9 | Grok Bot | 61 |
| 10 | Lovable | 57 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Share climbed from 2.1 percent in February to a July peak of 8.5 percent, and completed August at 7.3 percent, still well above June's 5.3 percent. The July run-up tracks open-model advocacy from Nvidia's signed letter and Palantir's ownership argument. The last 30 days are down 40 percent; September is only 16 days in.
Posts to understand this · as of Sep 16
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 91 |
| 5 | OpenRouter | 49 |
| 6 | Baseten | 45 |
| 7 | Vercel | 59 |
| 8 | Grok Bot | 61 |
| 9 | Together AI | 31 |
| 10 | Clay | 87 |
How companies prove AI delivers enough value to move beyond a pilot.
Share of conversation held between 6.3% and 7.8% from February through July, then eased to 6.1% in August. The last 30 days are down 39%, so the current direction is down, though September is only 18 days in. The posts still working this topic are asking what the freed-up time actually buys.
Posts to understand this · as of Sep 18
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | Codex | 81 |
| 4 | HubSpot | 85 |
| 5 | OpenRouter | 49 |
| 6 | Clay | 87 |
| 7 | OpenClaw | 50 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Lovable | 57 |
| 10 | Vercel | 59 |
How large companies move AI from small pilots into secure, useful production work.
April was the high at 7.5 percent, and the slide has been steady since: down 20 percent over 90 days, down 32 over the last 30. The evidence shows why. Mistral shipped Workflows for production reliability, Rippling built a console to map AI spend to teams, and the safety pitch leans on a Replit agent deleting a database. Adoption talk became plumbing and controls.
Posts to understand this · as of Sep 17
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 85 |
| 4 | Codex | 81 |
| 5 | Clay | 87 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Lovable | 57 |
| 8 | OpenRouter | 49 |
| 9 | OpenClaw | 50 |
| 10 | Grok Bot | 61 |
How teams use buyer signals to decide who to target, when and why.
Share has faded steadily since February, from 7.8% to 4.1% in August, with no single break point. The March Apollo/Pocus deal and Mutiny's April relaunch both landed inside a decline that was already running. September is only 17 days in, and the last 30 days are down 5.6%, so the direction has not turned.
Posts to understand this · as of Sep 17
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | HubSpot | 85 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 91 |
| 5 | Instantly | 60 |
| 6 | Apollo.io | 51 |
| 7 | Prospeo | 51 |
| 8 | HeyReach | 51 |
| 9 | Apify | 53 |
| 10 | Nooks | 48 |
How companies build trust and stand out when AI makes content cheap and abundant.
This cluster has held a 4 to 6% band all year with no single event behind it. What sustains it is a grievance: AI content is cheap, and the tools built to police it are their own problem. Ann Handley's August post on slop buttons, humanizers, and writers adding typos on purpose is the clearest version. Down 22.9% over the last 30 days.
Posts to understand this · as of Sep 17
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | HubSpot | 85 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 91 |
| 5 | Clarify | 29 |
| 6 | Nooks | 48 |
| 7 | Codex | 81 |
| 8 |  Docket | 29 |
| 9 | Grok Bot | 61 |
| 10 | Substack | 52 |
How teams create, distribute and judge marketing content made with AI.
Four straight months near 4.5% with no launch behind any of it. The conversation is an argument about quality: Ann Handley on writers adding typos to prove they are human, Sara Stella Lattanzio on platform saturation, Kamil Rextin publicly recanting his AI maximalism. Down 27% over the last 30 days and 19% over 90.
Posts to understand this · as of Sep 17
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Claude Code | 99 |
| 3 | Midjourney | 36 |
| 4 | Higgsfield | 38 |
| 5 | Runway | 33 |
| 6 | Salesforce | 91 |
| 7 | Clay | 87 |
| 8 | Lovable | 57 |
| 9 | Grok Bot | 61 |
| 10 | Replit | 54 |
How companies keep agents secure, accountable and under control as they take on real work.
Agent governance climbed steadily from 3.1% share in February to 6.5% in July, then gave back ground in August, the only completed month of decline, at 5.4%. The last 30 days are down 46.9%, so the current 3.5% share is a fast fade, not a plateau. The posts still in the window are about control: identity, cost accounting, and hidden failures.
Posts to understand this · as of Sep 18
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 91 |
| 5 | Grok Bot | 61 |
| 6 | OpenRouter | 49 |
| 7 | Clay | 87 |
| 8 | HubSpot | 85 |
| 9 | LangChain | 45 |
| 10 | OpenClaw | 50 |
How AI changes software pricing, usage costs and gross margins.
Attention climbed to a June high, then faded through July and August, and the last 30 days are down about 36 percent. The posts still landing move the topic from sticker shock to cost control: open-weight competition pushing prices off the frontier, enterprises capping what they will spend, and one team cutting its own bill while usage grows.
Posts to understand this · as of Sep 14
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | OpenRouter | 49 |
| 4 | Clay | 87 |
| 5 | Codex | 81 |
| 6 | Claude Code | 99 |
| 7 | Replit | 54 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Lovable | 57 |
| 10 |  Twilio | 39 |
How AI changes what software companies build, charge for and deliver.
February was the loudest month at 5.4% and the line has drifted down to the mid-2s since, off 26% over 90 days with a small 8% lift in the last 30. The tone changed along with the level. Early posts argued the model is breaking, ElevenLabs cutting API prices up to 55%. By August Salesforce was posting that it put the saaspocalypse myth to bed.
Posts to understand this · as of Sep 16
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | HubSpot | 85 |
| 4 | Claude Code | 99 |
| 5 | Lovable | 57 |
| 6 | Replit | 54 |
| 7 | ZoomInfo | 50 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Twilio | 39 |
| 10 | Intercom | 43 |
How teams track and control the cost of models, tokens and agent work.
Share climbed through July, slipped in August, and is down about 40% over the last 30 days. The August posts sit on that slope, not the climb: Rippling and Peter Walker both talk about token cost as a settled budget problem rather than news. Vercel is still shipping the same gateway plumbing in September while the share keeps sliding.
Posts to understand this · as of Sep 16
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | OpenRouter | 49 |
| 2 | Salesforce | 91 |
| 3 | Codex | 81 |
| 4 | Claude Code | 99 |
| 5 | Clay | 87 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Vercel | 59 |
| 8 | HubSpot | 85 |
| 9 | OpenClaw | 50 |
| 10 | Twilio | 39 |
The choice between building software internally and buying another product.
April was the peak and July the floor. The move up since is defensive: Benioff used a record Salesforce quarter to argue AI is not replacing the platform. The practitioner posts sit on the other side, with Zipline plugging in via MCP and running its own revenue OS. L30 is up 20.2%, still well under April.
Posts to understand this
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | HubSpot | 85 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 50 |
| 6 | Airtable | 48 |
| 7 | Clarify | 29 |
| 8 | Codex | 81 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Lovable | 57 |
Growth driven by people using the product before they talk to sales.
Share more than halved between February and July, from 3.86% to 1.65%, and August's 1.91% did not reverse it. The wins are concentrated rather than broad: Lovable at a $13.3B valuation, Anthropic closing 54% of new enterprise logos with no sales meeting, PostHog with 97% of customers paying nothing. Down 17.9% over 30 days.
Posts to understand this · as of Sep 17
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | Codex | 81 |
| 4 | HubSpot | 85 |
| 5 | Canva | 48 |
| 6 | Clay | 87 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Intercom | 43 |
| 9 | Replit | 54 |
| 10 | Lovable | 57 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR ran above 3% from March into May, then lost nearly half its share by July and has not come back. Spring was launches and claims, with Artisan's Ava 2.0 saying it replaces ZoomInfo, Clay, Salesloft, Aircall and Common Room. The pushback showed up alongside them, on ROI and on data. L30 is down 12.2%.
Posts to understand this
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 85 |
| 5 | Lovable | 57 |
| 6 | ZoomInfo | 50 |
| 7 | Nooks | 48 |
| 8 | Outreach | 45 |
| 9 | Airtable | 48 |
| 10 | Clarify | 29 |
How people and agents share work, hand off tasks and make decisions together.
Share peaked in May at 2.8 percent, when Dust named multiplayer AI and StackAI announced it was joining Asana to run humans and agents together. It has slipped every month since, down to 1.8 percent in August, and the last 30 days are off 16.7 percent. What is left is practice: Vista running 59 teams through a multi-agent hackathon.
Posts to understand this · as of Sep 14
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 81 |
| 3 | Salesforce | 91 |
| 4 | HubSpot | 85 |
| 5 | OpenClaw | 50 |
| 6 | beehiiv | 48 |
| 7 | Clay | 87 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Grok Bot | 61 |
| 10 | LangChain | 45 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context engineering climbed to 2.865% in June, then gave it back to 1.785% by August, with the last 30 days down 15%. The June high sat alongside Perplexity's Brain memory launch. By August the talk had moved to credentials and internal plumbing, like a Databricks certification exam and teams wiring semantic views into their own GTM engines.
Posts to understand this · as of Sep 17
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 91 |
| 3 | Clay | 87 |
| 4 | HubSpot | 85 |
| 5 | Codex | 81 |
| 6 | Cursor (Anysphere) | 78 |
| 7 |  Sumble | 33 |
| 8 | Grok Bot | 61 |
| 9 | Gong | 63 |
| 10 |  Attention | 31 |
Low-quality AI content and the fight to make automated work worth reading.
This one never spiked. It has run near 2% since February and eased since May, down 42% over the last 30 days. The posts are craft arguments rather than news: humanizer tools and slop buttons turning writers on each other, Satya writing his own essay, hand copy work as a daily drill.
Posts to understand this · as of Sep 17
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Salesforce | 91 |
| 3 | Claude Code | 99 |
| 4 | Clay | 87 |
| 5 | Codex | 81 |
| 6 | Docket | 29 |
| 7 | Lovable | 57 |
| 8 | Substack | 52 |
| 9 | Airtable | 48 |
| 10 | Clarify | 29 |
The argument that agents and custom software will break the classic SaaS model.
Share fell from 3.2 percent in February to about 1.0 percent in July and August, down 38.7 percent over the last 90 days. Those two complete months sit level near one point, and the last 30 days are up 6 percent, so the slide has stalled rather than continued. September is not finished.
Posts to understand this
 inVendor rebuttalSalesforce posts a record quarter and says attrition and seat growth contradict the thesisTD
 inBuyer checkbeehiiv runs 50+ engineers and still pays for Slack, HubSpot, Zendesk, SentryEO
 inPayments dataStripe data shows SaaS revenue growth accelerating during this year's software sell-off
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | HubSpot | 85 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 50 |
| 6 | Clarify | 29 |
| 7 | Codex | 81 |
| 8 | Nooks | 48 |
| 9 | Sumble | 33 |
| 10 | Twilio | 39 |
Ways to verify whether digital content or online activity came from a person or AI.
August nearly tripled to 1.14% on one cause: Anthropic's watermarking FAQ on the 14th, Lily Ray's response on the 15th, Synthesia's Article 50 post on the 19th. Regulation set the agenda here, not a product. The last 30 days are down 59% as that cycle cleared, with the 90-day line still up 84%.
Posts to understand this · as of Sep 17
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Substack | 52 |
| 3 | Claude Code | 99 |
| 4 | Clay | 87 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Higgsfield | 38 |
| 7 | HubSpot | 85 |
| 8 | Salesforce | 91 |
| 9 | ZoomInfo | 50 |
| 10 |  6sense | 40 |
AI tools that write, edit, test and operate software alongside a human builder.
Coding agents ran at 21% in March and have drifted to about 14%, flat over the last 30 days. The tools stopped being the story and the results took over: ColdIQ running $300k a month in ad spend from the terminal, Notion defining a whole workspace in TypeScript, and Cursor's founders cashing out in SpaceX's $60 billion acquisition.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 81 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 61 |
| 5 | Clay | 87 |
| 6 | Lovable | 57 |
| 7 | Salesforce | 91 |
| 8 | HubSpot | 85 |
| 9 | Replit | 54 |
| 10 | OpenClaw | 50 |
The frontier models and labs that provide the base layer for AI products.
Three labs kept this loud on price and capability. Anthropic's Project Glasswing and the Mythos preview drew the biggest single response of the year here. Then Sonnet 5's introductory pricing went permanent in August, and Grok 4.6 arrived the same week at half the price of comparable frontier models. August cooled off, and the L30 move is back up about 9%.
Posts to understand this · as of Sep 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 61 |
| 5 | HubSpot | 85 |
| 6 | OpenClaw | 50 |
| 7 | OpenRouter | 49 |
| 8 | Salesforce | 91 |
| 9 | Vercel | 59 |
| 10 | Midjourney | 36 |
An open protocol that lets agents connect to a product's data, tools and actions.
Share peaked in May and has eased every month since, down 17 percent across 90 days. The August evidence sits inside that easing, and both posts fold MCP into something larger: Vercel's plugin standard and ElevenLabs shipping a server into Claude. The last 30 days turned up 7.1 percent, with DocuSign dating its server to September 30.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 91 |
| 3 | Clay | 87 |
| 4 | Codex | 81 |
| 5 | HubSpot | 85 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Instantly | 60 |
| 8 | Prospeo | 51 |
| 9 | Grok Bot | 61 |
| 10 | Nooks | 48 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO tracks zero-click almost exactly: a May high near 8%, then a fade to about 5.4%, down 8.7% in the last 30 days. The tone changed with the level. Andrew Yan found only 11% of cited domains overlap across engines, and Eli Schwartz closed August with Google's line that there is no AEO without SEO fundamentals.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 51 |
| 2 | Ahrefs | 49 |
| 3 | Semrush | 48 |
| 4 | Clay | 87 |
| 5 | HubSpot | 85 |
| 6 | Webflow | 47 |
| 7 | AirOps | 37 |
| 8 | Claude Code | 99 |
| 9 | Grok Bot | 61 |
| 10 | Lovable | 57 |
People asking AI assistants for answers instead of using a traditional search engine.
A plateau, and that is the point. Share has held between 5 and 7 percent for eight months, up 2.5 percent over 90 days and down 11 over the last 30, even as Profound raised a $180M Series D at $1.8B co-led by Sequoia and Kleiner Perkins. HubSpot sells AEO to a canned cocktail brand; Google says good SEO is good GEO. Funding spikes, conversation does not.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | Profound | 51 |
| 3 | Ahrefs | 49 |
| 4 | HubSpot | 85 |
| 5 | Claude Code | 99 |
| 6 | Webflow | 47 |
| 7 |  Optimizely | 28 |
| 8 | AirOps | 37 |
| 9 | Clay | 87 |
| 10 | Codex | 81 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce stayed near zero all year, under one percent of share through August. Then the conference landed. Informatica announced its debut as part of the Salesforce family on September 8, and on the 16th Crossbeam and Outreach both posted AgentExchange news. September is only 17 days in, so read it as the event arriving, not a finished month.
Posts to understand this · as of Sep 17
 inOwnership debutInformatica announces its Dreamforce debut as part of the Salesforce familyBM
 inLaunch partnerCrossbeam named an AgentExchange launch partner in the AI agents and tools categoryAM
 inMarketplace transactionOutreach says it is the first revenue orchestration platform transacting on AgentExchange
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Intercom | 43 |
| 4 | 1mind | 37 |
| 5 |  Gradial | 21 |
| 6 |  Centralize | 23 |
| 7 | Clarify | 29 |
| 8 | Claude Code | 99 |
| 9 | Outreach | 45 |
| 10 | Rox | 31 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
April was the high point, when Mistral shipped Workflows for enterprise orchestration and the Copilot reappraisal landed. Share has fallen nearly every month since, and the last 30 days are down 29.6 percent. Dreamforce still produced posts like Liza Adams on Dario Amodei's 5 to 10 percent value claim, but one conference no longer lifts the whole topic.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 85 |
| 4 | Lovable | 57 |
| 5 | OpenClaw | 50 |
| 6 | OpenRouter | 49 |
| 7 | AirOps | 37 |
| 8 | Attio | 50 |
| 9 |  CHEQ | 15 |
| 10 | Clay | 87 |
Email sent to people with no prior relationship to start a sales conversation.
Cold email share climbed from 3.0% in February to a 5.5% peak in May, when practitioners were arguing in public about whether sequencers still work at all. It has fallen back since, sitting near 3.2% through July and August and down 28% over 90 days. The last 30 days are flat at down 3%, so the drop has stalled rather than reversed.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 87 |
| 3 | Instantly | 60 |
| 4 | Prospeo | 51 |
| 5 | Lemlist | 49 |
| 6 | HubSpot | 85 |
| 7 | Apollo.io | 51 |
| 8 | HeyReach | 51 |
| 9 | n8n | 58 |
| 10 |  AI Ark | 43 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer success is still one of the biggest blocks of the conversation, but it has shed roughly a third of its share since February and the last 30 days are down again. The posts show where it went. Vanta folded post-sales into one sales org, Rox is selling agents that run renewals and expansion, and one buyer could not reach a human at Salesforce.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Clay | 87 |
| 4 | Claude Code | 99 |
| 5 | Twilio | 39 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Intercom | 43 |
| 8 | Lovable | 57 |
| 9 | Replit | 54 |
| 10 |  Salesloft | 41 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps share slid through the summer, down 27.1% over the last 90 days, with August at 2.70%, the lowest completed month. The last 30 days are up 5.7%, so the slide has flattened rather than continued. The argument now is about where the work sits, not what it is called.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | HubSpot | 85 |
| 4 | Claude Code | 99 |
| 5 | Attio | 50 |
| 6 | Gong | 63 |
| 7 | Codex | 81 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Instantly | 60 |
| 10 | Granola | 47 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Share dropped more than a point between May and July, then stopped moving: 2.85% in July, 2.79% in August, and the L30 is flat at down 2.6%. The plateau matters because vendors kept shipping into it. Clay rebuilt its sequencer and then released an API and CLI, and Salesforce previewed Hunter in the Agentforce summer release.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 91 |
| 4 | HubSpot | 85 |
| 5 | Prospeo | 51 |
| 6 | Instantly | 60 |
| 7 | Apollo.io | 51 |
| 8 | AI Ark | 43 |
| 9 | Grok Bot | 61 |
| 10 | n8n | 58 |
Measuring whether AI answers mention, cite and recommend a brand.
The curve peaked in June at 4.1% and has cooled since, with L30 down 24% and L90 still up 10%. The argument changed underneath it. Ryan Law's Ahrefs study set the optimization agenda in February, and by August the Otterly slop test had turned citation rate itself into the thing under attack.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | Profound | 51 |
| 3 | Ahrefs | 49 |
| 4 | HubSpot | 85 |
| 5 | Claude Code | 99 |
| 6 |  Ranked AI | 35 |
| 7 | Salesforce | 91 |
| 8 | Docket | 29 |
| 9 | Peec AI | 28 |
| 10 | AirOps | 37 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand generation is down about 26 percent over 90 days and roughly flat in the last 30, while the posts argue the model itself is going. Dave Gerhardt says buyers get answers from AI instead of gated content, Joe Chernov says founders no longer hire demand gen first, and Brigitta Ruha shows form-fill optimization teaching Meta to find fillers, not buyers.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | HubSpot | 85 |
| 3 | Salesforce | 91 |
| 4 | Docket | 29 |
| 5 | Webflow | 47 |
| 6 | RB2B | 48 |
| 7 | Claude Code | 99 |
| 8 | Instantly | 60 |
| 9 | Optimizely | 28 |
| 10 | HeyReach | 51 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
A steady erosion, not a break. Share drifted from 3.44% in March to 2.41% in August with no event behind any single step, and the L30 is down 16.7%. The posts still landing are about execution rather than the motion itself: Rippling's 150 SDRs, Gong's five-minute response, signal campaigns handed to an agent.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 87 |
| 3 | Instantly | 60 |
| 4 | Nooks | 48 |
| 5 | Prospeo | 51 |
| 6 | Gong | 63 |
| 7 | HeyReach | 51 |
| 8 | HubSpot | 85 |
| 9 | Salesforce | 91 |
| 10 | Lemlist | 49 |
Voice and chat software that talks with buyers and customers.
Share has bounced between 1.7 and 2.8 percent since February. It dipped to 1.7 in June, came back to 2.8 in July and held near that in August, and the last 30 days are down 27 percent. September's posts are model releases and deployments, not a new high.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 |  AssemblyAI | 33 |
| 2 | beehiiv | 48 |
| 3 | Salesforce | 91 |
| 4 | HubSpot | 85 |
| 5 | Codex | 81 |
| 6 | Claude Code | 99 |
| 7 | Docket | 29 |
| 8 | Grok Bot | 61 |
| 9 | Vercel | 59 |
| 10 | ElevenLabs | 50 |
The debate over AI risk, alignment, regulation and responsible development.
Safety talk sat under one percent for most of the year, then more than doubled in the last 30 days. Anthropic's Model Hardware Standard and Mistral's Shieldstral moderation model both put safety inside shipped product, and Satya Nadella's superintelligence post pulled Microsoft in. September is only 19 days in, so read that as direction, not a finished move.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 61 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Salesforce | 91 |
| 6 | OpenClaw | 50 |
| 7 | Substack | 52 |
| 8 | beehiiv | 48 |
| 9 | ElevenLabs | 50 |
| 10 |  Frontier | 22 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid media share fell from 2.7 percent in February to 1.8 in April, then held between 2.1 and 2.5 through August. The last 30 days are down about 20 percent. The posts show a split: one shop puts paid at 10.5 percent of leads, another credits LinkedIn ads with 75 percent of pipeline.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | HubSpot | 85 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 60 |
| 5 | Codex | 81 |
| 6 | HeyReach | 51 |
| 7 | Nooks | 48 |
| 8 |  Tally | 32 |
| 9 | Apollo.io | 51 |
| 10 | Lemlist | 49 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
The year's high was February at 4.7%, and March carried real news when Apollo acquired Pocus and people wrote about the data layer and signal layer finally sitting together. Nothing since has matched it. Clay's Workflows launch in August, a node-based orchestration canvas with run tracing, did not lift the line, and the last 30 days are down 24%.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Clay | 87 |
| 4 | Claude Code | 99 |
| 5 |  GrowthLoop | 30 |
| 6 | Gong | 63 |
| 7 | Codex | 81 |
| 8 | Twilio | 39 |
| 9 | Attio | 50 |
| 10 | Grok Bot | 61 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
No single event bends this one. Enrichment held above 2.9% into June, stepped down in July and has drifted since. The talk moved underneath the category: ZoomInfo as the native data layer for Salesforce's prospecting agent, a Clay power user rebuilding waterfalls in Claude Code, and CRM governance set before an agent gets access. L30 is down 10.8%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Claude Code | 99 |
| 3 | Instantly | 60 |
| 4 | HubSpot | 85 |
| 5 | Prospeo | 51 |
| 6 | HeyReach | 51 |
| 7 | AI Ark | 43 |
| 8 | Lemlist | 49 |
| 9 | Apollo.io | 51 |
| 10 |  Findymail | 40 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
Eight months inside a band of 1.4 to 2.3 percent, with no breakout. Grok's Imagine video 1.5 added text-to-video and native 1080p, fal shipped Seedance 2.5, and Black Forest Labs put fast editing into Flux 3 video. Constant releases, and no single one that moves the conversation. Down 29% over the last 30 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Midjourney | 36 |
| 2 | Higgsfield | 38 |
| 3 | HubSpot | 85 |
| 4 | Runway | 33 |
| 5 | Claude Code | 99 |
| 6 | Salesforce | 91 |
| 7 | Lovable | 57 |
| 8 | Replit | 54 |
| 9 |  HeyGen | 32 |
| 10 | ElevenLabs | 50 |
Programmable tools used to build custom go-to-market systems, agents and automations.
The spring climb was Claude Code. Practitioners started publishing whole cold email builds and open skill repos, and share peaked near 2.6% in May before the how-to wave cooled through August. The last 30 days are up 26.1%, though the 90-day trend is still down 23.4%.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Prospeo | 51 |
| 2 | Instantly | 60 |
| 3 | Clay | 87 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 85 |
| 6 | FullEnrich | 41 |
| 7 | HeyReach | 51 |
| 8 | Lemlist | 49 |
| 9 | Apollo.io | 51 |
| 10 | Findymail | 40 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability sits in a band between 1% and 2.2% with no launch driving it, and the last 30 days are up 21%. The posts are maintenance work: Resend hiring a deliverability engineer out of Klaviyo, Customer.io taking questions on Reddit, and Brigitta Ruha's math on how a 16% bounce rate kills a domain.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Instantly | 60 |
| 3 | HubSpot | 85 |
| 4 | Prospeo | 51 |
| 5 | Salesforce | 91 |
| 6 | Claude Code | 99 |
| 7 | Lemlist | 49 |
| 8 |  Smartlead | 44 |
| 9 | Codex | 81 |
| 10 | Grok Bot | 61 |
Sales and marketing coordinating around a defined set of target accounts.
Down from 3.6% in February to about 1.6%, with the last 30 days off 16%. February held the events: Kelly Hopping moving from Demandbase to 6sense, Clay adding ads with 90% LinkedIn match rates. Nothing since has matched them. Joshua Perk's September launch attacks legacy ABM platforms for running on two account-level signals, which is the live argument now.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Clay | 87 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 91 |
| 5 | 6sense | 40 |
| 6 | Apify | 53 |
| 7 | HeyReach | 51 |
| 8 | Docket | 29 |
| 9 | FullEnrich | 41 |
| 10 | Instantly | 60 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
In-person events are up about 25 percent over 90 days, the clearest rise here, and the last 30 days held the gain. Summer conference season carried it, with Databricks opening Data + AI Summit to 30,000 attendees. The complaints are the tell: show rates and Bay Area venue naming are operator problems, which is what real activity sounds like.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 87 |
| 3 | Salesforce | 91 |
| 4 | HubSpot | 85 |
| 5 | Clarify | 29 |
| 6 | Codex | 81 |
| 7 | Docket | 29 |
| 8 | Grok Bot | 61 |
| 9 | Vercel | 59 |
| 10 | 1mind | 37 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Share climbed from February to a July peak, then gave ground in August, and the last 30 days are down 42 percent. What still posts is benchmark supply from vendors: Mercor turning enterprise workflows into evals, Cognition claiming frontier-level coding scores for a cheaper model, Surge rerunning a hyped result on its own unreleased benchmark and getting something ordinary.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 61 |
| 5 | LangChain | 45 |
| 6 | Salesforce | 91 |
| 7 |  Cline | 26 |
| 8 | Clay | 87 |
| 9 | Vercel | 59 |
| 10 | Devin | 37 |
The training, fine-tuning and modeling work underneath AI products.
This is the one line holding up while the GTM categories fall, up 33% over ninety days. The rise is supply, not commentary: Skild's S1 robot model learning from a single demo, Poolside's open-weight Laguna S 2.1, and Together AI putting 10,000 NVIDIA B300 GPUs in Chennai. L30 is off 5.7%, so the level is holding rather than climbing.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 91 |
| 5 | LangChain | 45 |
| 6 |  Groq | 26 |
| 7 | OpenClaw | 50 |
| 8 | OpenRouter | 49 |
| 9 | Baseten | 45 |
| 10 | Devin | 37 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
This one is a calendar. UNBOUND ran September 16 to 18 in Boston, and the run-up did the work: John Barrows previewing 300-plus AI and agent sessions, Dharmesh Shah trading his fifteenth keynote for a fireside with Brian Halligan, Yamini Rangan briefing 1,300 partners on data and outcomes. Up 450% over the last 30 days, with the September bar still filling.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Clay | 87 |
| 3 | Gamma | 42 |
| 4 | Salesforce | 91 |
| 5 |  Breeze | 21 |
| 6 | 6sense | 40 |
| 7 |  Chili Piper | 33 |
| 8 | Docket | 29 |
| 9 | Intercom | 43 |
| 10 |  LeadIQ | 16 |
The work of connecting marketing activity to pipeline and revenue.
The line has slid since March, from 2.5 percent to under 1.4, and the last 30 days are flat. No single event explains it. The posts that do land reframe the work instead of defending it: Ethan Smith's n8n case study treats last touch as broken for zero-click AI conversions, and Amanda Natividad's book sells that same premise.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Salesforce | 91 |
| 3 | Clay | 87 |
| 4 | Claude Code | 99 |
| 5 | Docket | 29 |
| 6 | GrowthLoop | 30 |
| 7 | Intercom | 43 |
| 8 | Lovable | 57 |
| 9 |  MoEngage | 23 |
| 10 | Apollo.io | 51 |
The choice of go-to-market motion and the plan for making it work.
Nothing broke. GTM Strategy has slid steadily since March, down 40% over the quarter and still easing over the last 30 days. The posts show where it went: off the plan and into the mechanics. Amos Bar-Joseph's agent-run pipeline, a GTM methodology shipped as Claude Code skills, Notion's workflow-first roles. People argue about the motion by building it.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 91 |
| 4 | HubSpot | 85 |
| 5 | Grok Bot | 61 |
| 6 | Nooks | 48 |
| 7 | Airtable | 48 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | HeyReach | 51 |
| 10 | Intercom | 43 |
Mapping and winning the committee of people involved in a business purchase.
A steady fade from 3.0% in March to 1.4%, down 14% in the last 30 days. No vendor event drives this one, and that is the pattern: the posts are craft, not news. Clay's Slack channel for exec multithreading, Anthony Pierri on who actually reads a homepage, Krysten Conner separating a champion from a contact.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Clay | 87 |
| 4 | Claude Code | 99 |
| 5 | Gong | 63 |
| 6 | Codex | 81 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Instantly | 60 |
| 9 |  Vector | 39 |
| 10 | Apollo.io | 51 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
This one saws back and forth rather than trending, between 1.3% and 2.5% all year, roughly flat over the last 30 days at -2%. August's bump to 1.66% came from definition fights: Jen Abel arguing the process is 15 steps not five, and Ryan Walsh charting 80 sales orgs to show which enterprise titles are really enterprise. Arguments about the label, not new tooling.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Clay | 87 |
| 4 | HubSpot | 85 |
| 5 | Claude Code | 99 |
| 6 | Grok Bot | 61 |
| 7 | Attention | 31 |
| 8 | Codex | 81 |
| 9 | Lovable | 57 |
| 10 | Attio | 50 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
No spike to explain. Forecasting has drifted down from February and sits near 1.3 percent, off 17.8 percent over 90 days and roughly flat in the last 30. The posts that land are about mechanics: what belongs in a CLAUDE.md, whether legal and procurement clear this month, and Creatio comparing AI forecasts to rep forecasts.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Claude Code | 99 |
| 4 |  Clari | 34 |
| 5 | Clay | 87 |
| 6 | Gong | 63 |
| 7 | Codex | 81 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Grok Bot | 61 |
| 10 | Lemlist | 49 |
How marketing teams use AI, where it helps and how it changes the job.
The line drifted down from 1.55% in February to 0.85% in July, then turned up 53% over the last 30 days. What carries it is who does the job: Marvin Chow hiring Google's first marketing engineer, Andy Mowat taking the CMO seat at Inflection.io, Tom Wentworth arguing SaaStr's event brand is itself marketing.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 51 |
| 2 | HubSpot | 85 |
| 3 | Claude Code | 99 |
| 4 |  Buffer | 27 |
| 5 | LangChain | 45 |
| 6 | Cursor (Anysphere) | 78 |
| 7 |  Framer | 35 |
| 8 | Granola | 47 |
| 9 | Lovable | 57 |
| 10 | Salesforce | 91 |
Starting and running a business, including the economics and experience of the founder path.
Eight months between 0.86% and 1.4%, with no event moving it either way. The steady supply is personal rather than commercial: Peep Laja's Panama origin story, Dave Gerhardt taking a day off to chaperone a field trip, Debra Aho Williamson posting a solopreneur's week of wins. Up 50% over the last 30 days, down 16% over 90.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | Clay | 87 |
| 4 | Codex | 81 |
| 5 | Lovable | 57 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | HubSpot | 85 |
| 8 | Substack | 52 |
| 9 | Grok Bot | 61 |
| 10 | Instantly | 60 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Share peaked near 3 percent in April, when HockeyStack and Fin launched revenue agents a week apart. It fell through the summer to under 1 percent in August, and the posts since then are smaller. The last 30 days are flat, so the fall has stalled rather than reversed.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 87 |
| 3 | Salesforce | 91 |
| 4 | HubSpot | 85 |
| 5 | Sumble | 33 |
| 6 | Nooks | 48 |
| 7 | Rox | 31 |
| 8 | Attention | 31 |
| 9 | Clarify | 29 |
| 10 | Codex | 81 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product marketing's share has slid since February, from 2.8 percent down to about 1.3 percent, with no single event behind the drop. The L30 move is still negative at 8 percent, so the drift has not stopped. What does get posted is steady craft work: launch tiering, packaging under faster shipping, and competitive intelligence pulled from buyers.
Posts to understand this · as of Sep 15
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 63 |
| 2 | Profound | 51 |
| 3 | Salesforce | 91 |
| 4 |  Navattic | 23 |
| 5 | Canva | 48 |
| 6 | Claude Code | 99 |
| 7 | HubSpot | 85 |
| 8 | Lovable | 57 |
| 9 | Semrush | 48 |
| 10 | Codex | 81 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales leadership held about 2.2 to 2.4 percent of the conversation from February through May, then dropped to roughly 1.5 percent in June and drifted lower through August. The last 30 days are down 35 percent, with current share at 1.05 percent. These three posts show what leaders are arguing about, not why the share fell.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Clay | 87 |
| 4 | Gong | 63 |
| 5 | Replit | 54 |
| 6 | Twilio | 39 |
| 7 | Attention | 31 |
| 8 | Outreach | 45 |
| 9 | 1mind | 37 |
| 10 | AI Ark | 43 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing swings month to month rather than trending, and it is down 9 percent over 30 days. The spring highs came from build posts: Claude Code content engines and terminal-first blog stacks with their own source-of-truth files. The live argument has since shifted to whose voice you publish rather than how much you produce.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 85 |
| 3 | Clay | 87 |
| 4 | Gong | 63 |
| 5 | Ahrefs | 49 |
| 6 | Semrush | 48 |
| 7 | AirOps | 37 |
| 8 | Apify | 53 |
| 9 | Attio | 50 |
| 10 |  Customer.io | 37 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
The share has drifted down since February and now sits near 1 percent. What remains is platform talk, not category talk. Zoom claims leader status in IDC's revenue orchestration MarketScape, and Momentum says it powers the data foundation for Salesforce's new Hunter agent. The practitioner post skips the tools and runs call transcripts through Claude.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 63 |
| 2 | Salesforce | 91 |
| 3 | HubSpot | 85 |
| 4 | Claude Code | 99 |
| 5 | Clay | 87 |
| 6 | Instantly | 60 |
| 7 | Outreach | 45 |
| 8 | Nooks | 48 |
| 9 | HeyReach | 51 |
| 10 | Lemlist | 49 |
How companies create demand, build trust and reach buyers at other businesses.
Down 37 percent over 90 days from a March high of 2.6 percent. Nothing broke. The conversation split into its parts, and the parts now carry it: Kieran Flanagan's playbook routes B2B marketing into paid, AEO citations, founder social and creators. Matt Heinz argues marketers sold the MQL themselves, and LinkedIn's research puts trust with peers over brands.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | CHEQ | 15 |
| 3 |  HG Insights | 26 |
| 4 |  Meltwater | 24 |
| 5 | Optimizely | 28 |
| 6 |  TrustRadius | 26 |
| 7 | Webflow | 47 |
| 8 | Attio | 50 |
| 9 | Chili Piper | 33 |
| 10 | Claude Code | 99 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search Strategy ran under 1% through winter, dipped in April, then climbed in May and June to a 1.42% peak. July and August are the only completed months of decline. September is partial at 19 days, and the last 30 days are down 18.5%, while the window still runs 7.7% above the prior 90 days.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | HubSpot | 85 |
| 3 | Ahrefs | 49 |
| 4 |  SparkToro | 26 |
| 5 | Ranked AI | 35 |
| 6 | AirOps | 37 |
| 7 |  Amazon Bedrock AgentCore | 23 |
| 8 | Claude Code | 99 |
| 9 | Clay | 87 |
| 10 |  DataForSEO | 25 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
This started at 0.06 percent in February and now runs near 1 percent, up 29 percent over 90 days. One launch did not do that; a sequence of them did. Relevance AI shipped programmatic GTM in March, HubSpot's CLI reached beta in June, and in August Jordan Crawford said Clay's missing CLI was finally fixed.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Claude Code | 99 |
| 3 | Codex | 81 |
| 4 | Salesforce | 91 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Grok Bot | 61 |
| 7 | HubSpot | 85 |
| 8 | Instantly | 60 |
| 9 | Nooks | 48 |
| 10 | Apify | 53 |
The software stack marketers use to plan, run, measure and improve their work.
Martech has bounced between 0.85 and 1.5 percent all year and is down 29 percent over 90 days. The word keeps losing ground to architecture. Joe Chernov warns that unbundling into agents rebundles like cable, Phil Gamache spent 40,000 words on marketing architecture, and Gradial brought Scott Brinker to Dreamforce to map what follows 15,505 tools.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | GrowthLoop | 30 |
| 3 | Docket | 29 |
| 4 | HubSpot | 85 |
| 5 | Codex | 81 |
| 6 | Twilio | 39 |
| 7 |  Augment Code | 17 |
| 8 | Claude Code | 99 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Customer.io | 37 |
The durable knowledge and memory an agent can use across tasks and sessions.
This one never spiked. It drifted between 1.1% and 1.7% all year and sits down 28% on L30. Vendor launches carry it, not argument: Perplexity's Brain in June, Writer's Palmyra X6 in August. Denise Persson's Cannes read names the same idea from the enterprise side, a governed context layer.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 91 |
| 3 | Clay | 87 |
| 4 | HubSpot | 85 |
| 5 | Sumble | 33 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Attention | 31 |
| 8 | Gong | 63 |
| 9 | Clarify | 29 |
| 10 |  Clearskies | 21 |
How companies sell to other companies and how business buyers make decisions.
This one moves in a band rather than a trend, between 0.87 and 1.35 percent all year, down 3.1 percent in the last 30 days. Argument holds it up more than news: Morgan Ingram on buyers tiring of AI slop, Gong's data on AI deals up 85 percent while hiring talk stays flat, and Aligned's $60M Series B.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Clay | 87 |
| 3 | HG Insights | 26 |
| 4 | Salesforce | 91 |
| 5 | Semrush | 48 |
| 6 | TrustRadius | 26 |
| 7 |  AiSDR | 21 |
| 8 | Amazon Bedrock AgentCore | 23 |
| 9 | Apify | 53 |
| 10 | Attio | 50 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Salesforce is the engine here. Martin Kihn's post on hosted MCP servers reaching GA revived a conversation that had gone quiet by July, and Dreamforce extended it, with Gainsight taking its headless strategy onto AgentExchange. Rahul Pathak's June case, that agents call APIs and ignore your UX, is the frame everyone borrows. Up 56% over the last 30 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | ZoomInfo | 50 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 85 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Replit | 54 |
| 8 | Apify | 53 |
| 9 | Codex | 81 |
| 10 | Airtable | 48 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth marketing share slid most of the year, from 2.8% in March to 0.6% in August, a 77% drop over six months. The last 30 days are up about 52%. What is left is mostly hiring talk: growth teams staffing up at Anthropic and Clay, plus a warning that scattered AI use is dragging marketing teams down.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Webflow | 47 |
| 2 | Optimizely | 28 |
| 3 | HubSpot | 85 |
| 4 | Claude Code | 99 |
| 5 | Ahrefs | 49 |
| 6 | AirOps | 37 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Granola | 47 |
| 9 | Lovable | 57 |
| 10 | Semrush | 48 |
The work of earning awareness, trust and preference for a company over time.
Steady near 1.6 to 2.0% through June, then down since July, and off another 18% in the last 30 days. No event explains it. The posts are arguments about definition and funnel design rather than news, and that kind of conversation does not refresh itself.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Semrush | 48 |
| 3 | Claude Code | 99 |
| 4 | Clay | 87 |
| 5 | Gong | 63 |
| 6 | Ahrefs | 49 |
| 7 |  Fibbler | 34 |
| 8 | Lovable | 57 |
| 9 | Salesforce | 91 |
| 10 | 6sense | 40 |
Choosing which model should run each task based on cost, quality, speed or risk.
Roughly doubled over the quarter on a run of product news: Cognition's Devin Fusion hybrid harness in June, Cursor Router in July, then OpenRouter joining Stripe in August with 10T tokens a day across 400+ models. L30 is down about 17%, so the topic looks like it has settled at the higher level rather than kept climbing.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | OpenRouter | 49 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Salesforce | 91 |
| 4 | Claude Code | 99 |
| 5 | Clay | 87 |
| 6 | Vercel | 59 |
| 7 | beehiiv | 48 |
| 8 | Codex | 81 |
| 9 |  GitHub Copilot | 35 |
| 10 | Runway | 33 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
This one holds a band rather than trends, roughly 0.7% to 1.4% since February, with the L30 move up 55%. It runs on the seat-based software argument, not on launches: DocuSign's pricing lead explaining a new credit model, Peep Laja tying about $2T in lost software market cap to agents, and beehiiv's Tyler Denk listing the SaaS he still pays for.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | HubSpot | 85 |
| 3 | Intercom | 43 |
| 4 | Replit | 54 |
| 5 | Claude Code | 99 |
| 6 | Clay | 87 |
| 7 | Lovable | 57 |
| 8 | Twilio | 39 |
| 9 | Vercel | 59 |
| 10 | OpenRouter | 49 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing ops hit its high in March and has fallen through every quarter since, down 38 percent over 90 days and 11 percent over 30. Nothing replaced that March surge. The posts still here describe a management problem rather than a buying one: teams running 40 to 50 unconnected agents, and org change that lags the tools.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Docket | 29 |
| 2 | GrowthLoop | 30 |
| 3 | Salesforce | 91 |
| 4 | HubSpot | 85 |
| 5 | Lovable | 57 |
| 6 | MoEngage | 23 |
| 7 | 1mind | 37 |
| 8 | Augment Code | 17 |
| 9 | Clay | 87 |
| 10 | Twilio | 39 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Share jumped in March, held a plateau near 0.45% through July, then stepped up again in August. No single event explains it; vendors keep opening programs. Lovable launched a solutions partner program in July and Moloco named a dozen founding agency partners in August. Will Taylor's Catalyst26 readout names the pressure behind them: partnership leaders want predictable pipeline, and co-sell alone cannot deliver it.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Clay | 87 |
| 3 | Salesforce | 91 |
| 4 | Tally | 32 |
| 5 | Replit | 54 |
| 6 |  Typeform | 29 |
| 7 | Attio | 50 |
| 8 |  Bolt.new (StackBlitz) | 24 |
| 9 |  Calendly | 37 |
| 10 | Crossbeam | 24 |
Reusable instructions that teach an agent how to complete a specific kind of task.
The May peak followed people giving skill libraries away: Eric Nowoslawski's 29-skill cold email repo in April, then lemlist packaging seven years of outbound data from 30,000 customers into 30 free Claude skills. Vercel's August agent plugins folded skills and MCP into one open standard with AWS, Cursor, GitHub and OpenAI. Share is down 43.6% over the last 30 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Claude Code | 99 |
| 3 | Codex | 81 |
| 4 | Profound | 51 |
| 5 | Clay | 87 |
| 6 | Apify | 53 |
| 7 | Gong | 63 |
| 8 | Granola | 47 |
| 9 | HeyReach | 51 |
| 10 | Higgsfield | 38 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement is not spiking or crashing, it is grinding down, from about 2 percent in February to under 1 now and off 38 percent in the last 30 days. The talk has turned critical. Sam Jacobs and Keenan on quota attainment falling from 60 percent to 20 while enablement spend rose roughly 7x, with the wins posted as displacement deals and ramp-time math.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Codex | 81 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Gong | 63 |
| 5 | Grok Bot | 61 |
| 6 |  Highspot | 29 |
| 7 | HubSpot | 85 |
| 8 | Nooks | 48 |
| 9 |  Seismic | 28 |
| 10 |  CallRail | 20 |
A go-to-market operating model where agents execute work across the revenue motion.
The curve is choppy, not a climb. August nearly doubled July, 0.338 to 0.63, with the adoption gap argument doing the work. September is only 17 days observed, but the last 30 days are up 42.5%, carried by Clay's $115M round and its API and CLI release.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Codex | 81 |
| 5 | Claude Code | 99 |
| 6 | HubSpot | 85 |
| 7 | 1mind | 37 |
| 8 | n8n | 58 |
| 9 | Clari | 34 |
| 10 | Common Room | 43 |
The point where a product solves a real need for a market that will buy it.
PMF talk has thinned all year, from 1.8 percent of the conversation in February to roughly half that since July, and the last 30 days are down again. No single event moved it. What is left is redefinition rather than debate: Andrew Chen arguing an $800M pre-revenue raise breaks the ship-fast playbook, ClickUp claiming fit now refreshes every few weeks, Day AI finding its stickiest users were enterprise buyers.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 87 |
| 3 | HubSpot | 85 |
| 4 | OpenClaw | 50 |
| 5 | Salesforce | 91 |
| 6 |  Bland | 19 |
| 7 | Codex | 81 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Devin | 37 |
| 10 |  Fireflies | 35 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales ops has stayed in a narrow band all year, between 0.59% and 1.02%, with the L30 move down 26%. The subject is headcount math rather than tooling: whether a rep is worth $870K, whether two AEs with four SDRs beat four AEs hunting alone, and how ElevenLabs reached $600M ARR with quotas set at 20x base.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | ElevenLabs | 50 |
| 3 | HubSpot | 85 |
| 4 | Claude Code | 99 |
| 5 | Clay | 87 |
| 6 |  Monaco | 26 |
| 7 | Chili Piper | 33 |
| 8 | Cline | 26 |
| 9 |  Guru | 20 |
| 10 | Lovable | 57 |
Scoring leads and accounts to decide who deserves attention first.
The decline is steady and nothing triggered it. Share ran between 1.4% and 1.8% from February to May, then halved by August, and the last 30 days are down 39.5%. The conversation moved to signals and intent, with Clay launching topic intent to name the people researching a topic, while the old models stay distrusted.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Salesforce | 91 |
| 3 | Clay | 87 |
| 4 | Attio | 50 |
| 5 | FullEnrich | 41 |
| 6 | 6sense | 40 |
| 7 | Apify | 53 |
| 8 | Claude Code | 99 |
| 9 | Instantly | 60 |
| 10 | Lemlist | 49 |
Systems where several agents divide a job, coordinate their work and combine the result.
This one has hovered near 1% all year with no event to lift it, and the last 30 days are down 43.3%. The proof points come from vendors: Mercor's 100-subagent run finishing a 50-page diligence deck in 4 hours 39 minutes, Workato expanding Airo. Jonathan M K. names the ceiling, that agent architecture is not a value proposition.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | ElevenLabs | 50 |
| 4 | Grok Bot | 61 |
| 5 | Profound | 51 |
| 6 | AI Ark | 43 |
| 7 | AiSDR | 21 |
| 8 | Apify | 53 |
| 9 |  Base44 | 20 |
| 10 |  BuiltWith | 33 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting share climbed from 0.6% in March to a June peak of 1.31%, then dropped to 0.81% in July and 0.78% in August. September is only 16 days in, so read direction from the last 30 days: down about 21%. The posts here make the same argument from three angles, that copy is rarely the real problem.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 85 |
| 3 | Instantly | 60 |
| 4 | AI Ark | 43 |
| 5 | Apollo.io | 51 |
| 6 | Clay | 87 |
| 7 | HeyReach | 51 |
| 8 | FullEnrich | 41 |
| 9 | Lemlist | 49 |
| 10 | Nooks | 48 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Share has held between 0.83% and 1.05% since May with no launch owning it, and the last 30 days are down 33.7%. The term keeps getting stretched, to forward deployed experts and to marketing engineers, while vendors now sell against it: Rox pitches revenue agents that need no FDEs. The plateau is the shape.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | ElevenLabs | 50 |
| 4 | Gamma | 42 |
| 5 | Lovable | 57 |
| 6 | Replit | 54 |
| 7 | Twilio | 39 |
| 8 | Baseten | 45 |
| 9 | Bland | 19 |
| 10 | Calendly | 37 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound Systems peaked in May near 2.1% share and fell through the summer, and the last 30 days are down 43%. The posts still landing in late August and September do not sell an outbound stack. They describe outbound folded into something larger: one consolidated funnel at Xbow, one platform for data and deliverability, and outbound run off marketing signals.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 87 |
| 3 | Salesforce | 91 |
| 4 | Prospeo | 51 |
| 5 | Zapier | 53 |
| 6 | Apify | 53 |
| 7 | Apollo.io | 51 |
| 8 | Codex | 81 |
| 9 |  ColdIQ | 28 |
| 10 |  Explorium | 28 |
Rules, triggers and workflows that execute marketing programs across systems.
The decline stopped. Share halved between February and May, then held between 0.47 and 0.63 for four straight months, and it is flat again over the last 30 days. The floor is the story. Customer.io's G2 momentum win, Jon Miller's rework of Brinker's stack rings, Movable Ink's programmatic CRM pitch. The category is being renamed, not abandoned.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Salesforce | 91 |
| 3 |  ActiveCampaign | 31 |
| 4 | Attio | 50 |
| 5 | Clay | 87 |
| 6 | Gong | 63 |
| 7 | HeyReach | 51 |
| 8 | Instantly | 60 |
| 9 | Intercom | 43 |
| 10 | Nooks | 48 |
A permanently free product tier designed to attract users and convert some to paid plans.
July was almost silent at 0.08%, then OpenAI reported ChatGPT ads at $1 billion annualized run rate in under 200 days, explicitly to fund free access. Share is up 168.7% over the last 30 days. Brian Stempeck called the shape back in January: the money sits with the 90% who never pay.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Canva | 48 |
| 2 | Salesforce | 91 |
| 3 | Claude Code | 99 |
| 4 | Codex | 81 |
| 5 | Lovable | 57 |
| 6 | Replit | 54 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | HubSpot | 85 |
| 9 | Intercom | 43 |
| 10 | Salesloft | 41 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-serve held up in August around Bending Spoons agreeing to buy Airtable for $1.285B, with Elena Verna reading it as the classic PLG-to-enterprise trap. That argument carried the month and then faded, and the last 30 days are down 29.1 percent. Underneath it, the topic is back to steady motion-design debate rather than news.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Calendly | 37 |
| 3 | HubSpot | 85 |
| 4 |  Qualified | 27 |
| 5 | Replit | 54 |
| 6 | Canva | 48 |
| 7 | Codex | 81 |
| 8 | Gamma | 42 |
| 9 | Lovable | 57 |
| 10 | Salesloft | 41 |
B2B brands paying creators and independent voices to reach trusted audiences.
There is no trend here, just a recurring argument that flares and settles. Share has bounced between 0.56% and 0.97% all year, down 41% over the last 30 days against a roughly flat 90. August's cluster came from Clay naming a creator in residence and from program design posts, set against the view that paid B2B posts are opinions for sale.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 85 |
| 4 | Granola | 47 |
| 5 | HeyReach | 51 |
| 6 |  Userpilot | 22 |
| 7 | Vector | 39 |
| 8 | 1mind | 37 |
| 9 | AirOps | 37 |
| 10 | Apify | 53 |
AI agents that discover, compare and buy products on a person's behalf.
Agents as Buyers has held a narrow band all year, roughly 0.4% to 0.9%, with a March high and no trend since. The plateau is the point. Retailers moved past debating whether agentic commerce matters, per NRF, and the open questions got practical: which protocol wins, and which purchases an agent can finish alone.
Posts to understand this · as of Sep 14
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Exa.ai | 44 |
| 4 | Hermes Agent | 36 |
| 5 | Midjourney | 36 |
| 6 | Profound | 51 |
| 7 |  Similarweb | 34 |
| 8 |  StackAdapt | 20 |
Rule-based software that moves business work through predefined steps and systems.
Share fell steadily from 1.1% in February to 0.49% in July, then rebounded to 0.62% in August. The last 30 days are down 14.2%, so that rebound has not held, and September is only 20 days in. The phrase still shows up in seller advice, vendor skills posts, and product launches.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | n8n | 58 |
| 2 | Claude Code | 99 |
| 3 | Clay | 87 |
| 4 | Salesforce | 91 |
| 5 | Supabase | 46 |
| 6 | Apollo.io | 51 |
| 7 | Exa.ai | 44 |
| 8 | HubSpot | 85 |
| 9 | Instantly | 60 |
| 10 | Nooks | 48 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Six months in a steady band near 0.8%, then a step down in August and a 16.3% drop over the last 30 days. The case studies did not stop. Davide Grieco counted 4,756 registrations from one Clay post, Diandra Escobar published a four-bucket posting funnel, Charlotte Lloyd described buyers who follow silently. The tactic looks settled, so fewer people argue about it.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 87 |
| 3 | HubSpot | 85 |
| 4 | RB2B | 48 |
| 5 | Ahrefs | 49 |
| 6 | Granola | 47 |
| 7 | Grok Bot | 61 |
| 8 | HeyReach | 51 |
| 9 | Instantly | 60 |
| 10 | Nooks | 48 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
The rise ran March to May and has eased since, down 30.4% over the last 30 days. The talk moved from AI-native as a new species to who gets hired: Tom Wentworth on founders wanting AI-pilled marketers who operate as ICs, Andy Mowat taking the CMO seat at Inflection. Stevie Case's counterpoint is that AI-native companies are rebuilding classic GTM orgs.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Claude Code | 99 |
| 3 | Clay | 87 |
| 4 | Salesforce | 91 |
| 5 | Codex | 81 |
| 6 | Grok Bot | 61 |
| 7 | Nooks | 48 |
| 8 | Rox | 31 |
| 9 | ZoomInfo | 50 |
| 10 | 1mind | 37 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales tech has drifted down all year, from 1.07 percent in February to 0.57 in August, with the last 30 days off another 6 percent. The label is losing ground, not the market. Gong's own post rejects "another sales tool" in favor of a revenue AI OS, and the real-time guidance argument stakes out live conversations as the next category.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Outreach | 45 |
| 3 | Claude Code | 99 |
| 4 | Gong | 63 |
| 5 | Instantly | 60 |
| 6 | Attention | 31 |
| 7 | Clay | 87 |
| 8 | Explorium | 28 |
| 9 | FullEnrich | 41 |
| 10 | Nooks | 48 |
Time-limited access that lets a buyer test a product before paying.
Share fell hard between February and April, then flattened into a narrow band and stayed there. The plateau is the point: trials are settled infrastructure, discussed through funnel math and the occasional access change, like Grok Bot opening a limited free trial to everyone in August. The last 30 days are down 18%.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 81 |
| 3 | Salesforce | 91 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Firecrawl | 39 |
| 6 | HubSpot | 85 |
| 7 | ActiveCampaign | 31 |
| 8 | Amazon Bedrock AgentCore | 23 |
| 9 | Apify | 53 |
| 10 | Attio | 50 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
A straight slide from 1.9% in February to 0.63% in August, with L30 off 43.9%. The decline tracks a shift in what people argue about: Kyle Poyar's data shows SDR job posts down 21% while OpenAI and Cursor doubled SDR headcount, and Kyle Coleman writes off AI impersonating reps entirely. The role stopped being the fight.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Gong | 63 |
| 3 | Nooks | 48 |
| 4 | Clay | 87 |
| 5 | HubSpot | 85 |
| 6 | Outreach | 45 |
| 7 | Clari | 34 |
| 8 | Claude Code | 99 |
| 9 | Instantly | 60 |
| 10 | Salesloft | 41 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Down 44 percent over 90 days from May's peak, and the surviving posts changed register. Peter Caputa's marketing OS already automates production and is stuck on measurement. Kieran Flanagan mocks the agent-swarm content machine. Eli Schwartz points at John Mueller's warning that AI spam hurts a site's reputation and takes significant time and effort to undo.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Claude Code | 99 |
| 3 | Clay | 87 |
| 4 | Salesforce | 91 |
| 5 | Semrush | 48 |
| 6 | 6sense | 40 |
| 7 | AI Ark | 43 |
| 8 | Ahrefs | 49 |
| 9 | AirOps | 37 |
| 10 | Amazon Bedrock AgentCore | 23 |
Deciding what to build, why it matters and which product bets come first.
Product strategy talk swings month to month instead of trending. Share has moved between 0.38 and 0.78 percent since February with no sustained direction, and the last 30 days are down 17 percent. The posts below show what the talk consists of: services economics, the upstream half of product marketing, and niche category bets.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Codex | 81 |
| 3 | Salesforce | 91 |
| 4 | Claude Code | 99 |
| 5 | Devin | 37 |
| 6 | Exa.ai | 44 |
| 7 | Grok Bot | 61 |
| 8 | Hermes Agent | 36 |
| 9 |  Netlify | 27 |
| 10 | OpenClaw | 50 |
Websites and docs structured so AI crawlers and agents can read and use them.
Share climbed into April, held near that level through June, then stepped down in July and has stayed lower since. The last 30 days are down 16 percent. What still gets posted is mechanical: keeping bot rules in sync, making pages fast enough for crawlers to read, and building web layers aimed at agents.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 49 |
| 2 | HubSpot | 85 |
| 3 | Substack | 52 |
| 4 | 6sense | 40 |
| 5 | AirOps | 37 |
| 6 | Calendly | 37 |
| 7 |  Cloudflare Workers | 17 |
| 8 | Docket | 29 |
| 9 |  Metronome | 25 |
| 10 | Peec AI | 28 |
Multi-step work planned and executed by agents instead of fixed automation rules.
A flat oscillating band between 0.34% and 0.62% all year, with the last 30 days off 15%. HubSpot launching Agent Hub and Agent Builder in July was the largest single post here and the monthly line barely registered it. The talk has shifted to what is missing: a context layer, and Elaine Zelby's point that behavior change blocks teams before tooling does.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Apollo.io | 51 |
| 3 | Claude Code | 99 |
| 4 | Codex | 81 |
| 5 | Prospeo | 51 |
| 6 | Salesforce | 91 |
| 7 | Attio | 50 |
| 8 | Explorium | 28 |
| 9 | FullEnrich | 41 |
| 10 | Gong | 63 |
AI agents that create, launch, buy and optimize advertising.
February spiked at 0.56% on OpenAI's ChatGPT ads test, then collapsed to 0.11% by April. The rebuild since is different in kind: StackAdapt selling early programmatic access in May, AppsFlyer wiring Grubhub's installs and purchases into measurement in August. L90 is up 73.6% on that plumbing, though L30 has cooled 30%.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Codex | 81 |
| 3 | OpenClaw | 50 |
| 4 | Similarweb | 34 |
| 5 | 6sense | 40 |
| 6 | Clay | 87 |
| 7 | ColdIQ | 28 |
| 8 |  Criteo | 20 |
| 9 |  Deepgram | 24 |
| 10 | Gong | 63 |
Approval and review steps that keep a person involved in an agent's work.
Human in the loop has swung between 0.36 and 0.83 percent of the conversation every completed month this year, with no direction in it. The last 30 days are close to flat at plus 2.2 percent, while the 90 day move is down 28.6 percent. When it does surface, it is people trying to make the phrase specific.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | OpenClaw | 50 |
| 2 | Claude Code | 99 |
| 3 | Clay | 87 |
| 4 | HubSpot | 85 |
| 5 | Salesforce | 91 |
| 6 | n8n | 58 |
| 7 | Ahrefs | 49 |
| 8 | Apify | 53 |
| 9 |  Ciro | 19 |
| 10 | Clarify | 29 |
Advantages that grow stronger as more people, data or participants join a product.
Share has fallen in every full month since February, from 1.9% down to under half a percent, with no single event behind it. The moat argument moved rather than died. Rahul Pathak says UX stopped being the defense once agents call APIs, while Salesforce and Sierra both recast the moat as proprietary data and accumulated context. L30 is down 26.9%.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Devin | 37 |
| 5 | Guru | 20 |
| 6 | Intercom | 43 |
| 7 | Lovable | 57 |
| 8 | Replit | 54 |
| 9 | Semrush | 48 |
| 10 |  ZoomInfo Chorus AI | 16 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
Down about 40% over 90 days from February's 1.5% high. Consolidation stopped being one argument and split into three: Rox's room of 75 RevOps leaders debating life without Salesforce, Jan Rasmussen's category-by-category tool map, Elric Legloire defending Snowflake's 24 tools across 300 SDRs. When the answer depends on scale, the slogan loses.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | HubSpot | 85 |
| 4 | ZoomInfo | 50 |
| 5 | Attio | 50 |
| 6 |  Bombora | 29 |
| 7 | Codex | 81 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Fireflies | 35 |
| 10 | Outreach | 45 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Up 41.7% over 90 days on a climb that ran from April through August, with the last 30 down 14%. The rise is vendor-led. Canva ran a joint enterprise workflow session with LinkedIn, WRITER staged a CMO fireside before its September launch, and Gradial hired three-time CMO Lynn Girotto on the argument that enterprise marketing has turned into ticket routing.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Profound | 51 |
| 3 | Claude Code | 99 |
| 4 | ZoomInfo | 50 |
| 5 | AI Ark | 43 |
| 6 | AiSDR | 21 |
| 7 | BuiltWith | 33 |
| 8 | CHEQ | 15 |
| 9 | Clay | 87 |
| 10 | Codex | 81 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
Flat for seven months between 0.51 and 0.66 percent, essentially unchanged over 90 days, and down 47 percent in the last 30. The steadiness comes from vendors publishing proof on a regular cadence rather than from incidents: OpenAI's automated red teamer, Cursor's AIUC-1 certification, Vanta selling continuous compliance against shadow AI.
Posts to understand this · as of Sep 15
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Midjourney | 36 |
| 4 | Claude Code | 99 |
| 5 | ElevenLabs | 50 |
| 6 | Hermes Agent | 36 |
| 7 | HubSpot | 85 |
| 8 | Salesforce | 91 |
| 9 | Canva | 48 |
| 10 | Devin | 37 |
The runtime around an agent that provides tools, state, controls and stopping rules.
Zero in February, then a saw-tooth between 0.27 and 0.57 with no accumulation. The 90 day move is flat, which tells you each bump is one launch rather than a building conversation. DeepSeek's harness v0.1 developer preview pulled 24,526 engagements by itself in August, after Databricks put Omnigent above the harness layer in June and Perplexity moved the runtime onto local hardware.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 91 |
| 4 | Cline | 26 |
| 5 | Grok Bot | 61 |
| 6 | LangChain | 45 |
| 7 | Vercel | 59 |
| 8 | AI Ark | 43 |
| 9 | Ahrefs | 49 |
| 10 | AiSDR | 21 |
Tracing and monitoring what a model or agent did during a production run.
Observability has held a narrow 0.3 to 0.46 percent band all year, and the L30 dip keeps it inside that band. The plateau is the finding. Intercom's Fin suite, Parloa Lens and Dataiku all push the category from the vendor side, and practitioners have not made it their own topic.
Posts to understand this · as of Sep 14
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 91 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | LangChain | 45 |
| 6 | Grok Bot | 61 |
| 7 | HubSpot | 85 |
| 8 | OpenClaw | 50 |
| 9 | Augment Code | 17 |
| 10 | Customer.io | 37 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
No trend here, just launches. Each bar tracks whatever shipped that month: Clay's research infrastructure inside Claude in January, the Grok Figma connector in July, Salesforce making hosted MCP servers generally available in August. Up 22.9% over 90 days and down 50.7% over the last 30, which is what a launch-driven line looks like.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Canva | 48 |
| 3 |  Cargo | 30 |
| 4 |  Enrich | 25 |
| 5 | Prospeo | 51 |
| 6 | Airtable | 48 |
| 7 | Apollo.io | 51 |
| 8 | Clay | 87 |
| 9 | Codex | 81 |
| 10 | Gamma | 42 |
Using AI to tailor outreach and marketing to each person at scale.
AI personalization has halved since February and is down 43 percent in the last thirty days. No event pushed it off a cliff; it drained. The pattern in what remains is that almost nobody is defending the phrase. The posts that still carry it are practitioners narrowing lists by hand or arguing the buyer got the worse end.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 91 |
| 3 | Codex | 81 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | ElevenLabs | 50 |
| 6 |  Lightfield | 24 |
| 7 | Outreach | 45 |
| 8 | Salesloft | 41 |
| 9 | Apify | 53 |
| 10 | Clay | 87 |
Founders running early sales themselves before handing the motion to a sales team.
This one spikes rather than trends. It nearly vanished in May, jumped in July when Peter Kazanjy opened Founding Sales copies to any founder rather than accelerator members, and has eased since, down 23% in the last 30 days. Without a resource or a hiring fight to gather around, there is no base under it.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | Codex | 81 |
| 4 | AI Ark | 43 |
| 5 | AirOps | 37 |
| 6 | Apify | 53 |
| 7 | Apollo.io | 51 |
| 8 |  BetterContact | 42 |
| 9 | Chili Piper | 33 |
| 10 | Cursor (Anysphere) | 78 |
The strategy of naming, defining and leading a new market.
Share slid through the spring, bottomed at 0.31 in July, then came back to 0.398 in August. The last 30 days are up 8.3 percent, so the line is holding rather than falling, even though L90 is still down 20.8 percent. September has only 18 days observed. New categories are still being named while practitioners argue the play is finished.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 63 |
| 2 |  Noble | 23 |
| 3 | Salesforce | 91 |
| 4 | 1mind | 37 |
| 5 | 6sense | 40 |
| 6 | Apify | 53 |
| 7 |  DemandScience | 23 |
| 8 | HubSpot | 85 |
| 9 | Lovable | 57 |
| 10 | Nooks | 48 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
Share of conversation has stayed between 0.2 and 0.9 percent all year, so monthly moves are small. May spiked to 0.84 percent, June fell to 0.31, July came back to 0.43, August settled at 0.32. The last 30 days are down 23 percent, and the posts are about operating detail: what an AI-first org buys, builds and staffs.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 91 |
| 3 | Clay | 87 |
| 4 | Apify | 53 |
| 5 | HubSpot | 85 |
| 6 | Lovable | 57 |
| 7 | n8n | 58 |
| 8 | AI Ark | 43 |
| 9 | Airtable | 48 |
| 10 | Attention | 31 |
Teams building internal software with AI instead of buying another SaaS product.
This one has never spiked. It sits in a narrow band between 0.36 and 0.53 percent all year and drifts gently down, off 28 percent in the last thirty days. The plateau is the story: the argument has moved past whether to build and onto where the line goes and what happens six months after version one.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | Augment Code | 17 |
| 4 | Customer.io | 37 |
| 5 | HubSpot | 85 |
| 6 |  Parallel | 36 |
| 7 | Sumble | 33 |
| 8 |  11x | 23 |
| 9 | AiSDR | 21 |
| 10 | AirOps | 37 |
How AI changes headcount, entry-level work and the jobs people still need to do.
Two spikes and then a long fade: 1.39% in March, 1.11% in May on Melissa Rosenthal's Gartner finding that 80% of large enterprises cut jobs with no ROI to show for it, then down to 0.34% by August. L90 is off 58.9%. The concrete cases replaced the alarm, like Notion folding nine GTM roles into four.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Salesforce | 91 |
| 3 | Lovable | 57 |
| 4 | Attention | 31 |
| 5 | Clarify | 29 |
| 6 | Clearskies | 21 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Grok Bot | 61 |
| 9 | Nooks | 48 |
| 10 | Rox | 31 |
A shared revenue knowledge layer that people and agents can query and update.
Share climbed from 0.37% in February to a 0.70% peak in June, the month Marcel Santilli wrote up a teammate's abandoned GTM brain. It has not held since: July fell to 0.35%, August recovered to 0.43%, and the trailing 30-day move is down 18.7% to 0.269%. ZoomInfo shipped a context layer into Slack in August while practitioners were still working out how to structure one.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Salesforce | 91 |
| 4 | Apify | 53 |
| 5 | Clay | 87 |
| 6 | Codex | 81 |
| 7 | HubSpot | 85 |
| 8 | Lovable | 57 |
| 9 | Ahrefs | 49 |
| 10 | Attio | 50 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
Down about 40% over 90 days from an April high of 0.90. The vendor moves are still landing, Hightouch's Lifecycle Studio in June and Gainsight's retention argument at Dreamforce, but they are not pulling the conversation with them. Bruno Estrella names the drift from the inside: ten years in growth marketing, now pointed at GTM engineering instead.
Posts to understand this · as of Sep 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | ActiveCampaign | 31 |
| 3 | GrowthLoop | 30 |
| 4 | RB2B | 48 |
| 5 | beehiiv | 48 |
| 6 | AI Ark | 43 |
| 7 |  Adobe Marketo | 25 |
| 8 | Ahrefs | 49 |
| 9 | Airtable | 48 |
| 10 | Apify | 53 |
Writing and structuring the instructions a model follows.
Share has drifted down all year, from 1.1% in February to 0.63% in August, and the last 30 days are off 53%. The posts show vendors renaming the work: DevRev sells context engineering, Kiro scores system prompt behavior with a judge pipeline. Semrush still ships a prompt library, so the older frame has not gone away.
Posts to understand this · as of Sep 15
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Granola | 47 |
| 4 | HubSpot | 85 |
| 5 | Salesforce | 91 |
| 6 | Attio | 50 |
| 7 | Canva | 48 |
| 8 | Cline | 26 |
| 9 | Codex | 81 |
| 10 | Devin | 37 |
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
July was the outlier month at 0.45 percent, which is why L90 still reads up 123 percent while the last 30 days are down 43.7. Recent posts keep the theme alive without rebuilding that volume: bolt.new's Forge mode running open models with Arcee AI, and Christopher Lochhead arguing the big labs fear commoditization. Small base, sharp swings.
Posts to understand this · as of Sep 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 81 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 61 |
| 5 | Salesforce | 91 |
| 6 | Hermes Agent | 36 |
| 7 | Airtable | 48 |
| 8 | Attention | 31 |
| 9 | Baseten | 45 |
| 10 | Canva | 48 |
How sales teams use AI and how it changes the work of selling.
The broad framing is emptying out, from 1.43% in February to 0.40% in August, with L30 down 59.6%. Individual launches still land hard, Austin Hughes repositioning Unify for GTM engineers in June and Yuriy Zaremba betting his company on the Ami agent in September. The launches keep coming, the general category talk does not.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Apollo.io | 51 |
| 2 | Attention | 31 |
| 3 | Clari | 34 |
| 4 | Claude Code | 99 |
| 5 | Explorium | 28 |
| 6 | FullEnrich | 41 |
| 7 | HubSpot | 85 |
| 8 | Instantly | 60 |
| 9 | Lemlist | 49 |
| 10 | Lovable | 57 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory oscillates in a narrow band instead of trending: 0.59% in April, 0.16% in July, 0.36% in August, and L30 down 25.6%. No event moves it. The posts are one pitch from three angles, with Neil Weitzman costing a full-time CRO at $400-600k OTE against a fractional hire and Nico Druelle naming the advisor-builder handoff as where execution breaks.
Posts to understand this · as of Sep 18
Interfaces that let agents understand and operate software built for human users.
This one never settles. It runs from 0.07% in March to 0.32% in May, drops to 0.15% in August, and sits up 10.4% over 90 days with L30 down 29%. Shipping is what drives it. Adam counted Clay, Apollo, Webflow, 6sense, ZoomInfo, Clari, HubSpot and Outreach all releasing something an agent can call in one month.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Claude Code | 99 |
| 3 | Clay | 87 |
| 4 | HubSpot | 85 |
| 5 | ZoomInfo | 50 |
| 6 | Apify | 53 |
| 7 | Apollo.io | 51 |
| 8 |  Browser Use | 27 |
| 9 | Ciro | 19 |
| 10 | Clarify | 29 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
The thinnest curve in the set, and the most honest. HubSpot set the terms in April with per-outcome agent pricing, August was the floor at 0.09%, and L30 has turned up 30% off it. Henry Schuck explains the stall: in GTM there are too many steps between the software and a closed deal.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 91 |
| 2 | Clay | 87 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Intercom | 43 |
| 5 | ZoomInfo | 50 |
| 6 | Apify | 53 |
| 7 | Bland | 19 |
| 8 | Canva | 48 |
| 9 | Frontier | 22 |
| 10 | HubSpot | 85 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
Flat all year under 0.2%, then August at 0.894%. Anthropic's watermarking FAQ caused it, with the EU AI Act as the forcing function and Synthesia confirming Article 50 marking on every relevant video. This was a compliance news event, not a standing theme, and the L30 move is down 67.1%.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Clay | 87 |
| 3 | Higgsfield | 38 |
| 4 | HubSpot | 85 |
| 5 | Salesforce | 91 |
| 6 | Substack | 52 |
| 7 | ZoomInfo | 50 |
| 8 | 6sense | 40 |
| 9 | Airtable | 48 |
| 10 | Ciro | 19 |
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent loops sat under 0.12% share through May, then jumped to 0.40% in June and held at 0.37% in July. The vendor launches land on that plateau and after it, not ahead of the step. Share has fallen since, down about 51% over the last 30 days, while the tooling keeps shipping.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | AssemblyAI | 33 |
| 2 | beehiiv | 48 |
| 3 | Claude Code | 99 |
| 4 | Clay | 87 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Devin | 37 |
| 7 | Lovable | 57 |
| 8 | OpenClaw | 50 |
| 9 | Vercel | 59 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
Down 46.4% over 90 days and 59% over the last 30, with no single event behind it. The complaint has not gone away, it has moved into craft. Rob Kaminski hears "everyone sounds the same with AI" across 51 founder calls, and Josh Braun is busy rewriting the cold email opener a prospect has already read 40 times this week.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 81 |
| 2 | Salesforce | 91 |
| 3 | AirOps | 37 |
| 4 | Claude Code | 99 |
| 5 | Semrush | 48 |
| 6 |  Viktor | 31 |
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
Share sat near zero through spring, then jumped in July as a Pangram study of LinkedIn slop circulated, and held through August alongside vendor claims about platform detection features. The last 30 days are down 66.6%, and September is still partial. The whole line moves inside a 0.3% band, so the base is tiny.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Substack | 52 |
| 3 | Codex | 81 |
| 4 | Cursor (Anysphere) | 78 |
| 5 |  Grammarly | 28 |
| 6 | Grok Bot | 61 |
| 7 | Replit | 54 |
| 8 | Similarweb | 34 |
The online channel mix used to reach, convert and retain customers.
A small, noisy line that peaks in February at 0.38% and again in June at 0.29%, with L30 down 39.1%. It shows up as a look backward rather than news. Rand Fishkin maps what zero-click made useless, Tom Wentworth lines AI up with email in 1995 and mobile in 2007, and louisgrenier calls the label a treadmill.
Posts to understand this · as of Sep 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 85 |
| 2 | Claude Code | 99 |
| 3 | Frontier | 22 |
| 4 | Grok Bot | 61 |
| 5 | HG Insights | 26 |
| 6 | Midjourney | 36 |
| 7 | Replit | 54 |
| 8 |  The Trade Desk | 22 |
AI-generated creators, avatars and user-style content used in marketing.
The April peak sits well above everything since, and share has more than halved over 90 days. The visible activity is distribution, not debate. HeyGen went native inside Canva in May, Lovable shipped a HeyGen connector two weeks later, and by September the posts are operators testing avatars of themselves. The last 30 days tick up 21.7% off a low base.
Posts to understand this
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing showed up in April, topped out in July at 0.47 percent, and has fallen hard since, with the last 30 days down 76.3 percent. The word mostly got used to be argued against. Sierra countered with outcomemaxxing, Databricks with valuemaxxing, and Wade Foster cited Uber burning its 2026 AI budget in four months.
Posts to understand this · as of Sep 19
Brands use human authorship and craft as a reason to trust or value their work.
This one never gets big and never goes away. It has run between zero and 0.17% since February and is down 43% in the last 30 days. Every post is a person making a case rather than a company shipping something. The largest is Amos Bar-Joseph's marketplace, which sells human-crafted operator skills to agents.
Posts to understand this · as of Sep 17
| Brand | GTM Index | |
|---|---|---|
| 1 | Attention | 31 |
| 2 | Clarify | 29 |
| 3 | Clay | 87 |
| 4 | Clearskies | 21 |
| 5 | Grok Bot | 61 |
| 6 | Nooks | 48 |
| 7 | Rox | 31 |
| 8 | Sumble | 33 |
| 9 | Claude Code | 99 |
| 10 | Salesforce | 91 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
The line moves in bursts, not a trend. June's jump to 0.25% came and went, and the last 30 days are down by half. What sits underneath is AI visibility: G2's AEO event and LinkedIn review verification in March, Ross Simmonds arguing visibility is compounded distribution, Tyrona Heath arguing volume is not a trust signal.
Posts to understand this · as of Sep 18
The argument over requiring a form before someone can access useful content.
A long slide, from 0.305% in February to 0.084% in August, down 59.4% over the last 30 days. The argument is settled enough that people now talk about what replaces the form: Amanda Natividad's rule to ungate the argument and gate the utility, Alex Lindahl's interactive mini apps built at Clay with Ploy.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | ActiveCampaign | 31 |
| 2 | HubSpot | 85 |
| 3 |  Ploy | 20 |
| 4 | Salesforce | 91 |
Using product activity to identify, time and support sales opportunities.
Barely registers, with nothing at all in April, May and July. Brendan Short's post-mortem explains why: $150M in venture, 14 startups, and none still operating independently as a PLG CRM after Pocus joined Apollo in March. What is left is plumbing work, like Dan Rosenthal's HubSpot build updating 60,000 records a day.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 87 |
| 2 | Attention | 31 |
| 3 | Clarify | 29 |
| 4 | Claude Code | 99 |
| 5 | Clearskies | 21 |
| 6 | Codex | 81 |
| 7 |  Hightouch | 33 |
| 8 | HubSpot | 85 |
| 9 | Intercom | 43 |
| 10 |  Mixmax | 21 |
How model costs, services and agent work put pressure on software gross margins.
Software designed for agents to operate as the primary user.
Nothing before June, faint readings in July and August, nothing yet in September. The 700% 90-day move is arithmetic on a near-zero base. All three posts are vendors talking to themselves, Netlify, MotherDuck and Retool, and almost nobody replied, so the idea has vocabulary but not yet an audience.
Posts to understand this
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Claude Code peaked at 11.6% of the conversation in March and has roughly halved since, down 20% in the last 30 days. The talk did not turn negative, it turned comparative. Composio ran GPT-6 Astra across six harnesses and found similar success rates, and Marty Kausas wants the same model without the terminal.
Posts to understand this · as of Sep 16
Cursor is an AI code editor with agents that write, edit and review code.
Cursor's share drifted down all spring, from 3.3 percent in February to 2.3 percent in July. August pulled it back to 3.0 percent when the SpaceX acquisition closed, still under the February and March level. The last 30 days are down 17 percent, so the August lift reads as news, not a new baseline.
Posts to understand this
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay topped out at 6.7 percent in May, stepped down to 3.8 in July, and has held there for three months. The last thirty days are flat. The step matches a change in where the work happens. Long-time users are weighing Clay tables against Claude Code and Codex, and saying so out loud.
Posts to understand this
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n peaked in June after the May multi-year partnership that embedded it natively inside SAP's Joule Studio, then gave most of that back over the summer. The last 30 days are up 8.6%. The talk has shifted off n8n's own news and onto whether Clay workflows or Anthropic's Routines replace it.
Posts to understand this · as of Sep 12
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable's high was March, powered by making the product free for International Women's Day with Anthropic and the SheBuilds events around it. It bottomed in July at 0.67% and is up 69% in the last 30 days, still down 42% over 90. The recent lift looks like distribution rather than campaigns, with Slack listing Lovable among ten agent partners.
Posts to understand this · as of Sep 16
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit held between 1.1 and 1.3 percent share from February through May, then fell to 0.74 in June. July and August took it back to 0.895, still under the spring band. September is only 20 days in, and the last 30 days are down 12.4 percent.
Posts to understand this
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
The steepest decline on the board, from 3.68% in February to about half a point, down every month in between. The posts trace the arc. An early complaint that OpenClaw talk sat miles ahead of what customers asked for, a home rack built for it in April, and by August it is the thing Grok Bot gets compared to. L30 is down 19.8%.
Posts to understand this
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
A plateau, and that is the point. Codex has held near 3% every month since May, L30 flat at minus 6% and L90 up 13%. It stopped being news and became the assumption. Aurelien Aubert shows where the argument moved: every SaaS company either becomes a harness or gets used by one.
Posts to understand this · as of Sep 18
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Attention peaked in spring, when people were wiring Hermes into live business data to run GTM agents. Nous Research shipped bot mode in August and the curve kept falling: down 46.6% over 30 days and 56.4% over 90. Hermes now turns up mostly as a reference point inside other people's prompting advice.
Posts to understand this · as of Sep 18
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce share sat near 4 percent from March through August, below the 5.6 percent it ran in February. The last 30 days is up 38 percent, and the first 16 days of September are pacing at 5.3 percent, an incomplete month. The lift starts before Dreamforce, then partner posts cluster as the event opens.
Posts to understand this · as of Sep 16
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
HubSpot has faded from 6% in May to around 3.5% and is flat over the last 30 days, down 29% on the quarter. The mentions it does get are corporate rather than cultural: the Warmly acquisition in June, Revenue Hub pulling quotes, contracts and billing into one place, and stack histories that file HubSpot under the foundation era.
Posts to understand this · as of Sep 16
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Gong has been sliding most of the year, from 1.89 percent in April to 1.27 now, with L90 down 15.1 percent and the last 30 days roughly flat. What holds the floor is other people using Gong: Benjamin Douablin citing its 326,000-call talk-ratio stat, Armand Farrokh testing its inbound speed. The half-billion ARR post did the rest.
Posts to understand this · as of Sep 19
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
A flat band all year between 0.90 and 1.31, with both the 30 and 90 day moves inside the noise. The plateau is the point: Vercel mostly appears inside other companies' news. A launch partner in Slack Code next to Anthropic and OpenAI, the host Ivan Zhao spoke with at Vercel Ship, and the bench Cognition hired its VP of Engineering from.
Posts to understand this · as of Sep 16
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Cowork has fallen every month since March, from 3.2% to 0.7% in August, down 57% over the quarter and still down 39% in the last 30 days. No event caused it. Cowork now shows up inside other people's arguments, as one item in a Google-wins prediction or a setup step for the Zapier MCP, rather than as the subject.
Posts to understand this · as of Sep 16
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly peaked at 2.1 percent in June, then halved in July and has not recovered: down 41 percent over 90 days, up 26 over the last 30. The brand travels through other people's stack posts, not its own. Dima Bilous listing roughly 200 mailboxes drew over a thousand engagements; Instantly's own AI Lead Finder launch drew 184.
Posts to understand this · as of Sep 17
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter climbed from near zero in February to an August high, when reports of a Stripe acquisition above seven billion dollars put the routing layer in everyone's feed. Its own traffic data carried the rest. Share is down 45 percent in the last thirty days and still 75 percent above where it sat ninety days ago.
Posts to understand this
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
The line drifts down all year, from 1.16% in February to under 0.8% since June, off 19.5% over 90 days and 12.9% over 30. No crash, just fewer reasons to bring it up. What talk remains is about leaving it or policing it, not building on it.
Posts to understand this · as of Sep 13
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Semrush peaked at 1.1% in June, when its Cannes Lions villa put AI search and brand visibility in front of the big SEO names. Attention halved by August, and the L30 move is down 27%. The September note on Google's goto redirects, telling marketers rank tracking was not affected, is defense rather than a new draw.
Posts to understand this · as of Sep 17
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva's share peaked in April at 1.40 percent, then slid through summer, with August flat against July. September is only 20 days in, so use the rolling read: down 22 percent over 30 days and 49 percent over 90. What is still posted is Canva's own feature push and an outside read on its valuation cut.
Posts to understand this
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Share more than tripled in May, to 1.097 percent, and held near that in June. None of the evidence here is from May, so the jump itself is unexplained; what the posts show is the argument that followed, over whether AI search needs its own tooling. Share then fell by half into August, and the last 30 days are up 28 percent.
Posts to understand this
 inReplacement pitchSays ChatGPT prompts replaced his Semrush and Ahrefs subscriptions in fourteen days.A
 inCompany replyAhrefs explains a data inconsistency from Google routing results through /goto redirects.ST
 inJune plateauCalls out Google's VP of Search Ads for saying AI search needs nothing special.
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier's share held near 1.3% through March, dipped in April, rebounded to 1.29% in May, then dropped to about 0.7% across June and July. The mentions carrying it come from operators naming Zapier as the glue they route around. August lifted slightly and the last 30 days are up 26.5%, with Zapier's own Build Off running into September 21.
Posts to understand this · as of Sep 16
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
The line fell from 1.56% in March to 0.56% in August, down 37% over 90 days. Most mentions come from challengers positioning against them, from Ava 2.0's replacement pitch to Adam Robinson's $27 unlimited contact data. ZoomInfo's own Slack MCP listing is the exception. Up 41% in the last 30 days off a low base.
Posts to understand this · as of Sep 17
Profound measures and improves how brands appear in AI answers.
Profound's recent lift traces to one event: the $180M Series D from Sequoia and Kleiner Perkins at a $1.8B valuation, amplified by partners like Rahul Jain. The last 30 days are up 53.7 percent. Not all the attention has been friendly. Brian Stempeck spent July arguing Profound's sampling carries a margin of error that makes GEO data unreliable.
Posts to understand this · as of Sep 19
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
Share sits well below its spring level, down about a quarter over 90 days, with the last 30 roughly flat. The posts explain why the name keeps surfacing: rivals use it as the benchmark. Bland claimed Speech v3 outranks it, Deepgram published a buyer's own test against it, and SaaStr ran the zero to $600M GTM playbook.
Posts to understand this · as of Sep 18
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio peaked at 1.032% in May around the GTM Atlas launch and has come down since, off 19% over 30 days and 34% over 90. What still posts is other people's commentary rather than Attio's own news: a customer crediting the flexible data model, and Anthony Pierri picking apart the tagline he switched for.
Posts to understand this · as of Sep 17
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo went from no share in February to 0.94% in May, then flattened into a band it has held all summer. The pattern is not launches. Apollo turns up inside other people's stacks: a stripped-back outbound rebuild, a line item in Replit's growth kit, and its own post about a soccer sponsorship. L30 is down 19.9%.
Posts to understand this
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify's share climbed from 0.14% in March to about 0.93% in May, held near 0.9% through July, then eased. The last 30 days are down 14.3% to 0.65%. The posts here start June 19, after that rise, so they show what sustained the plateau, not what caused it: Apify named inside Claude Code and MCP stacks.
Posts to understand this · as of Sep 17
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Share swings month to month and is down 40% over 90 days. The attention comes less from the product than from arguments about its edges: Noah Kagan calling it one Siri update from unnecessary, Peter Kazanjy telling founders it fails as a sales meeting recorder. The Apple Watch app is the one thing Granola itself put into the conversation.
Posts to understand this · as of Sep 18
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
Zero in February, then a plateau near 0.68% held for three straight months. The entry point was LinkedIn's ban wave in March. What keeps it there is different work: HeyReach now appears inside other people's stacks, in a Replit SDR's outreach setup and on Dima Bilous's keep list. A plateau like that means furniture, not news.
Posts to understand this · as of Sep 18
RB2B identifies the people and companies visiting a website so sales can follow up.
RB2B climbed from February to a June high, carried by the bootstrapped revenue story and by showing up inside other vendors' stack posts, like Listen Labs routing visitor signals into Unify. That run ended in July and August, and the last 30 days are down 22 percent. Adam Robinson's own posts have moved from the product to founder economics.
Posts to understand this · as of Sep 17
Intercom is a customer messaging platform built around Fin, its AI support agent.
Intercom's share peaked in March, the month Fin shipped its observability suite. June brought a second, smaller lift on Salesforce's agreement to buy Fin, and share then fell hard through July and August. The last 30 days are up 111 percent off that low, with the talk now about the exit rather than the product.
Posts to understand this
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
After an April dip to 0.074%, LangChain has held near 0.4% since June. The flatness is the story: the last 30 days moved 1.6% while the 90-day picture is up 52.1%. What holds it there is evaluation work and ecosystem gravity rather than launches. A test of JEV against LLM judges drew the largest response here, and Tavily bought a booth at Interrupt26.
Posts to understand this
 XEval benchmarkLangChain tests JEV against LLM judges on accuracy, repeatability, latency, costEK
 inPractitioner pickKramer starts a production-agent experiment with LangChain, Dust, Gumloop and VercelT
 inEvent orbitTavily sponsors the Interrupt26 closing reception and demos retrieval in fleet agents
Baseten deploys and runs custom AI models in production.
Baseten was invisible in February and runs near 0.4 percent now, up 67 percent over 90 days. Other companies carry the rise. Kimi.ai named Baseten a day-zero launch partner for K3, and Harvey posted about co-training recursive language model agents with it for M&A diligence. Its own strongest move was giving a book away.
Posts to understand this
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Nooks has no trend, just spikes from single posts. February came off the AI sequencer launch that Florin Tatulea said would shake the legacy sequencing space. August's loudest post was Peter Mollins announcing his exit after two years. The last 30 days are up almost 19 percent, while the company's own G2 award post barely moved.
Posts to understand this
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Share peaked at 0.66% in July, when the Zoom acquisition was the conversation. Florin Tatulea's July 2 post drew the biggest reaction that day, and outside commentary was still running on July 29. Then it stopped. August fell to 0.22%, and the last 30 days are down 56%, with Common Room's own posting the main voice left.
Posts to understand this · as of Sep 17
Exa.ai is a web search API designed for models and AI agents.
Exa went from almost nothing in February to a May peak, right after the $250M round. It has not settled since: June dipped, July hit the high, August fell back. The last 30 days are up 7.1 percent. The talk has widened from the funding headline to how agent search actually gets built and used.
Posts to understand this · as of Sep 17
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly climbed steadily from February to 0.54% in July, helped by its MCP and API launch in June and then by HubSpot buying the company. August dropped to 0.15% and the last 30 days are down another 10%. That is the normal shape after an acquisition: the name gets talked about as an outcome, then stops being talked about as a product.
Posts to understand this · as of Sep 16
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode went from 0.08 percent of the conversation in March to 0.45 percent in August, and the lift came from other people naming it rather than from its own launches. Grok told users to run 4.6 inside it, Supabase scored it beside Claude Code and Codex, Together AI slotted it in as the harness layer. The last 30 days are down 32 percent.
Posts to understand this · as of Sep 15
Gamma turns prompts into presentations, documents, websites and images.
Gamma's share peaked in March at 0.72, slid to 0.29 by July, and has sat in the high 0.3s since. The last 30 days are up 5.4 percent while the last 90 are down 39.5 percent, so the slide has flattened rather than reversed. September is still partial, and the recent posts are smaller and come from three different corners.
Posts to understand this · as of Sep 19
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps hit its high in May at 1.03% share, driven by other people's research posts. It then fell 62% over 90 days to a low base, and the monthly bars have sat near that floor since July, with the last 30 days down another 27%. The recent mentions come from people citing AirOps data.
Posts to understand this · as of Sep 16
1mind provides AI sales agents for websites, demos, live calls and customer success.
A steady fade from the February high, when Nathan Latka's interview about the $30M round and Jacco van der Kooij's twelve-month report on the Jack agent were both circulating. Nothing since has replaced that. Jonathan M K.'s August webinar pipeline post did not move the curve, and L30 is down about 39%.
Posts to understand this · as of Sep 19
Firecrawl turns websites into clean, structured data for models and agents.
From nothing in February to a spiky presence, up 27% over the quarter but off 21% in the last 30 days. Every bump is tactical rather than a launch. Free credits for GitHub stars and follows, a walkthrough pairing Firecrawl with Claude Code to reach sources Clay cannot, and Zenrows running head-to-head benchmarks against it.
Posts to understand this · as of Sep 16
Higgsfield generates video and images for ads and social content.
Higgsfield share bottomed in April at 0.074%, then climbed three straight months to a 0.320% peak in July. The MCP launch landed in the final days of April, and creator posts ran through the summer climb. August cut share roughly in half, and the last 30 days are flat at 0.201%.
Posts to understand this · as of Sep 17
Grok Bot is an always-on agent that learns routines and completes work across existing software.
New to the tracker and up 836% over the last 30 days. SpaceXAI opened the early beta on August 11 and the line starts there. Two things sustained it: users posting what the bot did on its own, like cancelling a service without being asked how, and Stripe giving bots a card to buy with.
Posts to understand this · as of Sep 13
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce did not exist in this data before August. What is carrying it is argument, not announcement: Jason Lemkin saying he has run Salesforce headless with a Claude agent for six months, Janis Zech reading the deal as Salesforce conceding the CRM is not where users should sit, Justin Norris calling it a dopey name and a smart bet.
Posts to understand this · as of Sep 16
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
Astra carried this line. It was near zero through spring, lifted in August when the claim that an internal Astra solved ten open problems in math and quantum spread, and sits far higher in the September partial. Peter Walker has OpenAI taking 31% of OpenRouter dollars, a new peak. Seventeen days observed, so treat the level as early.
Posts to understand this · as of Sep 17
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Fable went from nothing to 3.73% in June on the Fable 5 launch, ran hot in July, then cooled to 1.35% in August. Up 12.2% over 30 days. September's partial bar is high again, with Cursor shipping Fable 5.1 and calling it the most capable model it has benchmarked.
Posts to understand this · as of Sep 13
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
GPT-5 sits near the floor, under 0.1% since May, with the L30 move down 55%. It gets named inside other companies' posts rather than its own: a model list in Replit's design suite, a benchmark it lost to You.com's finance API, and a complaint that its price nearly doubled while cheaper models keep falling.
Posts to understand this · as of Sep 17
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Opus moves in release spikes and little else. April, May and July each clear 1%, with the Opus 5 launch carrying July, then the line falls to 0.31% in August. Down 64.2% over 30 days. Between launches it appears as a line item in someone else's comparison rather than a subject of its own.
Posts to understand this · as of Sep 13
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Grok 4 barely registered until July, when benchmark claims did the work: Grok 4.5 taking the top AutomationBench spot ahead of Claude, then Elon Musk calling it Opus class for browser use. Grok 4.6's CursorBench win held August near that level. The last 30 days are down 53 percent, which says the benchmark cycle was carrying the line, not the product.
Posts to understand this · as of Sep 16
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Sonnet 5 launched in June and share hit 0.72 percent that month, the high for the year. It fell through July and August to 0.12 percent. September is only 20 days in, so the month is not comparable, but the last 30 days are down about 10 percent.
Posts to understand this
Muse Spark is Meta's AI model for running coding and other agents.
Version releases move this one. Muse Spark 1.2 drew developer attention in August when Cline pulled its agent harness prompt, and 1.3 arrived in early September inside Meta's Muse personal agent and third-party products like Genspark. Share is up 30.7% over 30 days and 329% over 90.
Posts to understand this · as of Sep 18
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Gemini Flash has no baseline. It goes quiet, then jumps when a version ships, which is why ninety days reads up 81% and thirty days reads down 17.4%. Every post here belongs to a partner rather than Google: Databricks with day-zero access to 3.8 Flash, Harvey benchmarking 3.6, Factory discounting 3.7.
Posts to understand this
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
Kimi K3 hit #1 on the frontend code arena in mid-July, and that ranking carried the July spike. What followed was building, not benchmarking: Harvey post-trained its Tenet legal model on a K3 base, and Vercel's security eval scored K3 at half the leader for a fifth the cost. Down 73% over the last 30 days, still far above spring.
Posts to understand this
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen rises on use, not launches. Hugging Face's summer report put Qwen ahead for local inference, Andrew Chen runs 27B on a homelab eGPU, and Morgan is testing whether 27B holds up for production code. That practitioner chatter built through August and has cooled since. Down 60% over the last 30 days, still above the spring baseline.
Posts to understand this
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM was a rounding error until June, then jumped to roughly 0.6 percent and has held that level for four months. Nothing spiked; the line stepped up and stayed, 275 percent above where it sat ninety days ago. Distribution did it. GLM 5.2 landed in Notion, led a category on Mercor's apex-swe benchmark, and shows up in Bolt's new lineup.
Posts to understand this
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos moves when Anthropic does. The April high came from the Glasswing preview, a model held back to 40 partners for defensive security work. The September 5.1 release did not repeat that: talk turned to pricing at $10 and $50 per million tokens and to launch partners like Rogo. Down 29% over the last 30 days, down 73% over 90.
Posts to understand this
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney does not carry its own conversation here. It spikes when other people need it as an example: Greg Isenberg's June note that the company is bootstrapped, Gamma's studio crawl built on tuned Midjourney srefs, a reshared sandbox joke in August. No product news appears in the evidence, and the L30 move is down 43%.
Posts to understand this · as of Sep 17
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Devin has held a narrow band all year, between 0.06% and 0.27% a month, with no month that breaks out. The mentions carrying it come from other companies' launches: Windsurf 2.0 built cloud delegation on Devin, Amplitude named it beside Cursor and Warp. Devin travels inside other people's announcements more than its own.
Posts to understand this · as of Sep 17
Runway is an AI platform for generating and editing video and images.
Runway's share is small and mostly borrowed. The last 30 days are up 29.5 percent, but the recent mentions come from other vendors: MiniMax listing Runway among guests at its Japan IP conference, and Pika pricing itself against Runway. Runway's own posts, like the April single-creative ad, carried the earlier moves. L90 is still down 9.3 percent.
Posts to understand this · as of Sep 19
Join 19,257+ GTM leaders and practitioners. Free, unsub anytime.
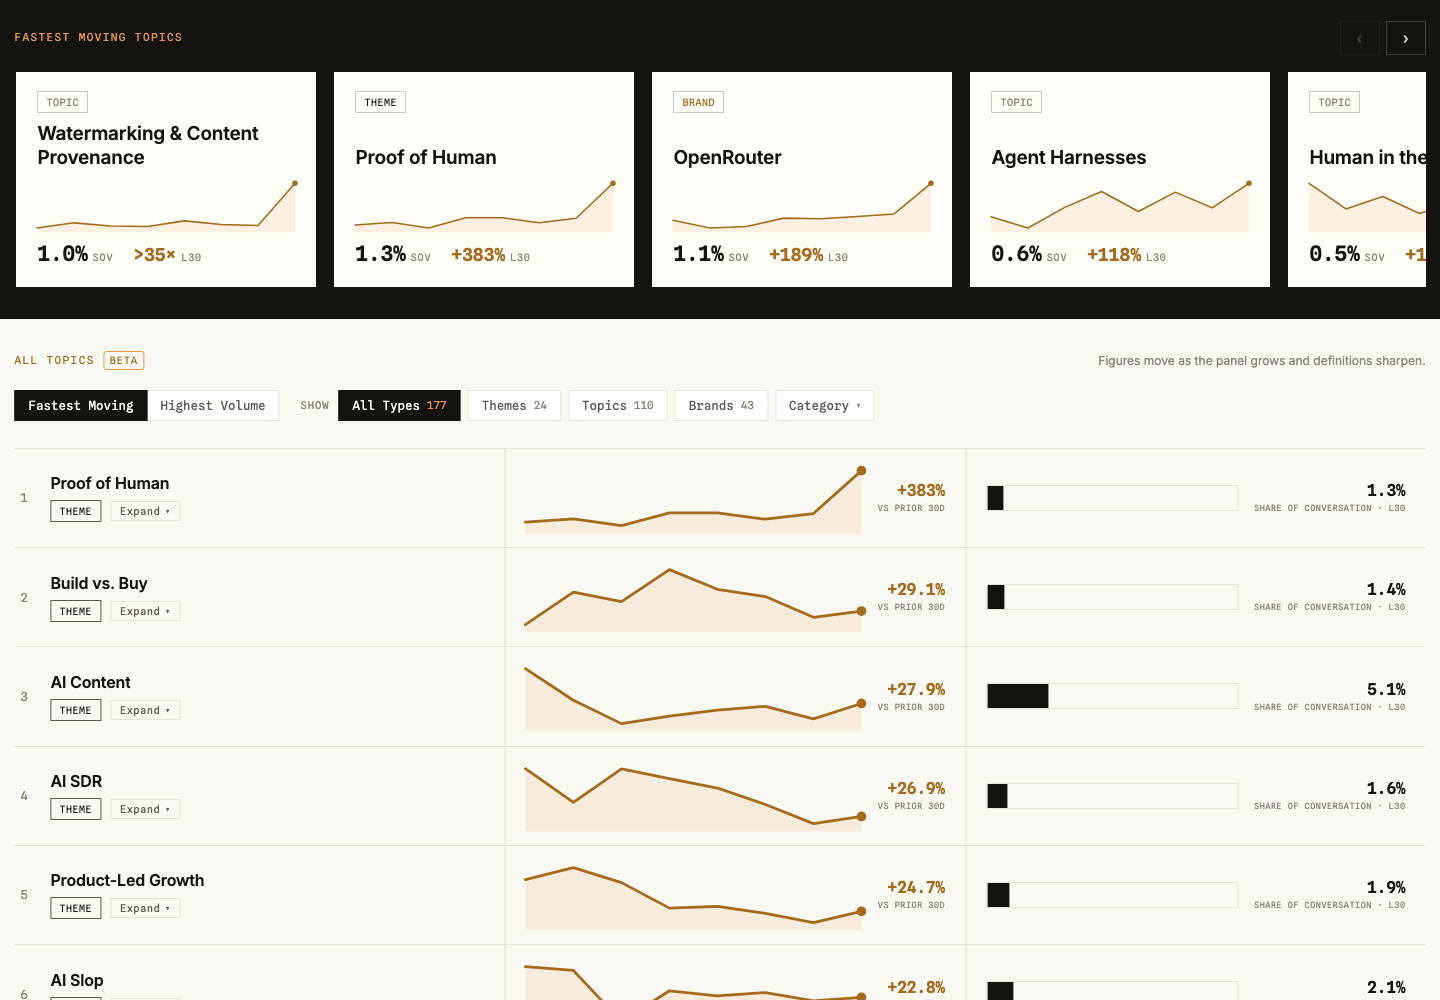
Loading people…
join 19,257+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-09-20.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,257+ gtm leaders, unsub anytime.