What’s moving now
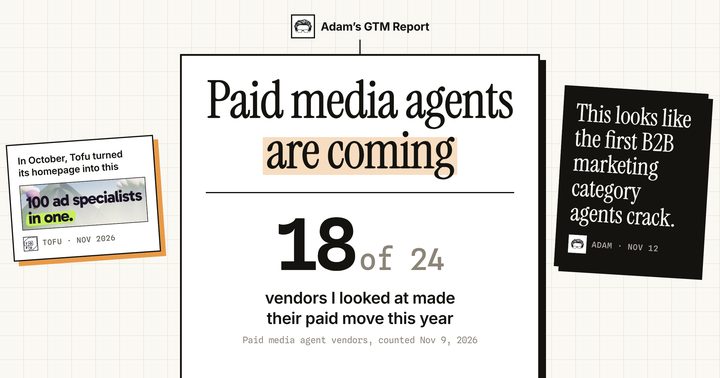 Paid media agents are comingNov 12 · The vendors and builders. Why paid is first. My experiment
 24.8× the usual response · 2,292 engagements
 24.7× the usual response · 1,037 engagements
 13.8× the usual response · 5,787 engagements
 10.0× the usual response · 130 engagements
 7.6× the usual response · 136 engagements
 BraintrustFirst seen Nov 9Featured roleDirector, AI-Driven Marketing
 IruFirst seen Nov 8Featured roleCreative Lead, Brand and Video
 Harmony.ai$120K–180K · 30% below the medianFeatured roleGTM Engineer
 Endor LabsFirst seen Nov 13Featured roleSenior Community Manager
 Gradial$160K–180K · at the medianFeatured roleHead of Product Marketing
 Benchling$208K–312K · at the medianTrending Creator
 Mark JungShares a seven-column growth experiment tracker covering ideas, goals, status, stakeholders, assets, performance and notes, describing Notion as their preferred platform.
 2,048 interactions · 1d agoTrending Creator
 Jan RasmussenOutlines nine GTM roles, their responsibilities and suggested tools, arguing that small teams cover all roles by assigning several to each person.
 843 interactions · 1d agoTrending Creator
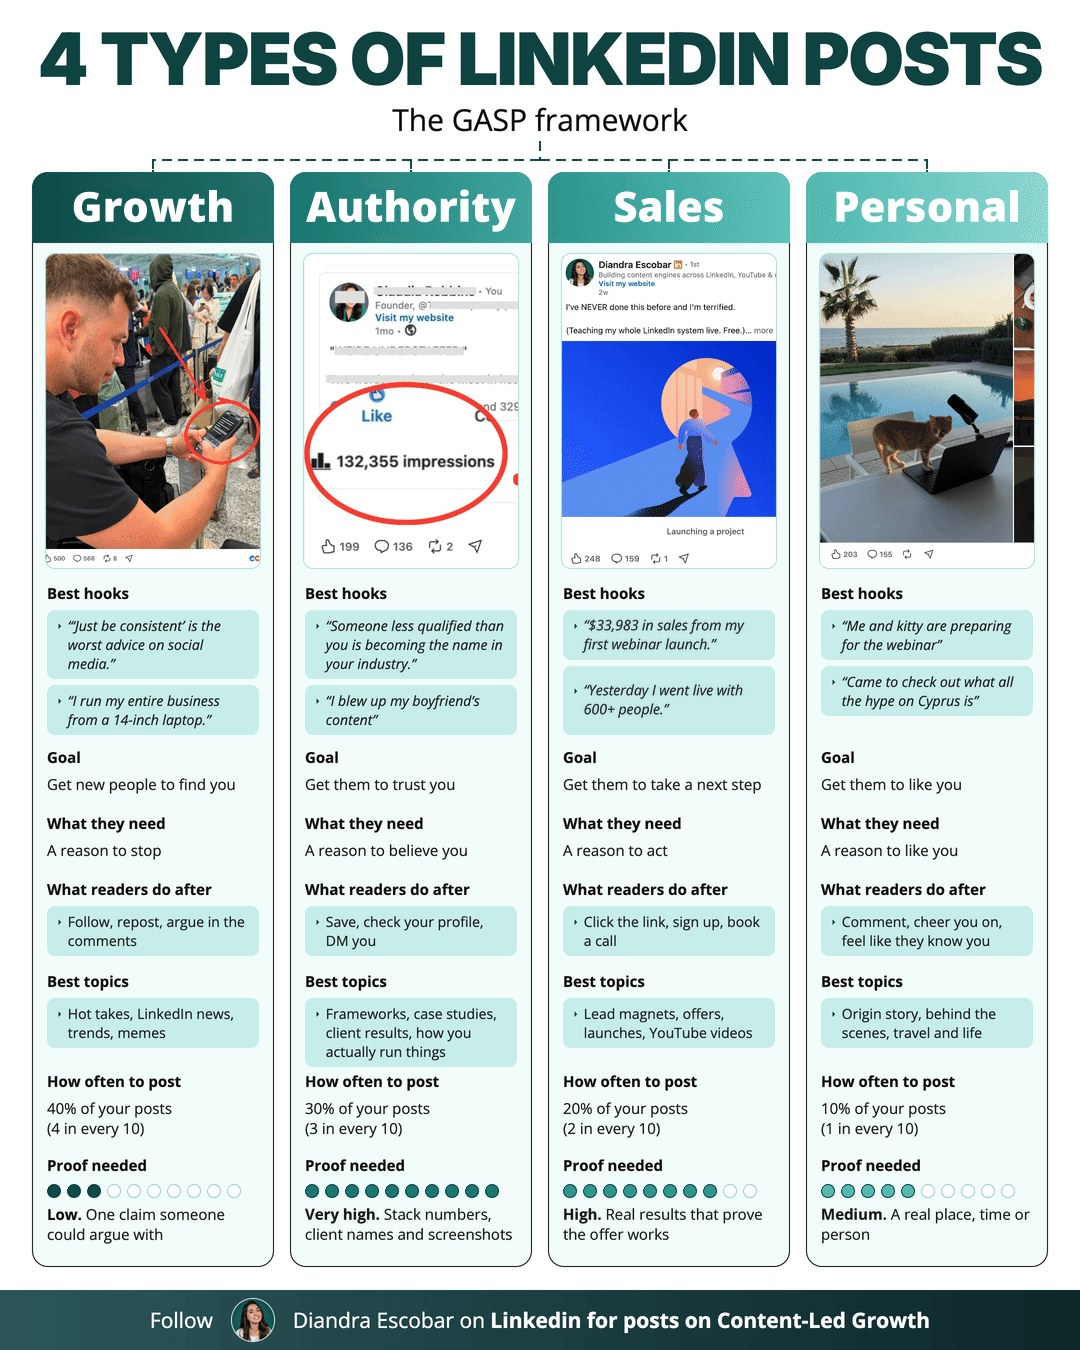
 Diandra EscobarIntroduces GASP, a content framework recommending an initial mix of 40% growth, 30% authority, 20% sales, and 10% personal posts, adjusted to audience response.
 693 interactions · 2d agoTrending Creator
 Dan RosenthalCredits coordinated LinkedIn posting across Workflows.io with booking over 80 monthly meetings and describes quarterly employee bonuses supporting broader buying committee coverage.
 380 interactions · 1d agoTrending CreatorDiandra EscobarReports that LinkedIn engineers described AI matching between reader profiles and unfamiliar creators’ content, then recommends explicit topics and targeting one job title.
 336 interactions · 1d agoTrending Creator
 Chris WalkerArgues that AI, corporate restructuring, valuable contributions requiring fewer hours, and dissatisfaction with toxic workplaces are shifting power toward independent talent.
 306 interactions · 1d agoTrending Creator
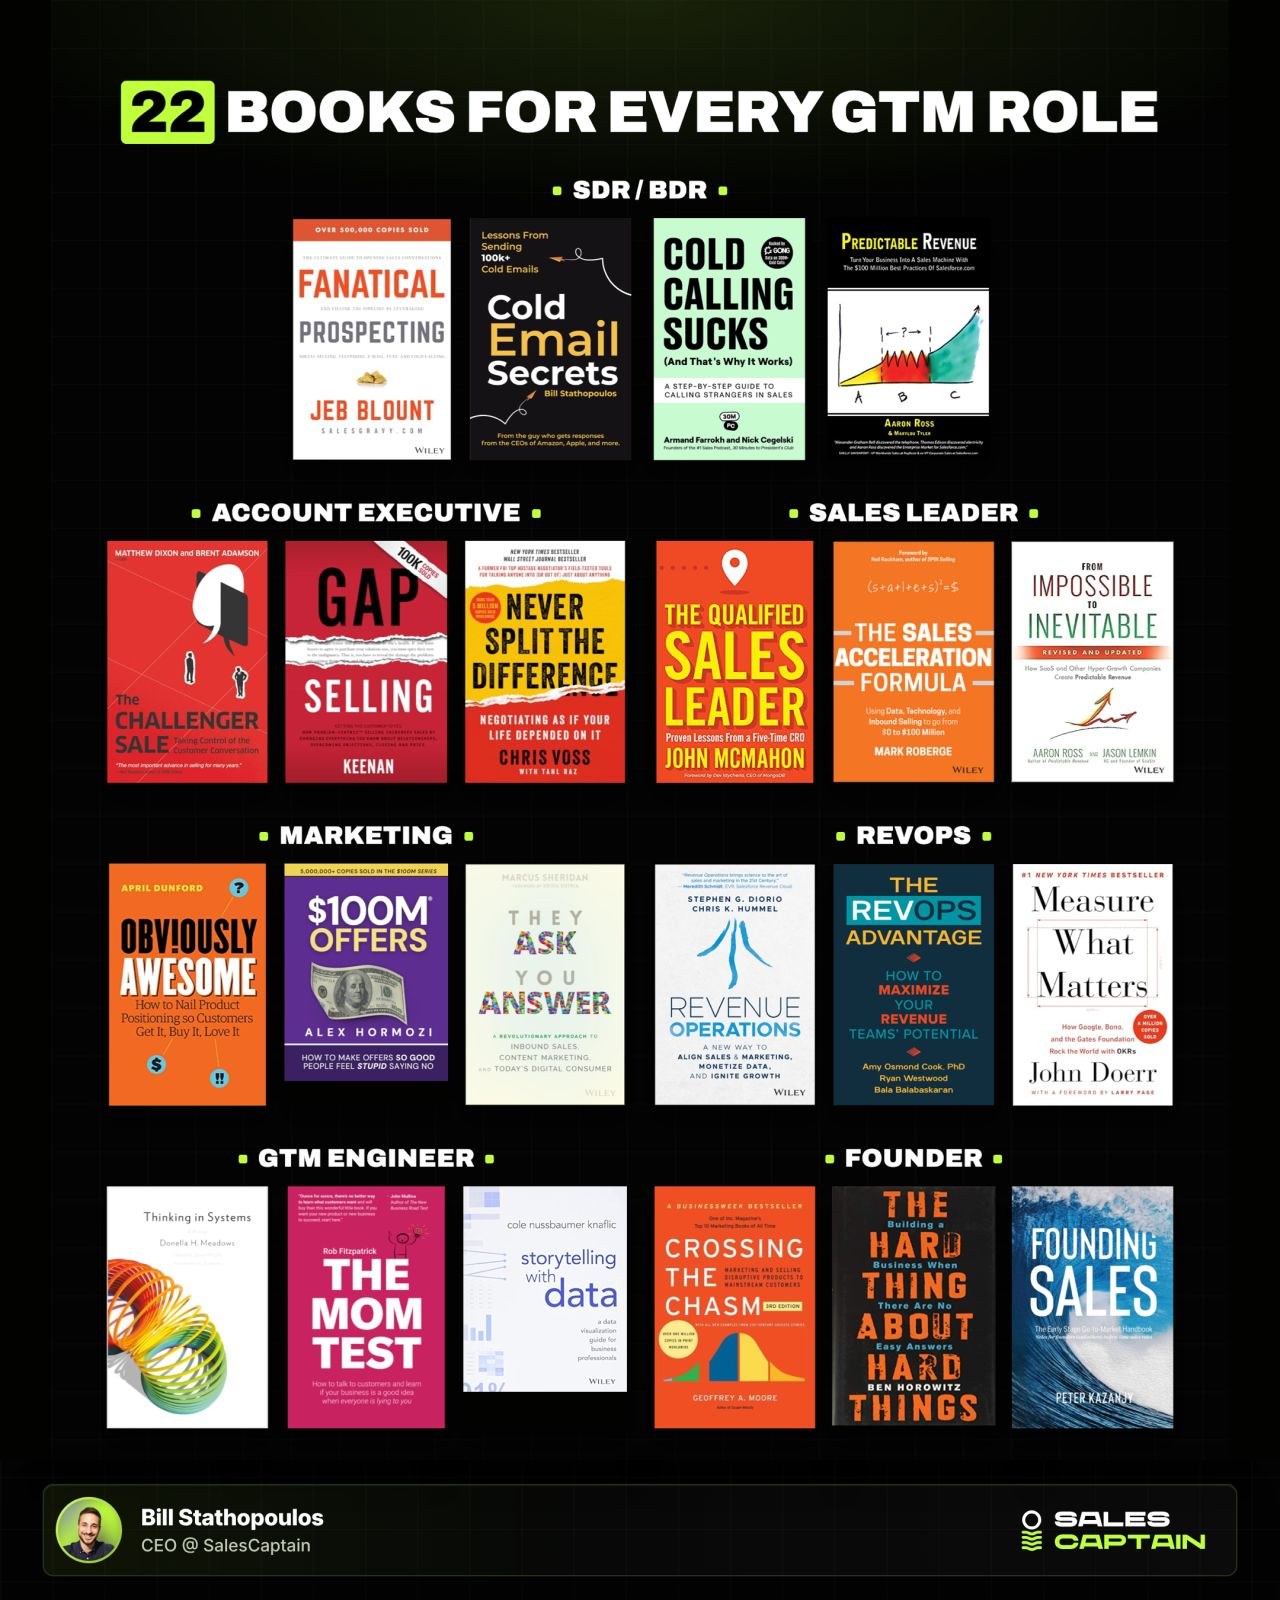
 Bill StathopoulosRecommends 22 books across seven GTM roles, favoring systems thinking, customer conversations and clear data over tool-specific guidance.
 283 interactions · 1d agoTrending topicClaude DuetNEW this month · 0.4% of the conversationTrending topicKimi+176% vs prior 30d · 1.1% of the conversationTrending topicMythos+144% vs prior 30d · 0.3% of the conversationTrending topicClaude Fable+82.1% vs prior 30d · 1.7% of the conversationTrending topicHeyReach+79.9% vs prior 30d · 0.9% of the conversation
 Management OS↑44 places in Traditional SaaS Going Headless
 Qualified↑21 places in AI-Native GTM Challengers
 Sitecore↑38 places in Traditional SaaS Going Headless
 Ploy↑21 places in AI-Native GTM Challengers
 Graphed↑28 places in GTM Developer Tools
Trending Topics
 BrandNEWthis month0.5%shareKimiKBrand+176%vs prior 30d1.1%share
Market Moves
 C605 engagements · 3.0× usualPost ↗1,037 engagements · 24.7× usualPost ↗
 222 engagements · 4.8× usualPost ↗
 leadiq ↗136 engagements · 7.6× usualPost ↗130 engagements · 10.0× usualPost ↗Post ↗
GTM Tech Index

Latest Posts
Nov 12Paid media agents are comingThe vendors and builders. Why paid is first. My experiments. The autonomy question. Nov 5Everything I measured in AI x GTM -- October reportBuild vs. buy, marketing agents are coming, the new inbound, and categories blurring.
 Oct 29We're going to build it ourselvesThe new stack, two paths for GTM, agents vs infra
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
All topics
BetaFigures move as the panel grows and definitions sharpen.
+23.1%vs prior 30d+4.5%vs prior 30d-4.6%vs prior 30d+9.4%vs prior 30d+35.5%vs prior 30d-23.1%vs prior 30d +82.1%vs prior 30d-3.8%vs prior 30d
 -45.6%vs prior 30d+18.1%vs prior 30d
 +176%vs prior 30d+14.4%vs prior 30d-18.7%vs prior 30d-15.6%vs prior 30d+79.9%vs prior 30d-19.5%vs prior 30d-22.7%vs prior 30d-7.2%vs prior 30d+55.2%vs prior 30d+14.1%vs prior 30d+39.1%vs prior 30d+72.9%vs prior 30d+28.0%vs prior 30d
 -48.3%vs prior 30d
 -63.8%vs prior 30d-27.3%vs prior 30d+7.7%vs prior 30d+25.2%vs prior 30d+10.3%vs prior 30d+9.7%vs prior 30d+30.1%vs prior 30dNEWvs prior 30d+29.1%vs prior 30d-14.0%vs prior 30d-14.7%vs prior 30d+5.9%vs prior 30d-32.9%vs prior 30d
 NEWvs prior 30d-2.4%vs prior 30d-53.2%vs prior 30d
 -34.6%vs prior 30d+144%vs prior 30d
 +8.7%vs prior 30d
 +8.7%vs prior 30d
 +17.8%vs prior 30d
 +21.1%vs prior 30d
 +11.3%vs prior 30d
 -27.0%vs prior 30d
 -35.4%vs prior 30d-47.3%vs prior 30d-42.0%vs prior 30d
 +12.1%vs prior 30d-48.8%vs prior 30d
 +5.0%vs prior 30d
 -25.5%vs prior 30d
 -72.6%vs prior 30d
 +3.6%vs prior 30d
 -10.1%vs prior 30d
 -68.1%vs prior 30d
 -24.6%vs prior 30d
 -22.8%vs prior 30d
 -52.8%vs prior 30d
 -37.7%vs prior 30d-52.6%vs prior 30d
 -59.8%vs prior 30d+22.9%vs prior 30d
 -78.9%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
GTM agent building lost conversation share from April through October, with a brief August pause; the last 30 days are down another 11.4%. No single event explains the slide: the posts span Cody Schneider’s setup guide, ColdIQ’s reusable ad skills and Greg Isenberg’s connected agent workflows. Practical examples persist even as the topic takes a smaller share of attention.
Posts to understand this · as of Nov 11
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 76 |
| 3 | Codex | 82 |
| 4 | Clay | 94 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | HubSpot | 90 |
| 7 | Salesforce | 95 |
| 8 | Lovable | 61 |
| 9 | Replit | 56 |
| 10 | Instantly | 66 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO rose from April to a June peak, faded through September, then rebounded in October; the last 30 days are up 10.3%, despite a 15.1% decline over 90 days. April’s agency funding story has given way to October adoption data and November tactics for earning third-party mentions, putting the recent conversation closer to execution.
Posts to understand this · as of Nov 12
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Semrush | 46 |
| 5 | Ahrefs | 50 |
| 6 | Claude Code | 99 |
| 7 | Grok Bot | 76 |
| 8 | AirOps | 41 |
| 9 | Salesforce | 95 |
| 10 | G2 | 58 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click conversation peaked in May, declined through September, and recovered some ground in October; the last 30 days are essentially flat at minus 0.9%. The posts trace a debate from Dave Gerhardt’s warning about AI bypassing downloads to more qualified advice. Amanda Natividad’s October evidence challenges blanket rules against links, while Wil Reynolds stresses accumulated brand authority.
Posts to understand this · as of Nov 12
 inLink evidenceAmanda Natividad cites research where 40% of creators performed better with linksDG
 inBuyer behaviorDave Gerhardt argues AI answers weaken marketing built around content downloadsWR
 inAuthority argumentWil Reynolds argues established brand signals shape inclusion in AI recommendations
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Semrush | 46 |
| 5 | Ahrefs | 50 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 41 |
| 8 | Salesforce | 95 |
| 9 | Grok Bot | 76 |
| 10 | Webflow | 49 |
The people, tools and operating model behind custom go-to-market systems.
GTM Engineering eased from May’s high before settling near 7% in September and October; the last 30 days are down just 1.8%, versus 18.4% over 90 days. Clay’s $115 million Series D and Sculpt agent announcement coincide with that plateau. Alongside Profound’s marketing engineer role, the posts show continued investment in custom GTM systems without renewed growth in conversation share.
Posts to understand this · as of Nov 13
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Instantly | 66 |
| 5 | Salesforce | 95 |
| 6 | HeyReach | 55 |
| 7 | Prospeo | 54 |
| 8 | Codex | 82 |
| 9 | Grok Bot | 76 |
| 10 | Apify | 54 |
How software exposes its data and actions so agents can use it directly.
Headless and agent interfaces lost share through the summer, briefly recovered in September, then dropped in October; the last 30 days are down 18.8%. No single event explains the decline. Cloudflare’s monetization gateway waitlist, Notion’s developer tools, and Databox’s Claude connector show concrete infrastructure work, but those announcements did not sustain the spring conversation share.
Posts to understand this · as of Nov 12
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Clay | 94 |
| 5 | Codex | 82 |
| 6 | Grok Bot | 76 |
| 7 | Instantly | 66 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Exa.ai | 51 |
| 10 | HeyReach | 55 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Open vs. Closed Models climbed to a July high, when Hugging Face amplified NVIDIA's support for open models, then declined through October. October announcements from Mistral and Kimi supplied fresh capability claims, but did not restore the summer's share. The last 30 days are up 5.3%, a modest pickup within a broader 90-day decline.
Posts to understand this · as of Nov 8
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cursor (Anysphere) | 75 |
| 3 | Codex | 82 |
| 4 | OpenRouter | 53 |
| 5 | Replit | 56 |
| 6 | Salesforce | 95 |
| 7 | Baseten | 43 |
| 8 | Canva | 51 |
| 9 | Grok Bot | 76 |
| 10 | ElevenLabs | 57 |
How teams use buyer signals to decide who to target, when and why.
Signal-Based Sales & ABM lost share from May through August, recovered through October and is now nearly flat, up 1.9% over the last 30 days. No single event explains that path. The recurring thread is practical execution: shared-context outbound agents, repeatable plays with Clay and Claude Code, and solutions by stc's use of intent data across key accounts.
Posts to understand this · as of Nov 11
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 95 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 | AI Ark | 49 |
| 8 | 6sense | 46 |
| 9 | Grok Bot | 76 |
| 10 | Apify | 54 |
How teams create, distribute and judge marketing content made with AI.
AI Content held between roughly 4% and 5% of conversation share from April through September, then softened in October; the latest 30 days are nearly flat, up 2.0%. The recurring pattern pairs easier production with objections to what gets published: Runway adds delivery formats, Higgsfield brings creation into ChatGPT, and Peter Walker calls out repetitive AI comments.
Posts to understand this
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 41 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Clay | 94 |
| 5 | ElevenLabs | 57 |
| 6 |  HeyGen | 34 |
| 7 | Runway | 36 |
| 8 | Canva | 51 |
| 9 | Replit | 56 |
| 10 | Salesforce | 95 |
How companies prove AI delivers enough value to move beyond a pilot.
Proving AI ROI held above 7% through July, then lost share each completed month through October; the latest 30 days are down another 16.2%. No single post explains the decline, but the evidence shows concrete approaches to the same unresolved problem: Rippling tracks spend, Glean routes tasks to suitable models, and Cassie Young questions whether experimental revenue will stick.
Posts to understand this
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | Clay | 94 |
| 4 | Grok Bot | 76 |
| 5 | HubSpot | 90 |
| 6 | Replit | 56 |
| 7 | Canva | 51 |
| 8 | Codex | 82 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Intercom | 43 |
How large companies move AI from small pilots into secure, useful production work.
Enterprise AI adoption’s share nearly halved between April and October, and the last 30 days are down 18%. The posts frame a recurring gap between ambition and execution: Steve Nouri questions pilot value, while Lindsay Rothlisberger describes undocumented processes that delay builds. Vanta’s reported $300 million ARR milestone offers a concrete success story within that broader friction.
Posts to understand this · as of Nov 11
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | Clay | 94 |
| 4 | HubSpot | 90 |
| 5 | Codex | 82 |
| 6 | Grok Bot | 76 |
| 7 | Cursor (Anysphere) | 75 |
| 8 |  Monaco | 31 |
| 9 | Nooks | 49 |
| 10 | Rox | 34 |
Agents that do go-to-market work across marketing and sales, rather than the tools people use to build them.
April’s high had launch support from Fin’s sales role and ElevenLabs’ agent templates, before share fell through July and rebuilt modestly through October. Nooks’ November announcement adds $500 million in growth capital, Node, and deal agents to that product cadence. Yet the last 30 days are down just 3.5%: substantial new announcements now sit within a relatively steady conversation.
Posts to understand this · as of Nov 13
Inside Agents for GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 90 |
| 5 | Nooks | 49 |
| 6 | Vercel | 61 |
| 7 | Grok Bot | 76 |
| 8 | Exa.ai | 51 |
| 9 | ZoomInfo | 51 |
| 10 | Codex | 82 |
How AI changes what software companies build, charge for and deliver.
Conversation share peaked at 5.3% in May, fell to 2.8% by September, and edged up in October; the last 30 days are up 12.4%, within a broader decline. Schoenfeld argues vendors must sell agents or tools for building them. Retell points to consumption pricing and customer ownership of agent workflows, while Rox ties deployments to measurable business goals.
Posts to understand this · as of Nov 12
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 51 |
| 6 | Vercel | 61 |
| 7 | Gong | 63 |
| 8 | ZoomInfo | 51 |
| 9 | Codex | 82 |
| 10 | Cursor (Anysphere) | 75 |
How companies keep agents secure, accountable and under control as they take on real work.
Agent governance built steadily from April through July, then lost share each completed month through October; the last 30 days are down another 25.7%. No single event explains the decline. The posts show a shift from Databricks’ broad access policies and tracing toward task-level evals and 11x’s automated call monitoring, with concrete controls still shipping as attention contracts.
Posts to understand this · as of Nov 13
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 95 |
| 3 | Clay | 94 |
| 4 | HubSpot | 90 |
| 5 | Vercel | 61 |
| 6 | Codex | 82 |
| 7 | Grok Bot | 76 |
| 8 | Canva | 51 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Higgsfield | 41 |
How AI changes software pricing, usage costs and gross margins.
After a June high of 4.7%, conversation share fell to 2.0% in October; the last 30 days are essentially flat at +0.4%. The posts trace a shift from OpenAI’s token price cuts to Rippling’s spend controls and Peter Walker’s cache economics. That pattern gives the plateau substance: attention persists around managing actual bills.
Posts to understand this · as of Nov 9
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Clay | 94 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | Exa.ai | 51 |
| 7 | Gong | 63 |
| 8 | Intercom | 43 |
| 9 | OpenRouter | 53 |
| 10 | ZoomInfo | 51 |
How companies build trust and stand out when AI makes content cheap and abundant.
August’s rebound gave way to two months of lower conversation share, with another 7.6% decline over the last 30 days. The recurring thread is human accountability as AI content spreads: Ann Handley challenged authenticity policing, Clay published an AI writing policy, and Zappi tested how surprise helps ads stand out without losing brand recognition.
Posts to understand this · as of Nov 11
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Claude Code | 99 |
| 5 | Grok Bot | 76 |
| 6 | Lovable | 61 |
| 7 | Cursor (Anysphere) | 75 |
| 8 | Apify | 54 |
| 9 | Codex | 82 |
| 10 | Gong | 63 |
Agents that do sales work, from prospecting and outbound to the AI SDR.
April’s high coincided with HockeyStack’s $50 million raise for revenue agents and Fin’s sales-role announcement, followed by a decline through August. September and October recovered modestly, with Clay’s global agent adding a concrete campaign-building release. Share is down 4.2% over the last 30 days, so fresh product news has not restored April’s conversation level.
Posts to understand this · as of Nov 13
Inside Agents for Sales
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | HubSpot | 90 |
| 4 | Claude Code | 99 |
| 5 | Nooks | 49 |
| 6 | Vercel | 61 |
| 7 | Exa.ai | 51 |
| 8 | Grok Bot | 76 |
| 9 | Monaco | 31 |
| 10 | Rox | 34 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
After holding around 2.4–2.5% through summer, conversation share dropped in September and recovered modestly in October; the last 30 days are flat at -0.5%. No single event explains the curve. The recurring thread is credibility through people: Wispr Flow’s founder content and Chris Donnelly’s personal-brand account sit alongside skepticism about AI-mediated authenticity.
Posts to understand this · as of Nov 9
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 95 |
| 5 | Lovable | 61 |
| 6 | Nooks | 49 |
| 7 | Apify | 54 |
| 8 | Grok Bot | 76 |
| 9 | Instantly | 66 |
| 10 | Profound | 52 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR discussion fell sharply from April to July, then settled into a lower, uneven range; the last 30 days are down 3.1%. The posts suggest a reset in expectations: Linda Lian describes failed internal builds, Yuriy Zaremba says automation lacked outbound fundamentals, and Clay introduces an agent with business memory. Recent launches have not restored spring’s share.
Posts to understand this · as of Nov 12
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | HubSpot | 90 |
| 4 | Vercel | 61 |
| 5 | Claude Code | 99 |
| 6 | Exa.ai | 51 |
| 7 | Monaco | 31 |
| 8 | Grok Bot | 76 |
| 9 | Instantly | 66 |
| 10 | Nooks | 49 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context engineering rose through June, then declined each completed month through October; the last 30 days are down 17.1%. The posts suggest a shift from explaining context to putting it inside working systems: Charlie Hills describes agent harnesses, Stevie Case quantifies help content’s contribution to support, and Seth London outlines a move toward agents that act on signals.
Posts to understand this
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 95 |
| 4 | Grok Bot | 76 |
| 5 | HubSpot | 90 |
| 6 | Codex | 82 |
| 7 | Nooks | 49 |
| 8 | Exa.ai | 51 |
| 9 | Rox | 34 |
| 10 | Cursor (Anysphere) | 75 |
Growth driven by people using the product before they talk to sales.
Product-led growth lost share from April to July, then stayed in a narrower range through October; the last 30 days are down 2.2%. No single event explains the curve: Clay’s sales-led expansion, Metronome’s self-serve launch, and 1up’s buyer-controlled sales process show several ways product access supports sales. Those examples sustain discussion without a clear return to spring’s attention.
Posts to understand this · as of Nov 12
 inGrowth strategyClay describes its marketing strategy for combining product-led and sales-led growthSW
 inSelf-serve launchMetronome opens self-serve access and reports fivefold quarterly new revenue growth1
 inBuyer experience1up describes faster buyer access through answer engines and self-service demos
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Clay | 94 |
| 3 | Salesforce | 95 |
| 4 | Claude Code | 99 |
| 5 | Ahrefs | 50 |
| 6 | Gong | 63 |
| 7 | Exa.ai | 51 |
| 8 |  FullEnrich | 45 |
| 9 | Ploy | 31 |
| 10 |  Primer | 33 |
How people and agents share work, hand off tasks and make decisions together.
Multi-Player AI peaked in May, held near 2.2% through late summer, then dropped in October; its share is down 33.3% over the last 30 days. Dust’s shared-team argument, Grok Bot’s early beta and Asana’s customer feedback repeat the same ambition: agents that complete work alongside people. That recurring pitch has not sustained May’s attention.
Posts to understand this · as of Nov 13
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 |  Viktor | 36 |
| 5 | Claude Code | 99 |
| 6 | Vercel | 61 |
| 7 | Grok Bot | 76 |
| 8 | Nooks | 49 |
| 9 | Instantly | 66 |
| 10 | Apify | 54 |
Low-quality AI content and the fight to make automated work worth reading.
AI Slop held near 2% from April through June, then softened unevenly through October; no single event in the posts explains the decline. The recurring complaint shifts from empty content at scale to authenticity policing and repetitive AI comments. The latest 30 days are nearly flat at +1.7%, so November’s first eight days do not establish a rebound.
Posts to understand this · as of Nov 8
 inContent critiqueMarketing diary skewers a CEO’s push to replace content strategy with ClaudeAH
 inAuthenticity backlashAnn Handley criticizes AI detection pressures and tools that disguise generated writingPW
 inComment fatiguePeter Walker calls out repetitive AI comments across several of his posts
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 90 |
| 3 | Grok Bot | 76 |
| 4 | Substack | 51 |
| 5 | Apify | 54 |
| 6 | Clay | 94 |
| 7 | Gamma | 45 |
| 8 | HeyGen | 34 |
| 9 | Salesforce | 95 |
| 10 | Cursor (Anysphere) | 75 |
Agents that do marketing work, from campaigns and content to paid media and answering inbound demand.
Marketing agents recovered from July’s low through October, with share up 41.6% over the last 90 days and just 1.9% over the last 30. The evidence moves from Kieran Flanagan’s proposed agentic org chart to Clay’s $115 million financing and October campaign agent launch. That progression gives the recovery concrete product milestones, while the recent pace is much flatter.
Posts to understand this · as of Nov 12
Inside Agents for Marketing
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | Claude Code | 99 |
| 4 | Vercel | 61 |
| 5 | HubSpot | 90 |
| 6 | ZoomInfo | 51 |
| 7 | Primer | 33 |
| 8 | Apify | 54 |
| 9 | Profound | 52 |
| 10 | Webflow | 49 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal Agents stayed below 0.3% through August, then jumped in September and October as discussion expanded from individual setups like Brian Halligan’s Hal to integrations such as ElevenLabs in Meta’s Muse. The latest 30 days are down 33.7%, despite n8n’s November launch of Nod. The 90-day gain of 417.7% shows how far attention remains above the earlier baseline.
Posts to understand this
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 76 |
| 2 | Claude Code | 99 |
| 3 | Codex | 82 |
| 4 | Salesforce | 95 |
| 5 | HubSpot | 90 |
| 6 | Replit | 56 |
| 7 | Vercel | 61 |
| 8 | Apify | 54 |
| 9 | Clay | 94 |
| 10 | Granola | 54 |
How teams track and control the cost of models, tokens and agent work.
Token costs rose in share through July, when OpenAI announced steep Luna and Terra price cuts, then declined through October; the last 30 days are down 40.5%. Later posts shift from cheaper tokens to exposure: Harvey’s reported margin squeeze and Mutiny’s lost six-figure deal. Those examples keep cost control concrete without explaining the broader decline.
Posts to understand this · as of Nov 7
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 95 |
| 3 | Canva | 51 |
| 4 | OpenRouter | 53 |
| 5 | Higgsfield | 41 |
| 6 | Clay | 94 |
| 7 | Cursor (Anysphere) | 75 |
| 8 | Grok Bot | 76 |
| 9 | Intercom | 43 |
| 10 | Replit | 56 |
The argument that agents and custom software will break the classic SaaS model.
SaaSpocalypse’s share fell from 2.5% in April to below 1% in October, with little movement in August and September; the last 30 days are down 21.5%. The posts repeatedly qualify the death claim: Intercom backs both Fin and its help desk, Salesforce reports seat growth, and Cargo argues agents become software’s primary users. The debate increasingly concerns software’s customers and design.
Posts to understand this · as of Nov 11
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Claude Code | 99 |
| 5 | Apify | 54 |
| 6 | Exa.ai | 51 |
| 7 | Gong | 63 |
| 8 | ZoomInfo | 51 |
| 9 | Vercel | 61 |
| 10 | Codex | 82 |
The choice between building software internally and buying another product.
Build vs. Buy declined from April through July, steadied in August and September, then fell again in October; the last 30 days are down 30.4%. The posts move from broad SaaS replacement arguments to specific choices: a salesperson’s Replit tools and a broken Reflector app with limited support. That pattern grounds the debate without identifying a single cause for its decline.
Posts to understand this · as of Nov 11
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Apify | 54 |
| 5 | Exa.ai | 51 |
| 6 | Vercel | 61 |
| 7 | OpenRouter | 53 |
| 8 | ZoomInfo | 51 |
| 9 | Claude Code | 99 |
| 10 |  Resend | 32 |
Ways to verify whether digital content or online activity came from a person or AI.
Proof of Human’s August spike aligns with Anthropic’s watermarking FAQ and debate over whether AI-content users should welcome disclosure. Share fell back in September and stayed nearly level in October, when Evan Armstrong posted a Pangram-based check of Anthropic’s content. The last 30 days are down 12.5%, consistent with an announcement-led burst followed by occasional scrutiny.
Posts to understand this · as of Nov 8
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HeyGen | 34 |
| 3 | Substack | 51 |
| 4 | Apify | 54 |
| 5 | Exa.ai | 51 |
| 6 | Instantly | 66 |
| 7 | Replit | 56 |
| 8 |  AppsFlyer | 19 |
| 9 | Attio | 51 |
| 10 | Canva | 51 |
AI tools that write, edit, test and operate software alongside a human builder.
Coding agents’ share declined from 20.3% in April to 11.6% in October, with only a brief August lift; the last 30 days are down 7.7%. Vercel’s performance rules and Notion’s workspace-as-code beta show practical development uses, while Cursor’s October notice adds a security incident. The evidence spans tooling and operational risk, rather than one event that explains the sustained decline.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 76 |
| 3 | Codex | 82 |
| 4 | Cursor (Anysphere) | 75 |
| 5 | Clay | 94 |
| 6 | HubSpot | 90 |
| 7 | Lovable | 61 |
| 8 | Salesforce | 95 |
| 9 | Replit | 56 |
| 10 | Instantly | 66 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO’s October rebound has settled into near-flat current momentum, up 1.6% over the last 30 days and down 21% over 90 days. No single post explains the summer decline. The evidence shows a persistent debate over what actually works: Ahrefs’ citation research, Eli Schwartz’s defense of SEO fundamentals, and Ethan Smith’s report of broken ChatGPT attribution.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | HubSpot | 90 |
| 3 | Semrush | 46 |
| 4 | Clay | 94 |
| 5 | Ahrefs | 50 |
| 6 | AirOps | 41 |
| 7 | Claude Code | 99 |
| 8 | Salesforce | 95 |
| 9 | Webflow | 49 |
| 10 | Grok Bot | 76 |
The frontier models and labs that provide the base layer for AI products.
Foundation Models swung between July and September highs and sharp pullbacks, with share now down 7.8% over the last 30 days. The posts show recurring releases and comparisons, rather than one event that explains those swings: Anthropic introduced Glasswing, Arena compared agent delivery and user experience, and Claude announced Fable 5.2 and Mythos 5.2 in early November.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 82 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | Grok Bot | 76 |
| 5 | HubSpot | 90 |
| 6 | Salesforce | 95 |
| 7 | Granola | 54 |
| 8 | Midjourney | 33 |
| 9 | OpenRouter | 53 |
| 10 | ElevenLabs | 57 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP’s share has mostly declined since May, with a brief September pause and a further 21.6% drop over the last 30 days. The posts show concrete integrations across ElevenLabs, Databox and Monarch, but no single event explains the slide. New connectors and product actions keep arriving without restoring the protocol’s earlier share of conversation.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Clay | 94 |
| 5 | Instantly | 66 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | Codex | 82 |
| 8 | Gong | 63 |
| 9 | HeyReach | 55 |
| 10 | Exa.ai | 51 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid Media rose through summer, dipped in September, then jumped in October; its share is up 33.8% over the last 30 days. The evidence spans Anthropic’s growth marketing hire, reusable Claude skills for ad operations, and Perplexity Computer’s Meta ads support. That breadth points to a recurring focus on staffing and automating paid acquisition, rather than one launch alone.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Claude Code | 99 |
| 3 | Clay | 94 |
| 4 | Salesforce | 95 |
| 5 | Instantly | 66 |
| 6 | Primer | 33 |
| 7 | Codex | 82 |
| 8 | Grok Bot | 76 |
| 9 | RB2B | 50 |
| 10 | Apify | 54 |
Email sent to people with no prior relationship to start a sales conversation.
Cold email spiked in May, faded through October and is now up 16.5% over the last 30 days. Jason Bay’s reported reply lift from manual inbox sends gives May a concrete deliverability story; later posts debate broad outreach and durable infrastructure. The recurring question is whether the sending setup can support the volume, with no single event explaining the recent lift.
Posts to understand this · as of Nov 11
 inInbox experimentJason Bay reports replies rose after switching from sequencer to inboxS
 inInfrastructure guidanceSmartlead interviews Zapmail’s CEO about mailbox limits and infrastructure durabilityMS
 XVolume argumentMichael Saruggia advocates repeated market outreach with frequent infrastructure changes
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | Instantly | 66 |
| 4 | HubSpot | 90 |
| 5 | HeyReach | 55 |
| 6 | Salesforce | 95 |
| 7 | Prospeo | 54 |
| 8 | n8n | 58 |
| 9 | Lemlist | 50 |
| 10 | Apify | 54 |
Measuring whether AI answers mention, cite and recommend a brand.
AI Visibility reached 4% in June, slipped through September and recovered in October; the last 30 days are up 20%. The conversation includes a dispute over what visibility is worth: Steve Toth argues for active optimization, while Rand Fishkin's October critique questions business impact outside Google's AI surfaces. Checkthat's earlier launch adds another distinction: tracking mentions does not itself improve them.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | AirOps | 41 |
| 3 | G2 | 58 |
| 4 | Semrush | 46 |
| 5 | Ahrefs | 50 |
| 6 | Clay | 94 |
| 7 | HubSpot | 90 |
| 8 |  SparkToro | 28 |
| 9 | Grok Bot | 76 |
| 10 | Noble | 22 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Prospecting rose into May, declined through September, then recovered in October. Share is up 37.8% over the last 30 days but remains down 11.6% over 90. Nooks and Origami illustrate the earlier push toward automated research and lead generation; Moltsets’ October launch accompanied the recovery with a $27 monthly contact database pitch.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Salesforce | 95 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 | AI Ark | 49 |
| 8 | n8n | 58 |
| 9 | Prospeo | 54 |
| 10 | Nooks | 49 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps fell from nearly 4% of conversation in April to roughly 2.8% by August, then held that level through October; the last 30 days are up just 2.5%. That plateau has a practical theme across the posts: which work should teams build themselves? Sara McNamara questions SaaS replacements, while Janis Zech and Kyle Norton offer task-specific agent and forecasting examples.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 | Gong | 63 |
| 8 | n8n | 58 |
| 9 | Nooks | 49 |
| 10 | ZoomInfo | 51 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer Success lost share from April through July, briefly recovered in August, and now shows a 16.3% lift over the last 30 days despite a weaker 90-day trend. The recurring thread is expansion revenue: Rox automates renewals, Vanta unifies new sales and expansion, and Higgsfield describes a $99 subscriber becoming a $6 million annual customer.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Claude Code | 99 |
| 5 | Gong | 63 |
| 6 | Exa.ai | 51 |
| 7 | Vercel | 61 |
| 8 | Replit | 56 |
| 9 | Canva | 51 |
| 10 | Higgsfield | 41 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
Enterprise AI’s conversation share declined every month from April through October and is down another 21.4% over the last 30 days. No single event explains the slide; the posts consistently address deployment friction, from Mistral’s Workflows preview to Informatica’s trusted data argument and Dust’s partnership with Artefact, which established governance at Bpifrance across a 500-license deployment.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | Clay | 94 |
| 4 | Grok Bot | 76 |
| 5 | HubSpot | 90 |
| 6 | Codex | 82 |
| 7 | Monaco | 31 |
| 8 | Rox | 34 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Intercom | 43 |
Voice and chat software that talks with buyers and customers.
Conversational AI rose steadily from April through August, paused in September, then reached its highest completed-month share in October. That October lift coincided with Mistral’s Voxtral 3, ElevenLabs’ Eleven Realtime, and Cartesia Managed Agents launches: a concentrated push into real-time voice and enterprise deployment. Share remains up 19.5% over 90 days, despite a 5% pullback over the last 30.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | ElevenLabs | 57 |
| 4 | G2 | 58 |
| 5 |  Docket | 33 |
| 6 | Grok Bot | 76 |
| 7 |  11x | 24 |
| 8 | Attio | 51 |
| 9 | Clay | 94 |
| 10 |  Twilio | 43 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand generation’s share declined from April through October, apart from an August bounce, and is down another 4.6% over the last 30 days. The posts suggest pressure on familiar methods rather than one triggering event: Dave Gerhardt questions gated content as buyers turn to AI, ClickUp combines sales and marketing ownership, and Sam Jacobs reports widespread pipeline difficulty.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Clay | 94 |
| 5 | Webflow | 49 |
| 6 |  Optimizely | 34 |
| 7 | Primer | 33 |
| 8 | Docket | 33 |
| 9 | Gong | 63 |
| 10 | Nooks | 49 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
AI video’s share of conversation fell from April to June, rose in August and September, then slipped in October. The last 30 days show a 10.5% rebound, with recent discussion spanning HeyGen’s claimed blind-test lead, Higgsfield’s reported revenue growth, and Decart’s live video quality upgrade.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 41 |
| 2 | Claude Code | 99 |
| 3 | ElevenLabs | 57 |
| 4 | HeyGen | 34 |
| 5 | HubSpot | 90 |
| 6 | Runway | 36 |
| 7 | Canva | 51 |
| 8 | Replit | 56 |
| 9 |  Synthesia | 27 |
| 10 | Clay | 94 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold outbound’s share rose from April to May, then fell through September before a small October rebound; the L30 move is down 12%. October’s posts show a mixed conversation: Douablin recommends warmer, shorter call openers, while Hughes launches Unify’s dialer with prospect context built in. Poyar reports cold outbound failing in a survey of 300 B2B teams, alongside uneven adoption of buying signals.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Salesforce | 95 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 |  BetterContact | 44 |
| 8 | Nooks | 49 |
| 9 | Apify | 54 |
| 10 | n8n | 58 |
The work of connecting marketing activity to pipeline and revenue.
Attribution rebounded in October to near its May high, but the broader curve is steady: share is down 4% over 30 days and up just 0.4% over 90. The recurring question is how to connect marketing with revenue when clicks miss the journey. n8n’s self-reported attribution example and Google’s AI-sharing plans give that durable debate concrete measurement problems.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Clay | 94 |
| 3 | Salesforce | 95 |
| 4 | Gong | 63 |
| 5 | Claude Code | 99 |
| 6 | Docket | 33 |
| 7 | G2 | 58 |
| 8 |  GrowthLoop | 29 |
| 9 | AirOps | 41 |
| 10 | HeyReach | 55 |
People asking AI assistants for answers instead of using a traditional search engine.
AI Search & AI Answers rose through June, faded through September, and edged back in October; the latest 30 days are up 33.8%. The recent discussion centers on how to judge visibility when answers send few clicks: Michael King challenges referral-based measurement, while Searchable’s Black Friday research shows which retailer pages assistants cite. That gives the rebound a concrete measurement and merchandising focus.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | G2 | 58 |
| 2 | Clay | 94 |
| 3 | Profound | 52 |
| 4 | Salesforce | 95 |
| 5 | Semrush | 46 |
| 6 | Ahrefs | 50 |
| 7 | HubSpot | 90 |
| 8 | SparkToro | 28 |
| 9 |  CallRail | 25 |
| 10 | Granola | 54 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Data enrichment fell from May through September, recovered some share in October, and is now nearly flat over the last 30 days at +0.9%. Gong Enrich gives October a concrete launch, while the other posts place enrichment inside qualification and automation workflows. The plateau fits a recurring operational need, though these examples do not explain the earlier decline.
Posts to understand this · as of Nov 12
 XOperator workflowChristian describes qualification before enrichment, provider waterfalls, and monthly data refreshesG
 inProduct launchGong Enrich brings third-party contact and account data directly into GongA
 inIntegration exampleInflection adds n8n integration for workflows that include enrichment and personalized messaging
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Instantly | 66 |
| 5 | HeyReach | 55 |
| 6 | n8n | 58 |
| 7 |  Findymail | 45 |
| 8 | Salesforce | 95 |
| 9 | AI Ark | 49 |
| 10 | Nooks | 49 |
Sales and marketing coordinating around a defined set of target accounts.
ABM’s share held near 2% from April through June, dipped in July, and recovered through October. The last 30 days are down 11.7%, so that recovery has softened. Recent posts focus on coordinating ads, content, and email around target accounts, finding accounts through contact-level intent, and reaching decision-makers before Q1 budgets are set.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Clay | 94 |
| 3 | Salesforce | 95 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 |  Demandbase | 36 |
| 8 |  Vector | 34 |
| 9 | 6sense | 46 |
| 10 | Grok Bot | 76 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability peaked in May, then fluctuated at lower levels through October. Conversation share is up 35.2% over the last 30 days but nearly flat over 90 days, suggesting a rebound rather than sustained growth. October posts highlight the operational work behind email delivery and Resend’s Forge launch, without establishing what caused the recent rise.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 66 |
| 5 | n8n | 58 |
| 6 | Salesforce | 95 |
| 7 | HeyReach | 55 |
| 8 | Smartlead | 46 |
| 9 | Codex | 82 |
| 10 | Prospeo | 54 |
Mapping and winning the committee of people involved in a business purchase.
Buying Groups eased from May's high, then recovered modestly from August through October; the last 30 days are still down 1.3%. No single event explains the curve: the recurring argument is that deals depend on internal consensus and access across the account, illustrated by Clay's executive outreach and Jon Miller's critique of marketing automation built around MQLs.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Clay | 94 |
| 3 | Salesforce | 95 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 |  Influ2 | 28 |
| 8 | Nooks | 49 |
| 9 | 6sense | 46 |
| 10 | Demandbase | 36 |
Programmable tools used to build custom go-to-market systems, agents and automations.
GTM developer tools nearly doubled their share in May, faded through August, then recovered in September and October; the last 30 days are up 16.4%. The posts do not establish a single cause for May’s spike, but they show a consistent appetite for reusable builds. October examples span Jan Rasmussen’s GTM stack and a Grokbot-built visitor-to-outbound workflow with Clay.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Instantly | 66 |
| 5 | Prospeo | 54 |
| 6 | HeyReach | 55 |
| 7 | FullEnrich | 45 |
| 8 | Findymail | 45 |
| 9 | BetterContact | 44 |
| 10 | AI Ark | 49 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
GTM data infrastructure’s share declined every completed month after June’s high, with the last 30 days down 7.1% and the last 90 down 38.3%. No supplied event explains the June spike or subsequent slide. Across Pocus joining Apollo, Brinker’s unified-data proposal, and Refine Labs’ Mobi-backed services, the recurring story puts data foundations inside broader platforms and operational work.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | HubSpot | 90 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 66 |
| 6 | Attio | 51 |
| 7 | GrowthLoop | 29 |
| 8 | HeyReach | 55 |
| 9 | Nooks | 49 |
| 10 | Gong | 63 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search strategy peaked in June, eased through September and recovered in October; share is up 31.1% over the last 30 days. The evidence traces a shift from quick AI-citation wins to scrutiny of what those citations deliver. Kevin Indig’s October analysis gives that renewed discussion substance: organic losses vary by industry, and AI is only part of the explanation.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | Claude Code | 99 |
| 3 | Semrush | 46 |
| 4 |  Similarweb | 33 |
| 5 |  Ranked AI | 32 |
| 6 | Substack | 51 |
| 7 | AirOps | 41 |
| 8 | Grok Bot | 76 |
| 9 | Instantly | 66 |
| 10 | Profound | 52 |
Starting and running a business, including the economics and experience of the founder path.
Entrepreneurship fluctuated around 1% from April through October, but its last 30 days are up 49.9%. The evidence points to a recurring question about founder economics rather than a single catalyst: HubSpot Next launched YouSpot for solo operators, Tally reported $6M ARR with ten people, and Chris Walker challenged the financial rewards of venture funding.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | RB2B | 50 |
| 3 | Clay | 94 |
| 4 | HubSpot | 90 |
| 5 |  MoltSets | 29 |
| 6 | Resend | 32 |
| 7 | Salesforce | 95 |
| 8 | 6sense | 46 |
| 9 | Canva | 51 |
| 10 | Codex | 82 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product marketing’s April high coincided with Profound introducing the marketing engineer role and Google’s Marvin Chow announcing a similar hire. Share then drifted down to nearly level September and October readings, although the last 30 days are up 32.6%. Mark Huber’s positioning exercise supplies a recent practical thread, but the evidence does not establish a single rebound catalyst.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Clay | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 90 |
| 5 | Ploy | 31 |
| 6 | Vercel | 61 |
| 7 | Braze | 39 |
| 8 | Codex | 82 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Granola | 54 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Evals and benchmarks climbed to a July high, settled lower in August and September, then declined in October; the last 30 days are down 43.4%. No supplied event explains the July crest or subsequent retreat. The posts span leaderboard claims, test integrity and Cognition’s October FrontierCode 2.0 launch, which added a concrete debate about engineering judgment without reversing the broader decline.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 95 |
| 3 | Grok Bot | 76 |
| 4 | Clay | 94 |
| 5 | Codex | 82 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | ElevenLabs | 57 |
| 8 | Baseten | 43 |
| 9 | Canva | 51 |
| 10 |  Genspark | 24 |
The training, fine-tuning and modeling work underneath AI products.
Machine learning’s share fell through June, climbed to a September peak, then dropped in October; the last 30 days are down 16.2% despite a 10.9% rise over 90 days. October posts show concrete work underneath products: Anthropic trained Claude to assess misuse, Meta improved large-scale training reliability, and Baseten highlighted voice models fine-tuned from open weights.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 82 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | HubSpot | 90 |
| 5 | beehiiv | 51 |
| 6 | Baseten | 43 |
| 7 | ElevenLabs | 57 |
| 8 |  Together AI | 33 |
| 9 | OpenRouter | 53 |
| 10 | Higgsfield | 41 |
The choice of go-to-market motion and the plan for making it work.
GTM Strategy’s share peaked at 2.95% in May, fell to roughly 1.3% by September, and held there in October; the last 30 days are up 1.9%. October and November posts focus on adapting GTM to agent buyers, larger buying committees, and retention when competing products overlap. The discussion centers on who buys, how teams sell, and what keeps customers.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 95 |
| 5 | Instantly | 66 |
| 6 | Optimizely | 34 |
| 7 | Nooks | 49 |
| 8 | Webflow | 49 |
| 9 | beehiiv | 51 |
| 10 | Findymail | 45 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence has bounced between stronger and quieter months, with a 13% lift over the last 30 days but a 7% decline over 90. Salesforce’s agreement to acquire Cresta gives the latest lift a concrete deal backdrop. Gong’s emphasis on account context and Crayon’s Sparks Refresh show the broader pattern: call intelligence feeds decisions and content updates beyond coaching.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Gong | 63 |
| 3 | HubSpot | 90 |
| 4 | Clay | 94 |
| 5 | Claude Code | 99 |
| 6 | HeyReach | 55 |
| 7 | n8n | 58 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Grok Bot | 76 |
| 10 | Instantly | 66 |
How companies create demand, build trust and reach buyers at other businesses.
B2B marketing lost share from June through October; the last 30 days show only a 2.8% lift. No single event explains the slide: the posts describe a recurring search for distribution through owned audiences, creators and employees. Flanagan’s channel playbook and Sanginés’s people-led marketing argument give that smaller conversation a consistent focus: trust beyond the company account.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Salesforce | 95 |
| 3 | Claude Code | 99 |
| 4 | Clay | 94 |
| 5 | Optimizely | 34 |
| 6 | Webflow | 49 |
| 7 | Primer | 33 |
| 8 | Demandbase | 36 |
| 9 | 6sense | 46 |
| 10 | Ahrefs | 50 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise sales peaked in May, declined through July, rebounded in August, then settled lower in September and October. The last 30 days are down 22.8%, with selected posts focused on long buying cycles and procurement, Clay sellers closing enterprise deals, and Higgsfield moving upmarket from its consumer base.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | Clay | 94 |
| 5 | Exa.ai | 51 |
| 6 | Gong | 63 |
| 7 | Lemlist | 50 |
| 8 | ElevenLabs | 57 |
| 9 | Grok Bot | 76 |
| 10 | Instantly | 66 |
B2B brands paying creators and independent voices to reach trusted audiences.
Creator partnerships jumped in October after September’s dip, and the last 30 days are up another 14.5%. No single October trigger appears in the posts; the broader pattern is investment in programs, dedicated roles and software. Ramp’s creator activation and FullEnrich’s ongoing program provide earlier examples, while November posts describe an influencer marketing hire and Passionfroot’s platform ambitions.
Posts to understand this
 inCreator programsMatano describes Ramp’s Super Bowl activation and FullEnrich’s ongoing influencer programFS
 inDedicated hireSondors hires a head of influencer marketing from his LinkedIn commentsJP
 inPlatform investmentPassionfroot recruits engineers to build software for marketing through trusted voices
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | beehiiv | 51 |
| 4 | AirOps | 41 |
| 5 | Primer | 33 |
| 6 | Viktor | 36 |
| 7 | Lovable | 61 |
| 8 | Claude Code | 99 |
| 9 |  Fibbler | 36 |
| 10 | Granola | 54 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing held near 2% of conversation in May and June, when GrowthX announced GrowthOS, then reached a September low after an uneven summer. The last 30 days are up 9.2%, though the 90-day trend remains down. Recent posts share a clear argument: Sara Stella Lattanzio favors validated ideas over quotas, while Mark Jung connects content to trust before buyers enter the market.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 94 |
| 3 | Grok Bot | 76 |
| 4 | HubSpot | 90 |
| 5 | Semrush | 46 |
| 6 | G2 | 58 |
| 7 | HeyReach | 55 |
| 8 | Instantly | 66 |
| 9 | Salesforce | 95 |
| 10 | Cursor (Anysphere) | 75 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting fell from its May high, with a July interruption, before reaching a lower October level; the last 30 days show a 13% lift despite a 25.1% decline over 90 days. No supplied post explains May’s high or the current lift. The recurring thread pairs ROX and Salesloft’s automation promises with Chris Orlob’s insistence on checking actual buying steps.
Posts to understand this · as of Nov 13
 inAutomation launchROX launches Autopilot with autonomous pipeline, deal forecasting, renewals, and expansionCO
 inDeal inspectionChris Orlob checks legal and procurement steps before forecasting a $40,000 dealS
 inPlatform consolidationSalesloft announces a unified brand and system connecting selling with forecasting
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Claude Code | 99 |
| 5 | Gong | 63 |
| 6 |  Clari | 32 |
| 7 | Intercom | 43 |
| 8 |  Chili Piper | 38 |
| 9 | n8n | 58 |
| 10 | BetterContact | 44 |
How companies sell to other companies and how business buyers make decisions.
B2B Sales recovered in October after September’s dip, but the last 30 days show only a 2.2% gain and the 90-day trend remains negative. No single launch explains that modest recovery. The recurring argument is buyer understanding: research before outreach, empathy before a pitch, and content that earns a place on the buyer’s initial vendor list.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | G2 | 58 |
| 2 | Salesforce | 95 |
| 3 | 6sense | 46 |
| 4 | Clay | 94 |
| 5 | Claude Code | 99 |
| 6 | HubSpot | 90 |
| 7 | Gong | 63 |
| 8 | Grok Bot | 76 |
| 9 |  TrustRadius | 25 |
| 10 | Webflow | 49 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Forward deployed engineering declined from May through September, recovered in October and is up 63.4% over the last 30 days. The recent posts give that recovery a concrete focus: StackAI pairs its platform with custom integration work, while Lenny Rachitsky points to growing demand for FDE roles. September’s Palantir veteran critique also shows debate over what qualifies as the work.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | ElevenLabs | 57 |
| 4 | Cursor (Anysphere) | 75 |
| 5 | Exa.ai | 51 |
| 6 | HubSpot | 90 |
| 7 |  PandaDoc | 33 |
| 8 | Clay | 94 |
| 9 | Codex | 82 |
| 10 | Granola | 54 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales leadership’s share dropped sharply in June, paused in July and declined through October; the last 30 days are down 19.9%. No single event explains the erosion, but the posts show competing approaches to staffing: Replit wants leaders who execute, Collin Cadmus advocates longer rep tenure, and a November SaaStr post introduces a Vercel discussion about going from ten SDRs to one.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Vercel | 61 |
| 5 | Gong | 63 |
| 6 | Attio | 51 |
| 7 | BetterContact | 44 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Grok Bot | 76 |
| 10 | PandaDoc | 33 |
The debate over AI risk, alignment, regulation and responsible development.
AI safety jumped in September alongside Mercor’s $5 million safety fund commitment and Microsoft’s amplification of Satya Nadella’s principle for superintelligence. Share fell in October, and the last 30 days are down 46.7%, though the 90-day comparison remains positive. Gartner’s November observability post keeps the discussion grounded in costs and governance without evidence of another September-sized catalyst.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 76 |
| 3 | Granola | 54 |
| 4 | Codex | 82 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | Midjourney | 33 |
| 7 | Salesforce | 95 |
| 8 | beehiiv | 51 |
| 9 | ElevenLabs | 57 |
| 10 | HubSpot | 90 |
The durable knowledge and memory an agent can use across tasks and sessions.
Agent memory reached its highest share in June, then declined through October; the last 30 days are down 16.7%. No single event explains the retreat, and ZoomInfo’s October Workbounce acquisition did not coincide with a monthly rebound. The posts trace a practical pattern across personal knowledge vaults, locally stored meeting records, and account context drawn from internal tools.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | Clay | 94 |
| 4 | Grok Bot | 76 |
| 5 | Nooks | 49 |
| 6 | Codex | 82 |
| 7 | Exa.ai | 51 |
| 8 | Rox | 34 |
| 9 |  Sumble | 35 |
| 10 |  Attention | 27 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
CLI conversation reached its highest share in July, eased through October, and is now up 32.8% over the last 30 days. The posts show a recurring pattern rather than one launch: operators move real work into terminals, from $200,000 a month in ad spend to eight campaigns built through Clay’s CLI without opening Clay.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 94 |
| 3 | HubSpot | 90 |
| 4 | Instantly | 66 |
| 5 | Salesforce | 95 |
| 6 | Exa.ai | 51 |
| 7 | Grok Bot | 76 |
| 8 | HeyReach | 55 |
| 9 | Apify | 54 |
| 10 | n8n | 58 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement held near its spring levels through July, dropped in August and September, then recovered partly in October; the last 30 days are down 9.5%. No single launch explains the curve. Across the posts, the consistent argument is against static playbooks and process busywork, with business acumen, deal progress, and better coaching offered as the useful work.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 94 |
| 3 | HubSpot | 90 |
| 4 | Gong | 63 |
| 5 |  Highspot | 30 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | Salesforce | 95 |
| 8 |  Seismic | 29 |
| 9 | BetterContact | 44 |
| 10 | Monaco | 31 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Partner marketing moved to a higher level in August and held it through October; share is up 17.6% over the last 30 days and 47.9% over 90. The supporting pattern is repeated partner programs across different markets: OpenAI’s cyber partners, Lovable’s client builders, and Sierra’s technology, marketplace, and service ecosystem.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Gong | 63 |
| 5 | Lovable | 61 |
| 6 | HeyReach | 55 |
| 7 | Instantly | 66 |
| 8 | BetterContact | 44 |
| 9 | Claude Code | 99 |
| 10 | Findymail | 45 |
Scoring leads and accounts to decide who deserves attention first.
Lead scoring declined from its May high through September before an October recovery; share is up 27.1% over the last 30 days but remains down over 90 days. No single launch explains the curve. The recurring thread is execution: persona-specific qualification, AI-assisted prioritization, and ABM systems that get intent signals into the CRM before reps miss the moment.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 94 |
| 3 | HubSpot | 90 |
| 4 | Salesforce | 95 |
| 5 | Instantly | 66 |
| 6 | Codex | 82 |
| 7 | Apify | 54 |
| 8 | Exa.ai | 51 |
| 9 | 6sense | 46 |
| 10 | AI Ark | 49 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent skills declined from May through October, but the last 30 days show a 9.9% lift. The evidence shifts from Vercel’s January sharing ecosystem to November examples of specific work: Ira Bodnar’s 48 marketing skills and Alex Fine’s Claude Code outbound setup. These give the recent lift a practical theme, though they do not explain the earlier decline.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 94 |
| 3 | HubSpot | 90 |
| 4 | Codex | 82 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | HeyReach | 55 |
| 7 | Instantly | 66 |
| 8 | n8n | 58 |
| 9 | Apify | 54 |
| 10 | Grok Bot | 76 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth marketing fell after May, recovered some ground in September, and is now down 9.5% over the last 30 days. No single event explains the curve; the recurring debate is how much channel work becomes GTM engineering. Clay Ads supplies an automation example, while Anthropic’s October hiring post keeps performance, lifecycle and SEO in the remit.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Optimizely | 34 |
| 3 | Webflow | 49 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 90 |
| 6 | Grok Bot | 76 |
| 7 | Primer | 33 |
| 8 | Ahrefs | 50 |
| 9 | Codex | 82 |
| 10 | Cursor (Anysphere) | 75 |
The software stack marketers use to plan, run, measure and improve their work.
Martech’s share declined from May through October apart from an August bounce; a 16.2% lift over the last 30 days still leaves it down 13.9% over 90. No single event explains that path. The posts trace a recurring architecture debate, from Scott Brinker’s unified data foundation and Joe Chernov’s agent-sprawl concern to May Habib’s recent call for enterprise watermarking policies.
Posts to understand this
 inArchitecture proposalScott Brinker’s Databricks report explores martech built on unified dataJC
 inSprawl critiqueJoe Chernov compares proliferating marketing agents to streaming subscription bloatMH
 inGovernance argumentMay Habib argues watermarking policies belong in marketing technology procurement
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Salesforce | 95 |
| 3 | Braze | 39 |
| 4 | Clay | 94 |
| 5 | G2 | 58 |
| 6 | GrowthLoop | 29 |
| 7 | Influ2 | 28 |
| 8 | ZoomInfo | 51 |
| 9 |  Hightouch | 32 |
| 10 | Lovable | 61 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting climbed through June, then lost share every month through October; the last 30 days show only a 3.1% lift. The posts suggest a shift toward copy as one part of a larger workflow: Claude Code builds campaigns, Corey Haines’s June release tackles offer design, and Nolan Ong puts audience judgment alongside lists and tools.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 94 |
| 3 | HubSpot | 90 |
| 4 | n8n | 58 |
| 5 | HeyReach | 55 |
| 6 | Instantly | 66 |
| 7 | BetterContact | 44 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | FullEnrich | 45 |
| 10 | G2 | 58 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Conversation held near 1% from April through August, fell in September, then partially recovered in October; the last 30 days are down 9.5%. The recurring case is personal distribution with measurable business results, exemplified by Clay’s reported 4,756 livestream registrations. October posts extend that discussion from Wispr Flow’s founder content to the limits of relying on one person.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Clay | 94 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 66 |
| 5 | RB2B | 50 |
| 6 | HeyReach | 55 |
| 7 | Nooks | 49 |
| 8 | Apify | 54 |
| 9 | Profound | 52 |
| 10 | AirOps | 41 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
Conversation share peaked in May, eased through summer, and recovered modestly in October, with the last 30 days up 16.1%. Recent posts discuss usage pricing in practice: Databricks’ pricing lessons, Retell’s pitch for transparent consumption pricing, and Tavily’s pay-as-you-go path from developer trials to production.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Clay | 94 |
| 5 | Exa.ai | 51 |
| 6 | Gong | 63 |
| 7 | ZoomInfo | 51 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Vercel | 61 |
| 10 | Codex | 82 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Sales development lost share from May through September, then recovered in October; the last 30 days are up 37.7%. The posts trace a shift in the conversation toward equipping reps: Notion asked applicants to build useful agents, while October’s Clay and Notion discussion focused on signals, automation and pipeline per rep. No single event explains the longer decline.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Salesforce | 95 |
| 3 | Clay | 94 |
| 4 |  Outreach | 43 |
| 5 | Claude Code | 99 |
| 6 | Exa.ai | 51 |
| 7 | Gong | 63 |
| 8 | Influ2 | 28 |
| 9 | Monaco | 31 |
| 10 | Vercel | 61 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Revenue agents declined every month from April through October, but the last 30 days show a modest 7.2% lift against a 35.9% decline over 90 days. The posts document a reset in the sales pitch: AMI’s launch acknowledges weak outbound fundamentals, while Nooks emphasizes agents alongside reps and reports customer pipeline and meeting gains.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Nooks | 49 |
| 3 | Salesforce | 95 |
| 4 | Exa.ai | 51 |
| 5 | Rox | 34 |
| 6 | Claude Code | 99 |
| 7 | HubSpot | 90 |
| 8 | Vercel | 61 |
| 9 | Monaco | 31 |
| 10 | Sumble | 35 |
AI agents that create, launch, buy and optimize advertising.
AI-driven advertising rose steadily from April through August, paused in September, then reached a higher share in October; the last 30 days are up 3.5%. The posts trace a practical progression: AirOps support for self-serve ChatGPT ads, agents producing ad variants, and Roadway demonstrations of campaign setup and optimization. Repeated execution examples fit the sustained rise better than one isolated announcement.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | AirOps | 41 |
| 3 | Claude Code | 99 |
| 4 |  Criteo | 21 |
| 5 | Similarweb | 33 |
| 6 | Zapier | 52 |
| 7 | Braze | 39 |
| 8 | Canva | 51 |
| 9 | Codex | 82 |
| 10 | Cursor (Anysphere) | 75 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing operations lost roughly half its share between April and October despite August and October rebounds, and the last 30 days are down 5.4%. The evidence offers discrete announcements rather than one explanation for the decline: Conversion launched agents in May, and Refine Labs acquired Mobi Solutions in October. Sam Jacobs’s November argument questions whether marketing should retain separate operations ownership.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Claude Code | 99 |
| 4 | Clay | 94 |
| 5 | GrowthLoop | 29 |
| 6 | ZoomInfo | 51 |
| 7 | Vercel | 61 |
| 8 | Codex | 82 |
| 9 |  Conversion | 29 |
| 10 |  Customer.io | 37 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
AI-pilled companies lost share from April through October despite a brief summer stabilization; a 9.6% lift over the last 30 days sits within that longer decline. No single launch explains the curve. The recurring discussion tests AI ambition against operating realities: Yamini Rangan asks for growth outcomes, Stevie Case describes traditional GTM hiring, and Kyle Lacy questions team development.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Cursor (Anysphere) | 75 |
| 3 | HubSpot | 90 |
| 4 | Claude Code | 99 |
| 5 | Codex | 82 |
| 6 | ElevenLabs | 57 |
| 7 | Salesforce | 95 |
| 8 | Instantly | 66 |
| 9 |  Lorikeet | 21 |
| 10 | Nooks | 49 |
How marketing teams use AI, where it helps and how it changes the job.
AI in Marketing settled into a recurring band after April’s high, with no single launch behind the pattern. Google’s marketing engineer hire, Andy Mowat’s move to Inflection, and criticism of unchanged marketing processes keep the discussion focused on roles and workflows. Share is down 27.2% over the last 30 days, despite the higher early November reading.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 76 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Clay | 94 |
| 5 | Ahrefs | 50 |
| 6 | Braze | 39 |
| 7 | Canva | 51 |
| 8 | Chili Piper | 38 |
| 9 | Claude Code | 99 |
| 10 | Codex | 82 |
AI agents that discover, compare and buy products on a person's behalf.
Agents as Buyers rose through September and October as checkout partnerships gave the conversation concrete products: Shopify’s Shop Pay integration with Muse, then Claude Duet’s integration with Link’s agent wallet. Link also reported 38-fold monthly growth in agentic transactions. The last 30 days are up 3.5%, a slower continuation alongside discussion of marketing to machine shoppers.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 76 |
| 2 | Salesforce | 95 |
| 3 | Clay | 94 |
| 4 | Profound | 52 |
| 5 | Semrush | 46 |
| 6 | ZoomInfo | 51 |
| 7 | 1mind | 36 |
| 8 | Ahrefs | 50 |
| 9 | Attio | 51 |
| 10 | Claude Code | 99 |
The point where a product solves a real need for a market that will buy it.
Product-market fit lost share from April through July, settled into a narrow August–October range, and is down 21.7% over the last 30 days. No single event explains the decline; the recurring debate is what counts as proof, from Lovable’s need to repeatedly earn fit to Rahul Jain’s paying customers and Andrew Chen’s challenge to software assumptions.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Grok Bot | 76 |
| 3 | HubSpot | 90 |
| 4 | Viktor | 36 |
| 5 | Attio | 51 |
| 6 | Clay | 94 |
| 7 | Granola | 54 |
| 8 | Lemlist | 50 |
| 9 | Primer | 33 |
| 10 | Profound | 52 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales Ops declined from its May high to September, then recovered modestly in October; the last 30 days are up 13.6%. Compensation is the recurring thread, rather than a single launch or deal: Douablin challenges meeting-based SDR pay, Walsh describes seven-figure earnings at private companies, and Cadmus questions recruiting promises. The recent lift sits within a broader decline, with 90-day share down 28.6%.
Posts to understand this
 inRecruiting accountabilityCadmus challenges sales job promises against quota attainment and employee tenureBD
 inIncentive designDouablin argues SDR commissions should reward closed revenue over booked meetingsRW
 inCompensation shiftWalsh reports more private tech companies offering seven-figure sales earning potential
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Clay | 94 |
| 3 | Claude Code | 99 |
| 4 | Codex | 82 |
| 5 | Exa.ai | 51 |
| 6 | Gong | 63 |
| 7 | Grok Bot | 76 |
| 8 | Nooks | 49 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Devin | 37 |
Websites and docs structured so AI crawlers and agents can read and use them.
Conversation share faded through September, recovered in October, and is up 45.3% over the last 30 days. The evidence points to a recurring argument over what makes content usable by AI: Webflow reported conversion gains, Google’s guidance drew pushback, and Tim Soulo documented growing searches for agent optimization tactics whose value remains disputed.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | G2 | 58 |
| 2 | Profound | 52 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 76 |
| 5 | Semrush | 46 |
| 6 | Ahrefs | 50 |
| 7 | Vercel | 61 |
| 8 | AirOps | 41 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Peec AI | 29 |
A shared revenue knowledge layer that people and agents can query and update.
GTM Brain has oscillated rather than sustained a climb, with the last 30 days down 3.2%. October’s rebound coincided with concrete context-layer activity: ZoomInfo announced its Workbounce acquisition, and Ariel Cohen described a shared GTM memory in Swan AI. Those examples give the recurring conversation substance, but the curve does not yet support Short’s prediction of year-end dominance.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 95 |
| 4 | HubSpot | 90 |
| 5 | Exa.ai | 51 |
| 6 | Supabase | 50 |
| 7 | ZoomInfo | 51 |
| 8 | Attio | 51 |
| 9 | Codex | 82 |
| 10 | Cursor (Anysphere) | 75 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing automation recovered from its June low, then held near 0.6% share from July through October; the last 30 days are down 28.9%. The plateau contains a recurring tension rather than a single catalyst: Bloomreach describes targeted booking and retention campaigns, while Tom Fishburne critiques automated pressure to buy. ActiveCampaign’s earlier autonomy pitch supplies another angle on that debate.
Posts to understand this
 inCustomer dealFaceland chooses Bloomreach for unified customer data and targeted clinic campaignsTF
 inCustomer critiqueTom Fishburne critiques automated offers that ignore customer purchase readinessA
 inProduct positioningActiveCampaign describes workflows built from prompts and segments generated from behavior
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Salesforce | 95 |
| 3 | Braze | 39 |
| 4 | Clay | 94 |
| 5 | Claude Code | 99 |
| 6 | Nooks | 49 |
| 7 | Apollo.io | 48 |
| 8 | Intercom | 43 |
| 9 |  Klaviyo | 38 |
| 10 |  ActiveCampaign | 30 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Salesforce’s Headless 360 reveal gives April’s high a clear anchor: Salesforce, Agentforce and Slack exposed through APIs, MCP and CLI. Share faded through July, recovered into September, then slipped in October; the last 30 days are down 30.3%. Glean’s October workflow extends the same idea into agent development, but the posts do not explain the intervening rebound.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Claude Code | 99 |
| 4 | Clay | 94 |
| 5 | ZoomInfo | 51 |
| 6 | Vercel | 61 |
| 7 | Apify | 54 |
| 8 | Braze | 39 |
| 9 | Exa.ai | 51 |
| 10 | Replit | 56 |
The work of earning awareness, trust and preference for a company over time.
Brand Building fell sharply in September and stayed near that lower level in October; the last 30 days now show a 19.3% recovery, against a 30.4% decline over 90 days. The posts trace a recurring measurement problem, from Fin’s awareness survey to Peep Laja’s budget argument. Ross Simmonds extends it to AI search, where citations may omit the brand.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 46 |
| 2 | Clay | 94 |
| 3 | Gong | 63 |
| 4 | HubSpot | 90 |
| 5 | Primer | 33 |
| 6 | Profound | 52 |
| 7 | SparkToro | 28 |
| 8 | Ahrefs | 50 |
| 9 | AirOps | 41 |
| 10 | Demandbase | 36 |
Deciding what to build, why it matters and which product bets come first.
Product Strategy spiked in May, then settled into a narrower range from July through October; its latest 30-day share is up 40.8%. No single event explains that shape: the posts pair a recurring debate over product marketing’s influence on roadmaps with Automation Anywhere’s agreement to acquire boost.ai. The acquisition gives the discussion a concrete expansion into customer-facing conversational and voice AI.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Clay | 94 |
| 3 | Salesforce | 95 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 51 |
| 6 | OpenRouter | 53 |
| 7 | Apify | 54 |
| 8 | Resend | 32 |
| 9 | Vercel | 61 |
| 10 | ZoomInfo | 51 |
Teams building internal software with AI instead of buying another SaaS product.
Replacing SaaS with internal tools has lost share since April, with a brief July rebound and another drop in October; the last 30 days are down 29.2%. The posts consistently challenge blanket replacement: Slack and Granola examples emphasize maintenance and opportunity cost, while Frans Riemersma describes a mix of SaaS augmentation, AI-native products, and selective internal builds.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Apify | 54 |
| 5 | Exa.ai | 51 |
| 6 | Vercel | 61 |
| 7 | ZoomInfo | 51 |
| 8 | OpenRouter | 53 |
| 9 | Resend | 32 |
| 10 | Webflow | 49 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-serve discussion fell from April to May, recovered through July and August, then declined through October. The last 30 days are up 30.2%, although the last 90 remain down 7.5%. The selected posts illustrate a recurring tension: self-serve can support adoption and scale, while an enterprise push can pull attention away from it.
Posts to understand this
 inEnterprise tensionVerna describes how enterprise priorities can displace self-serve product investmentSWinAdoption exampleWoody reports Metronome opened self-serve access alongside increased user onboardingJR
 inRecent exampleRobin highlights Retell’s reported revenue scale and signup without sales
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | HubSpot | 90 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 51 |
| 6 | FullEnrich | 45 |
| 7 | Apify | 54 |
| 8 | Gong | 63 |
| 9 | OpenRouter | 53 |
| 10 | Primer | 33 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales Tech’s share roughly halved between April and October, but the last 30 days show a 13.3% lift against a 36.3% decline over 90 days. The posts share a practical thread rather than a single catalyst: Gong’s revenue AI system, Airscale’s data APIs, and a proposed workflow across Clay, Claude, n8n and HubSpot.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | Claude Code | 99 |
| 5 | Gong | 63 |
| 6 | ZoomInfo | 51 |
| 7 | Codex | 82 |
| 8 | Grok Bot | 76 |
| 9 | Nooks | 49 |
| 10 | Seismic | 29 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound Systems peaked in May, then lost share each month through October; the last 30 days show a 15.4% uptick. April’s sender-capacity discussion preceded that slide, May’s operator checklist captured the infrastructure workload at the peak, and August’s agent skills showed continued system-building discussion as share declined.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | HubSpot | 90 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 95 |
| 5 | HeyReach | 55 |
| 6 | RB2B | 50 |
| 7 | BetterContact | 44 |
| 8 | Grok Bot | 76 |
| 9 | Instantly | 66 |
| 10 | Lemlist | 50 |
Tracing and monitoring what a model or agent did during a production run.
Observability held a fairly steady base before a late-summer climb into September, then eased in October; the last 30 days are down 12.8%. No single launch explains that shape: Intercom’s March Fin suite, CrewAI’s September account of bank procurement friction, and Gartner’s November focus on cost and governance all connect visibility into agents with practical buying requirements.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | LangChain | 45 |
| 2 | Vercel | 61 |
| 3 | Baseten | 43 |
| 4 | Claude Code | 99 |
| 5 | Codex | 82 |
| 6 | HubSpot | 90 |
| 7 | Midjourney | 33 |
| 8 | Attio | 51 |
| 9 | Clay | 94 |
| 10 |  CrewAI | 25 |
Using AI to tailor outreach and marketing to each person at scale.
Share declined from April into a September–October plateau, while the last 30 days show a 41.2% recovery. The recurring thread is dissatisfaction with superficial personalization: Kyle Asay used AI to narrow accounts, Nick Palasz argued for relevance over observations, and Kelly Jo Horton praised Chewy’s human service. Renewed attention includes criticism of automation, not just adoption.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | HubSpot | 90 |
| 4 | Claude Code | 99 |
| 5 | Vercel | 61 |
| 6 | ElevenLabs | 57 |
| 7 | Exa.ai | 51 |
| 8 | Gong | 63 |
| 9 | Grok Bot | 76 |
| 10 | Replit | 56 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
Events conversation has moved in bursts, with May, July and October highs rather than a sustained climb; share is down 21.5% over the last 30 days and nearly flat over 90 days. No single event explains those swings. The recurring case is practical: trusted face-to-face contact, outreach tied to specific locations, and more pipeline from existing trade show budgets.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Clay | 94 |
| 3 | Lovable | 61 |
| 4 | HubSpot | 90 |
| 5 | Webflow | 49 |
| 6 |  Aurasell | 16 |
| 7 | Optimizely | 34 |
| 8 | Primer | 33 |
| 9 | AirOps | 41 |
| 10 | Apify | 54 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI security held relatively steady from May through August, dropped in September, and recovered some ground in October; the last 30 days are up 8.4%, against a 42.1% decline over 90 days. Vanta’s growth story and OpenAI’s GPT-Red announcement anchor the earlier discussion. Dust’s November Datadog AI Guard beta adds a concrete example of checks inside agent workflows.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 82 |
| 3 | Midjourney | 33 |
| 4 | Attio | 51 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | Firecrawl | 42 |
| 7 |  Pitch | 16 |
| 8 | Runway | 36 |
| 9 | Salesforce | 95 |
| 10 | Synthesia | 27 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Conversation share fell from May through October and is down another 19.4% over the last 30 days. The posts point to a recurring challenge to volume: Amos Bar-Joseph criticizes recognizable AI prose, while Eli Schwartz warns about Google's treatment of spam. Dima Bilous offers a practical counterpoint, with a Claude Code content system tied to booked calls.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | Claude Code | 99 |
| 3 | Clay | 94 |
| 4 | G2 | 58 |
| 5 | HubSpot | 90 |
| 6 | Peec AI | 29 |
| 7 | Salesforce | 95 |
| 8 | AI Ark | 49 |
| 9 | AirOps | 41 |
| 10 | Apify | 54 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
AI employees held a relatively steady share from June through September before a sharp October drop; the last 30 days are nearly flat, down 0.8%. The posts offer no single cause for the decline, but they move from Vista’s digital-worker thesis to concrete deployment questions: an open-source company brain in Slack and Databricks’ staged rollout of governed AI coworkers.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Viktor | 36 |
| 2 | Clay | 94 |
| 3 | HubSpot | 90 |
| 4 | Salesforce | 95 |
| 5 | Ploy | 31 |
| 6 | Primer | 33 |
| 7 | 6sense | 46 |
| 8 | Ahrefs | 50 |
| 9 | Apify | 54 |
| 10 | Claude Code | 99 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
May’s high coincided with Gong reporting more than $500 million ARR and explicitly crediting consolidation for growth. Share settled into a lower September–October plateau even as Apollo presented a complete AI GTM system, suggesting broader platforms remained a recurring pitch without another comparable spike. The last 30 days are up 15.5%, against a 36% decline over 90 days.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Salesforce | 95 |
| 3 | Clay | 94 |
| 4 | Gong | 63 |
| 5 | Claude Code | 99 |
| 6 | Clari | 32 |
| 7 |  Fathom | 35 |
| 8 | Outreach | 43 |
| 9 | ZoomInfo | 51 |
| 10 | Braze | 39 |
Multi-step work planned and executed by agents instead of fixed automation rules.
Agentic Workflows peaked in May, faded through August, rebounded in September and fell again in October; the latest 30 days are down 31.8%. May’s discussion centered on revenue outcomes and missing ownership, while October brought Clay’s global agent and Aurasell’s reported sales results. The pattern is repeated implementation evidence without a sustained rise, rather than one launch that resets the curve.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 90 |
| 3 | Salesforce | 95 |
| 4 | Clay | 94 |
| 5 | Instantly | 66 |
| 6 | AI Ark | 49 |
| 7 | Codex | 82 |
| 8 | Exa.ai | 51 |
| 9 | Findymail | 45 |
| 10 | HeyReach | 55 |
Approval and review steps that keep a person involved in an agent's work.
Human in the Loop has produced bursts rather than sustained growth, with May and August highs followed by declines through October. The last 30 days are down 13%, while the 90-day move is nearly flat. No single event explains those bursts; the recurring thread is practical oversight, from Tenex’s approvals and audit trails to Yahoo DSP’s discussion of trust.
Posts to understand this · as of Nov 12
 inOversight discussionYahoo DSP’s Emily Ray discusses agent interoperability, trust and human oversightCH
 inAutonomy frameworkCarolyn Healey proposes AI maturity stages centered on autonomy and accountabilityAL
 inAgent launchTenex launches enterprise agents with permissions, approvals and audit trails
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Salesforce | 95 |
| 3 | HubSpot | 90 |
| 4 | Vercel | 61 |
| 5 | Claude Code | 99 |
| 6 | HeyReach | 55 |
| 7 | Instantly | 66 |
| 8 | Nooks | 49 |
| 9 |  Pinecone | 32 |
| 10 | Smartlead | 46 |
Founders running early sales themselves before handing the motion to a sales team.
July’s spike coincided with Peter Kazanjy opening free Founding Sales copies to founders beyond accelerator communities. Conversation settled into a steadier band from August through October, with a 3.4% lift over the last 30 days. The recurring questions are practical: Jason Lemkin on first sales hires and Mark Roberge on retention as evidence of product-market fit.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Clay | 94 |
| 3 | Salesforce | 95 |
| 4 |  Clarify | 29 |
| 5 | Claude Code | 99 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | Granola | 54 |
| 8 | Lovable | 61 |
Writing and structuring the instructions a model follows.
Prompt engineering reached its highest monthly share in June, then declined through October; the last 30 days are down 20.3%. No single event explains that retreat, but the posts consistently question prompts as the main source of value. Carolyn Healey emphasizes context, Laurens Nys calls for agents with setup already done, and Wil Reynolds warns that polished prompts still leave recognizable patterns.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | Gong | 63 |
| 4 | HubSpot | 90 |
| 5 |  Reachdesk | 26 |
| 6 | SparkToro | 28 |
How sales teams use AI and how it changes the work of selling.
Conversation share peaked in May, fell in June, stayed flat in July, then declined through October. The last 30 days are nearly flat, up 1%. Selected posts span June’s push to hire AI-fluent sellers, October’s account of workflow adoption problems, and November’s criticism of hours saved as a measure of revenue impact.
Posts to understand this · as of Nov 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Clay | 94 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | Lovable | 61 |
| 5 | Braze | 39 |
| 6 | HubSpot | 90 |
| 7 | Monaco | 31 |
| 8 |  Vivun | 15 |
| 9 | 11x | 24 |
| 10 | Apollo.io | 48 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
After a May high and an August low, lifecycle marketing recovered modestly in September and October; its last 30 days are up 11%. The evidence points to repeated attempts to make customer outreach more useful and easier to run, rather than one catalyst. Lifecycle Studio, Customer.io's Americaneagle.com partnership and Lorikeet Dreamweaver span campaign production, data activation and individual AI account managers.
Posts to understand this · as of Nov 11
 inProduct launchLorikeet introduces Dreamweaver with an AI account manager for each customerC
 inAgency partnershipCustomer.io partners with Americaneagle.com on data activation and lifecycle messagingTM
 inCampaign workflowLifecycle Studio launches with Thumbtack reporting shorter campaign production cycles
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Salesforce | 95 |
| 3 | Clay | 94 |
| 4 | GrowthLoop | 29 |
| 5 | Supabase | 50 |
| 6 | 6sense | 46 |
| 7 | AI Ark | 49 |
| 8 | Ahrefs | 50 |
| 9 | Airtable | 41 |
| 10 | Apify | 54 |
AI sales agents that respond to inbound interest, engage website visitors, qualify leads and connect prospects with sales teams.
June’s brief rebound coincided with HubSpot’s Warmly acquisition announcement, but conversation share fell through August before recovering in September and October. October’s evidence included Single Grain testing a voice bot that calls demo leads within 60 seconds; no single supplied event explains the recovery. The latest 30 days are down 16.6%, tempering a 21.3% gain over 90 days.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Vercel | 61 |
| 3 | Salesforce | 95 |
| 4 | HubSpot | 90 |
| 5 | Qualified | 28 |
| 6 | Primer | 33 |
| 7 | 11x | 24 |
| 8 | 1mind | 36 |
| 9 | Apify | 54 |
| 10 | Braze | 39 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce shows a conference-shaped spike: almost absent in spring, higher in August, then at 3.7% in September before a sharp October drop. Salesforce’s Anthropic partnership promotion, Informatica’s debut as part of Salesforce and debate over conference ROI all cluster in September. The last 30 days are down 87.8%, consistent with that concentrated event cycle.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | 1mind | 36 |
| 5 | ZoomInfo | 51 |
| 6 | 11x | 24 |
| 7 |  AiSDR | 21 |
| 8 | Apify | 54 |
| 9 |  Base44 | 27 |
| 10 | Braze | 39 |
Advantages that grow stronger as more people, data or participants join a product.
Network effects declined every month from April through October, though the last 30 days show a 24.3% lift. The evidence moves from broad moat arguments around Snapchat and ChatGPT to Casado’s October critique of what qualifies as a network effect. That shift gives the conversation a sharper question, but no single event explains the long decline or recent lift.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | Cursor (Anysphere) | 75 |
| 3 | OpenRouter | 53 |
| 4 | Salesforce | 95 |
| 5 | Attio | 51 |
| 6 | Clay | 94 |
| 7 |  Railway | 34 |
| 8 | Vercel | 61 |
| 9 |  BlitzAPI | 27 |
| 10 |  Calendly | 39 |
Systems where several agents divide a job, coordinate their work and combine the result.
Share peaked in May and declined through October, with a further 62.1% drop over the last 30 days. No single event explains the slide: Workato expanded Airo, Mercor reported a 100-plus-subagent run, and ZoomInfo acquired DoubleO.ai during the decline. These posts emphasize workflow reliability and evaluation, but those concrete developments did not sustain broader conversation share.
Posts to understand this · as of Nov 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 90 |
| 4 | Grok Bot | 76 |
| 5 | Vercel | 61 |
| 6 | Apify | 54 |
| 7 | Clay | 94 |
| 8 | ElevenLabs | 57 |
| 9 | Firecrawl | 42 |
| 10 |  Lambda | 28 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
Outcome-based pricing climbed into May, faded through August, then recovered in September and October; the last 30 days are up 73.6%. The evidence spans actual prices, billing infrastructure and a growth story: HubSpot’s per-result agent fees, Salesforce’s m3ter agreement and November’s Sierra interview. That recurring commercial detail gives the conversation fresh hooks without one event explaining the whole curve.
Posts to understand this · as of Nov 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 95 |
| 2 | HubSpot | 90 |
| 3 | Clay | 94 |
| 4 | G2 | 58 |
| 5 | Ahrefs | 50 |
| 6 | Claude Code | 99 |
| 7 | Conversion | 29 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Exa.ai | 51 |
| 10 | FullEnrich | 45 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing climbed through summer and held near 1.1% of conversation in August and September, with Cursor’s router launch and reported Harvey margin pressure giving it concrete product and cost hooks. October broke that plateau, and the last 30 days are down 71.9%. Notion’s cheaper Auto router supplied fresh news, but did not sustain the earlier share.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Canva | 51 |
| 2 | Higgsfield | 41 |
| 3 | OpenRouter | 53 |
| 4 | Baseten | 43 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | Lovable | 61 |
| 7 | Replit | 56 |
| 8 | Substack | 51 |
| 9 | Claude Code | 99 |
| 10 | ElevenLabs | 57 |
Time-limited access that lets a buyer test a product before paying.
Free trials gained share from April through July, then lost ground unevenly; the last 30 days are down 14.2%. No single event explains the decline, but the posts share a concern: trial mechanics can obstruct the purchase. Sam Kuehnle describes delayed follow-up, Sunsama offers unused trials another chance, and Ora’s earlier experiment replaced a timed trial with payment at campaign launch.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 | AI Ark | 49 |
| 3 | Canva | 51 |
| 4 | Claude Code | 99 |
| 5 | Clay | 94 |
| 6 | Fibbler | 36 |
| 7 |  Freckle.io | 33 |
| 8 | G2 | 58 |
| 9 | Gong | 63 |
| 10 | Intercom | 43 |
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
The May high coincided with Polsia’s reported $10 million run rate, one employee, and $30 million fundraise; attention then sank through August. September and October brought concrete workflow examples from Swan AI and debate over solo founders’ limits. Share is up 111.1% over the last 30 days, though the 90-day trend remains down 47%.
Posts to understand this · as of Nov 13
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Lovable | 61 |
| 3 | Base44 | 27 |
| 4 | Canva | 51 |
| 5 | Codex | 82 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | G2 | 58 |
| 8 | Grok Bot | 76 |
| 9 | Salesforce | 95 |
| 10 | Twilio | 43 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium’s August–September recovery coincided with OpenAI’s report that ChatGPT ads reached a $1 billion annualized revenue run rate to help fund free access. Share eased in October, and the last 30 days are down 45%. Across OpenAI, Fireflies, and Perplexity, the recurring thread is how free usage supports revenue through ads, paid agent work, or enterprise sales.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | HubSpot | 90 |
| 3 | Attio | 51 |
| 4 | Canva | 51 |
| 5 | Claude Code | 99 |
| 6 | Grok Bot | 76 |
| 7 | Salesforce | 95 |
| 8 | Synthesia | 27 |
| 9 | Vercel | 61 |
| 10 | Airtable | 41 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise marketing held near its summer high in July and August, then slipped in September and October; the last 30 days are down another 15.2%. Canva’s LinkedIn campaign-workflow event fits that summer focus on execution. Iterable’s October CustomerLake beta announcement adds a concrete data-to-activation story, but the curve shows no sustained renewal of attention around these workflow and coordination themes.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 90 |
| 2 |  Creatio | 17 |
| 3 | Grok Bot | 76 |
| 4 | Salesforce | 95 |
AI-generated creators, avatars and user-style content used in marketing.
Conversation share shrank from 0.36% in April to 0.09% in August, then recovered partly in September alongside HeyGen’s research on unpublished business videos. The last 30 days are flat, so the recovery has not become sustained acceleration. The recurring tension is practical production help versus authenticity, visible in Corey Haines’ tooling and alinav’s avatar critique.
Posts to understand this · as of Nov 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HeyGen | 34 |
| 3 | Apify | 54 |
| 4 | Exa.ai | 51 |
| 5 | Instantly | 66 |
| 6 | AppsFlyer | 19 |
| 7 | Clay | 94 |
| 8 |  Framer | 29 |
| 9 | Gamma | 45 |
| 10 | Higgsfield | 41 |
The online channel mix used to reach, convert and retain customers.
Digital marketing rose through June, slid to a September low and rebounded in October; the last 30 days are up 73.9%. No supplied post pinpoints the rebound’s cause. The recurring thread is how channels work together as AI changes discovery, from Ahrefs’ Agent A to EasyVista’s connected stack, with an older warning from Elaine Zelby about declining digital trust.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 94 |
| 2 | Ahrefs | 50 |
| 3 | AirOps | 41 |
| 4 | Monaco | 31 |
| 5 | Semrush | 46 |
| 6 | Apollo.io | 48 |
| 7 | Baseten | 43 |
| 8 | Claude Code | 99 |
| 9 | Codex | 82 |
| 10 | Cursor (Anysphere) | 75 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
AI positioning and sameness lost share every complete month from April through October, with another 31.7% decline over the last 30 days. The posts repeat the concern across content teams, consulting firms and outbound email rather than identify a single cause for the slide. Lemlist’s November session shows the problem still surfaces in customer conversations despite its shrinking share.
Posts to understand this
inContent critiqueA marketing diary depicts AI content without customer knowledge or positioningMR inConsulting critiqueMelissa Rosenthal questions differentiation when consulting firms adopt similar AI playbooksL
 inCustomer questionsLemlist addresses customer questions about repetitive AI emails and outbound
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay |