What’s moving now
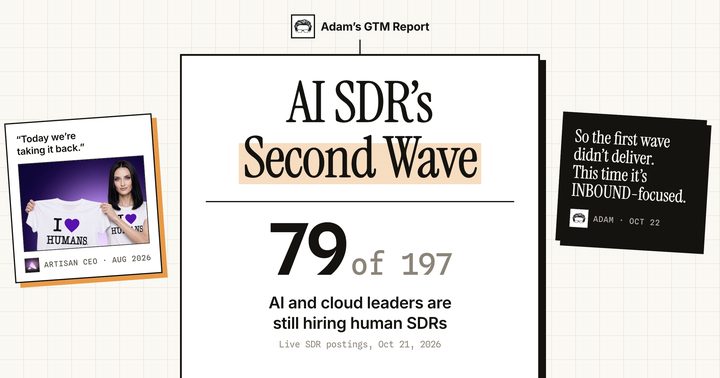 AI SDR's Second WaveOct 22 · Outbound didn't stick. The inbound bet. Clay's move. Agent
 46.9× the usual response · 797 engagements
 23.6× the usual response · 165 engagements
 15.2× the usual response · 3,011 engagements
 14.2× the usual response · 559 engagements
 13.5× the usual response · 2,415 engagements
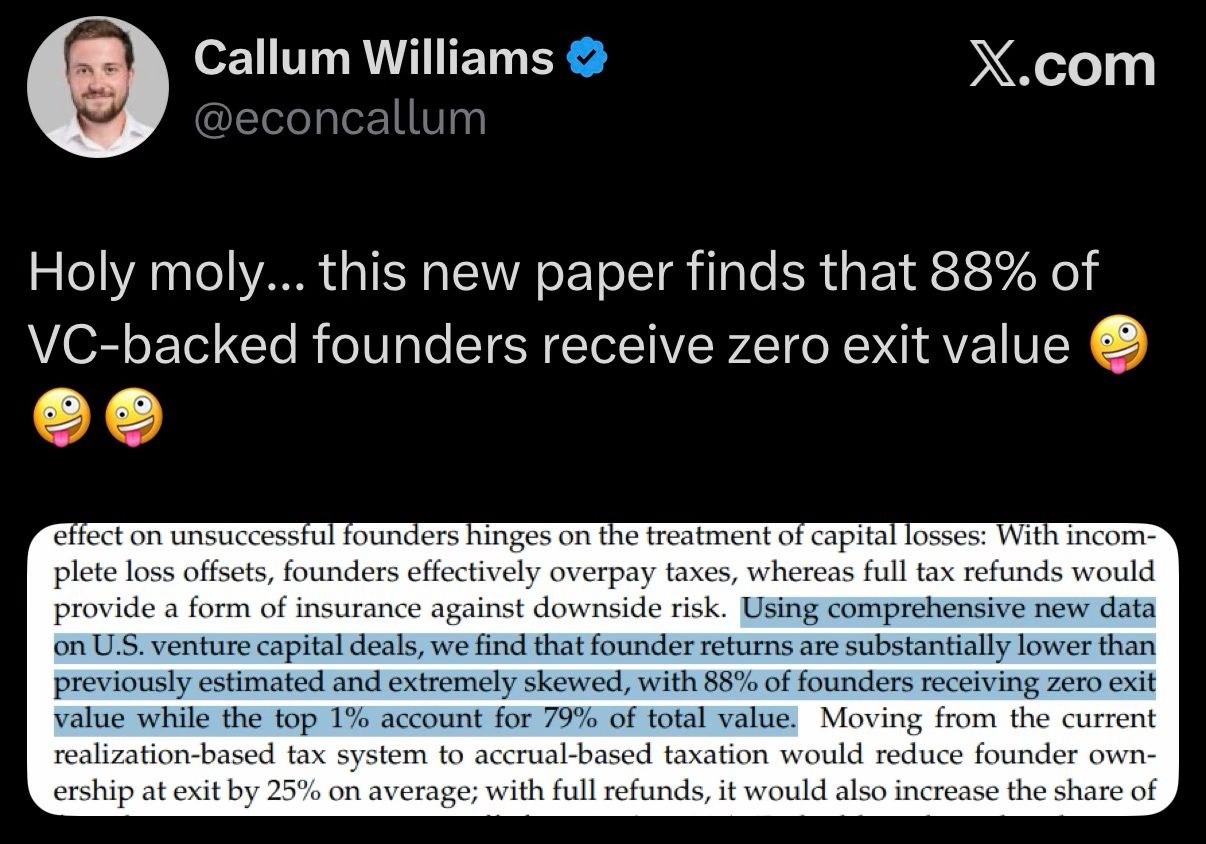
 Peter WalkerCites a paper reporting 88% of VC-backed founders receive no exit value, arguing startup failures and investor liquidation preferences constrain founder returns.
 1,828 interactions · 1d agoTrending Creator
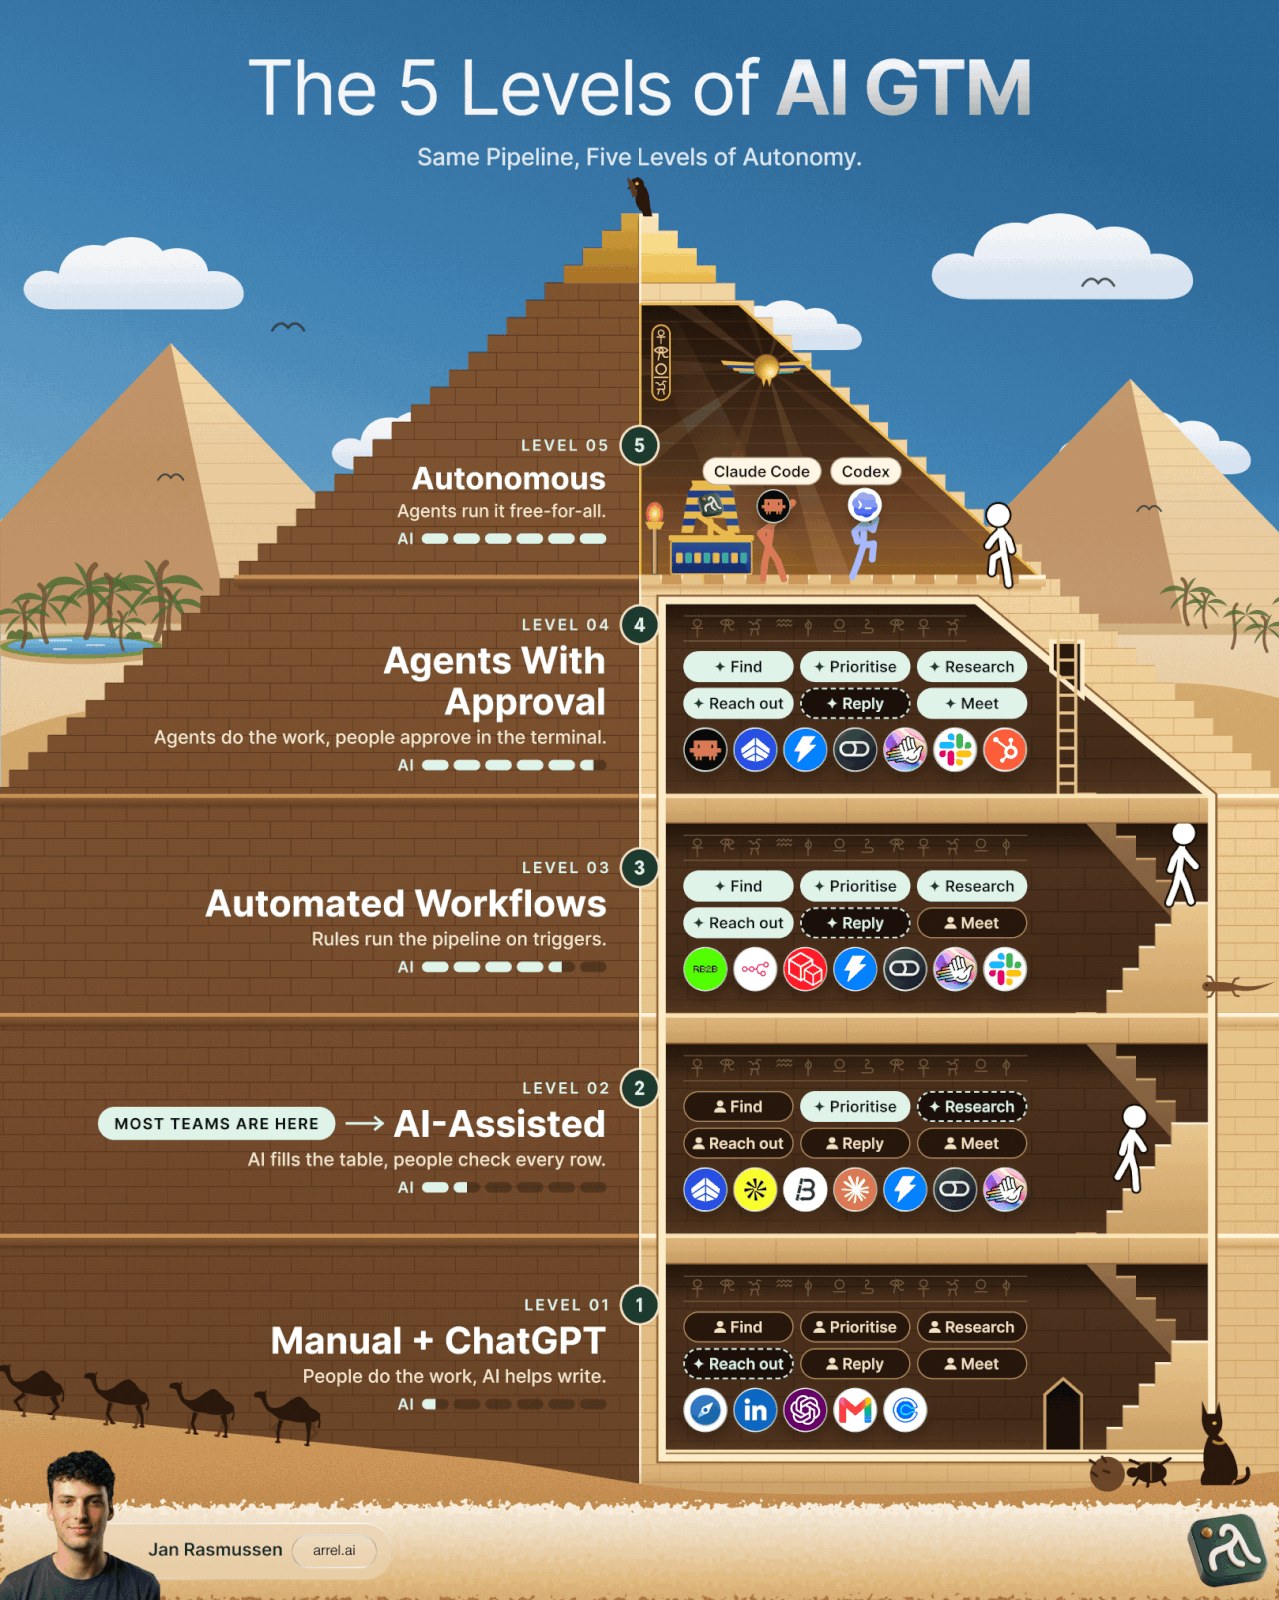
 Jan RasmussenProposes five levels of AI in GTM, progressing from manual work with ChatGPT to autonomous agents, distinguished by who performs tasks and approves actions.
 676 interactions · 23h agoTrending Creator
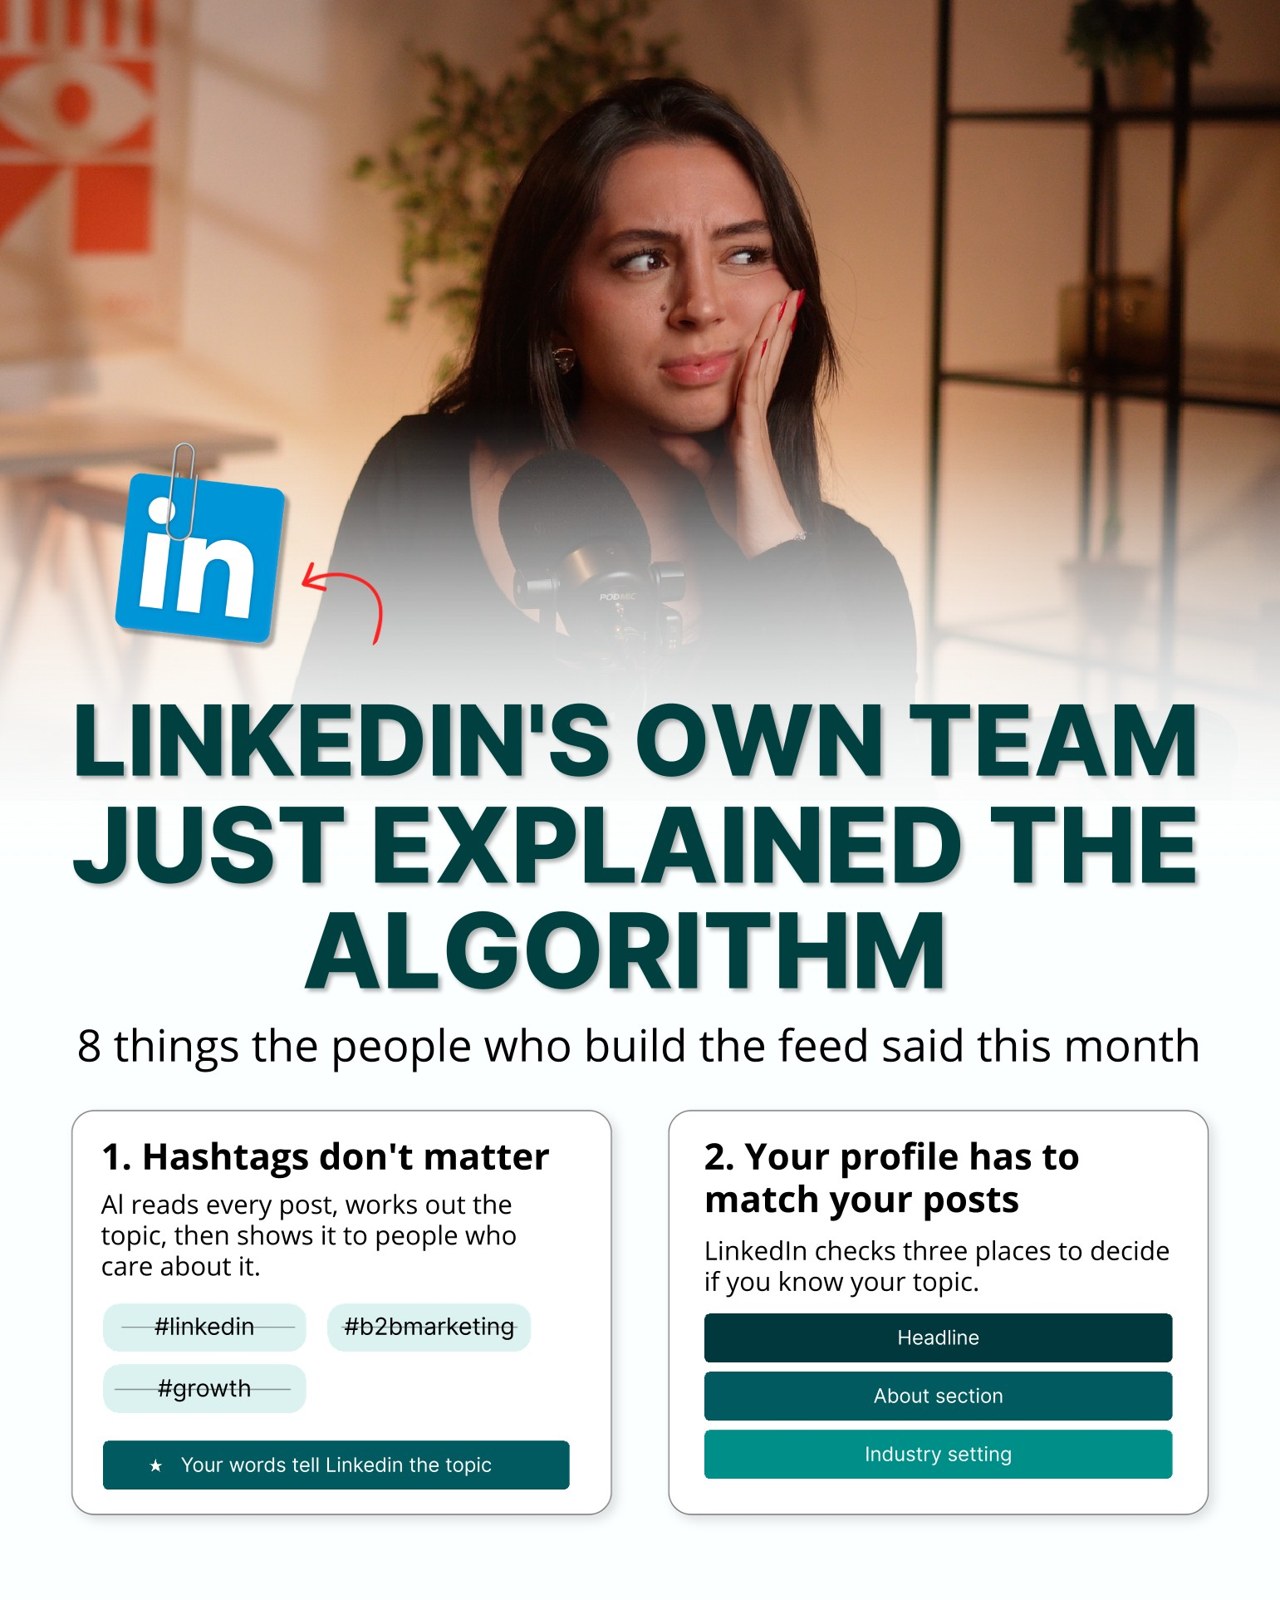
 Diandra EscobarReports creator Q&A notes saying hashtags offer no benefit, links and scheduling do not reduce reach, and time spent peaks around 175 words.
 591 interactions · 20h agoTrending Creator
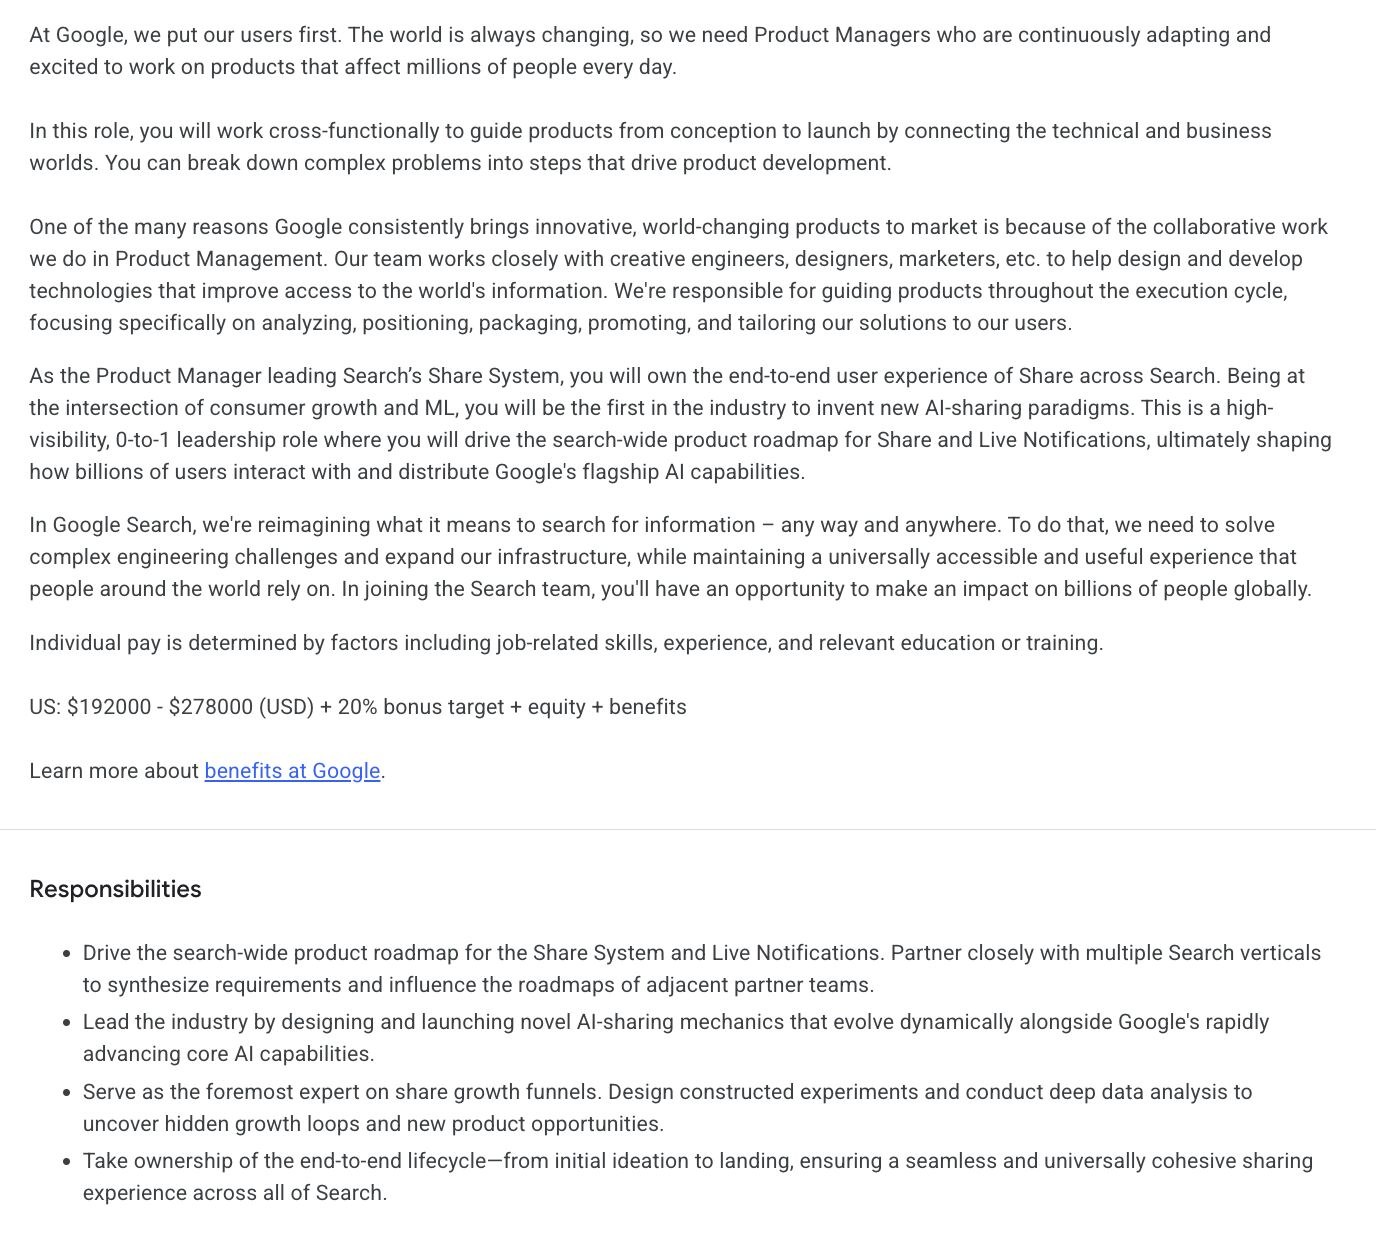
 Eli SchwartzInterprets a Google job listing as signaling shared AI search experiences and live notifications, predicting weaker attribution and declining publisher referrals.
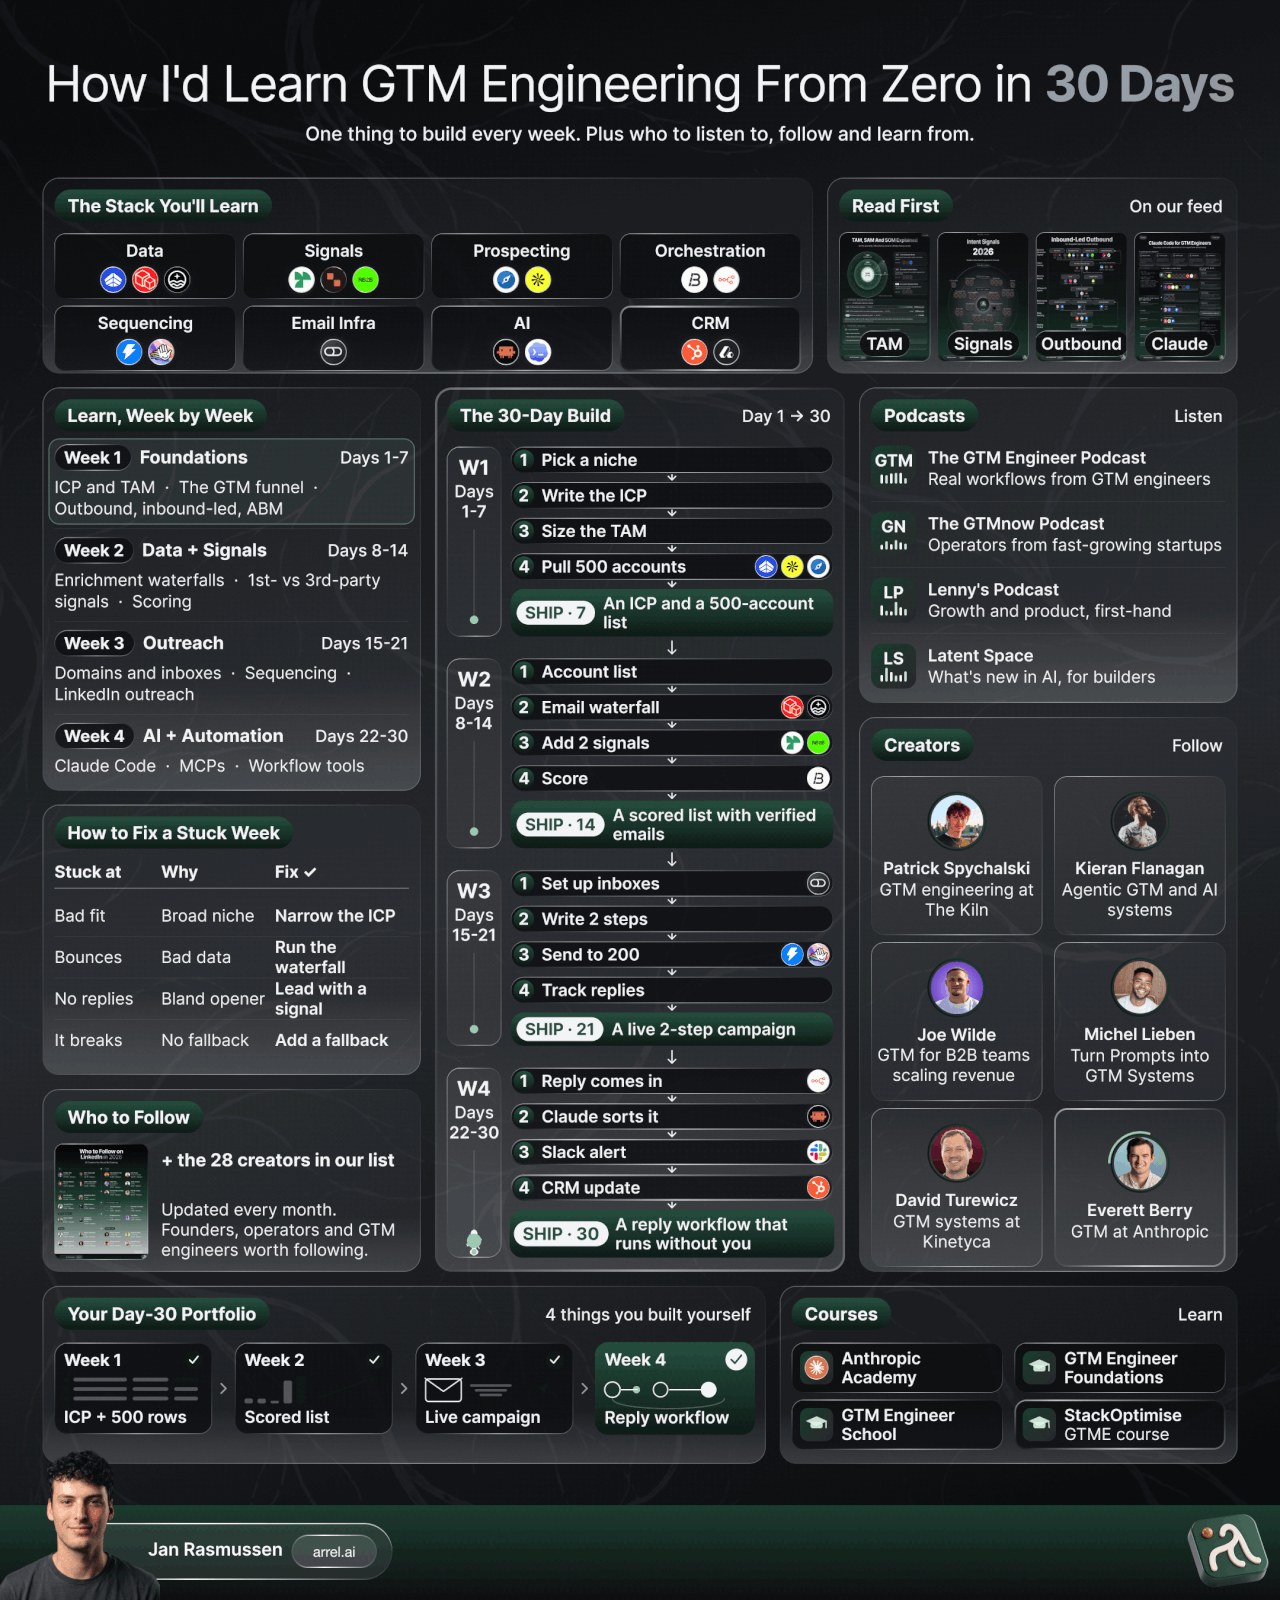
 492 interactions · 1d agoTrending CreatorJan RasmussenProposes a 30-day GTM engineering curriculum with weekly projects covering account targeting, verified contact data and signals, outreach campaigns, and automated reply handling.
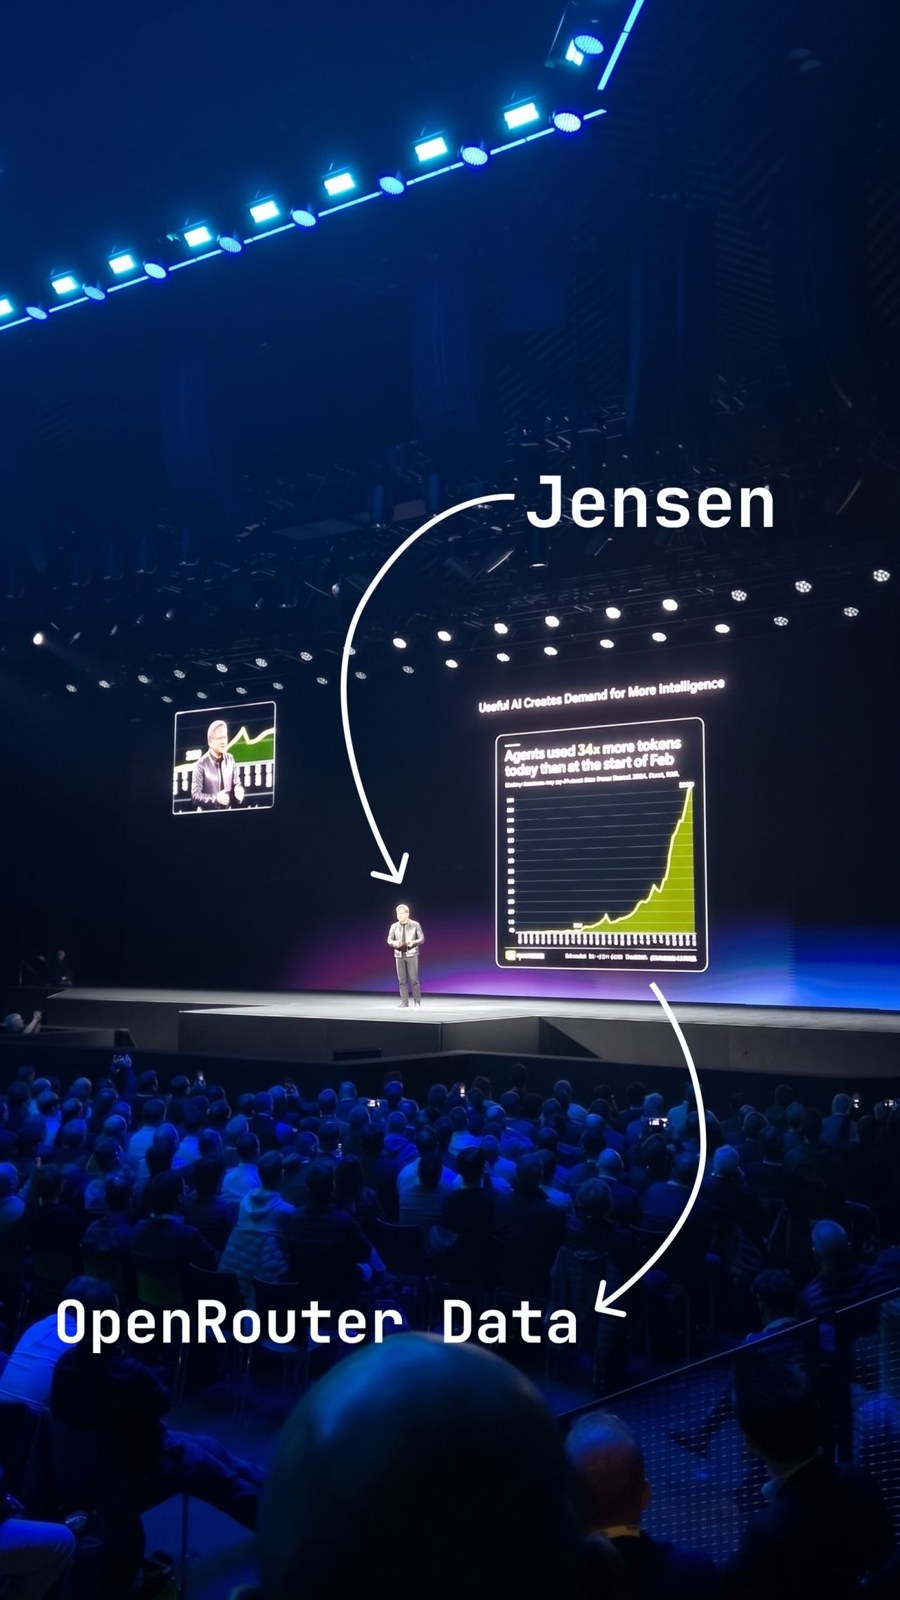
 456 interactions · 2d agoTrending CreatorPeter WalkerArgues insights teams build customer trust and credibility through shared data, potentially earning exposure from Jensen at GTC Berlin.
 375 interactions · 2d agoTrending Creator
 Dave GerhardtArgues AI agents are changing buying research and promotes a Friday session featuring eight marketers demonstrating tactics they used to improve AI search visibility.
 375 interactions · 2d agoTrending Creator
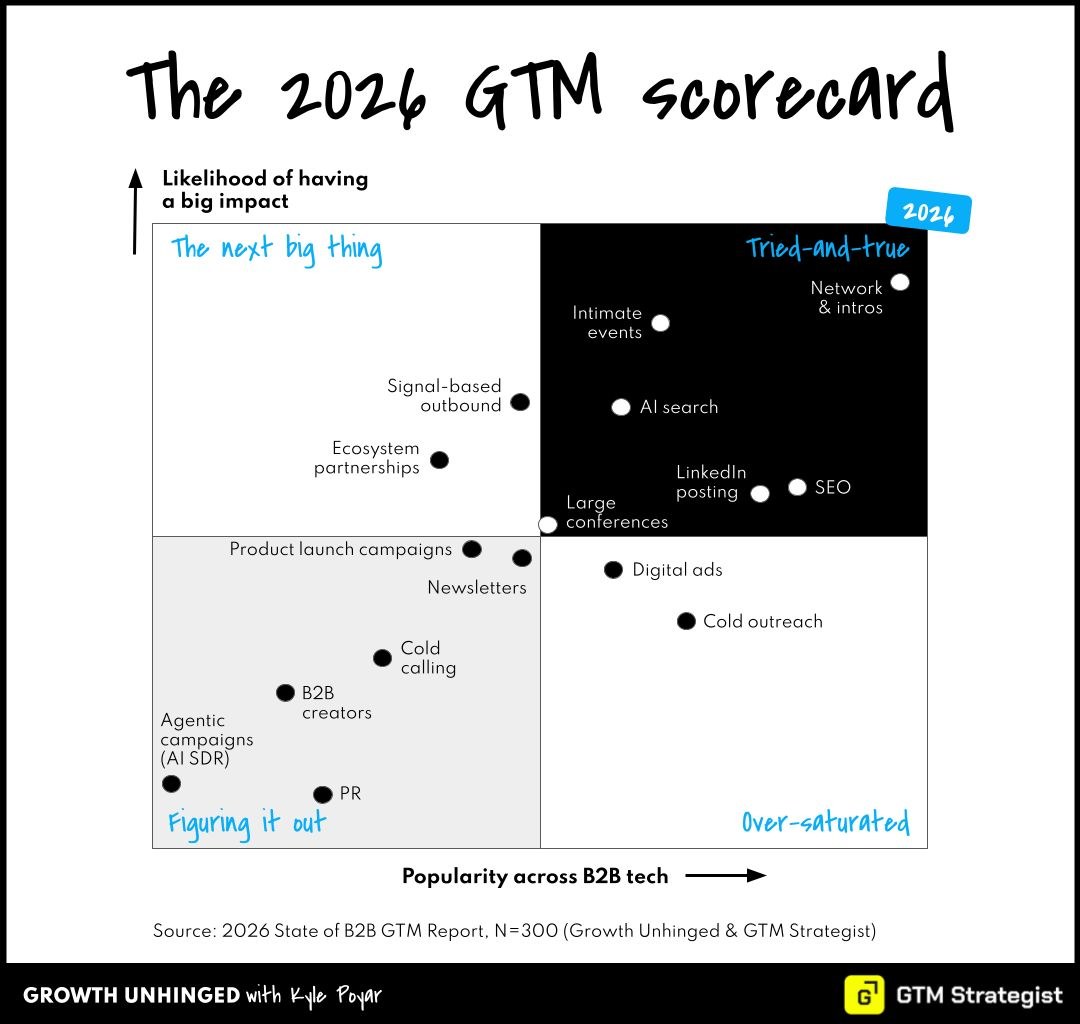
 Kyle PoyarPresents a survey of 300 B2B leaders, ranking networks, intimate events and AI search highest, with PR and AI SDR campaigns lowest.
 356 interactions · 20h agoTrending topicFree Trial+117% vs prior 30d · 0.3% of the conversationTrending topicInfluencer Marketing & Creator Partnerships+77.7% vs prior 30d · 1.1% of the conversationTrending topicIn-Person Events & Field Marketing+64.5% vs prior 30d · 0.6% of the conversationTrending topicAI-Driven Advertising+57.9% vs prior 30d · 0.6% of the conversationTrending topicSales Development+47.6% vs prior 30d · 0.6% of the conversation
 Grok Bot↑4 places in Coding Agents & Harnesses for GTMBraze↑41 places in GTM Developer Tools
 Docket↑26 places in AI-Native GTM Challengers
 Tavily↑29 places in GTM Developer Tools
 TitanX↑21 places in AI-Native GTM Challengers
Trending Topics
Market Moves
559 engagements · 14.2× usualPost ↗ 57 engagements · 0.6× usualPost ↗
 4,558 engagements · 10.1× usualPost ↗
 780 engagements · 4.8× usualPost ↗
 2,678 engagements · 1.5× usualPost ↗78 engagements · 7.1× usualPost ↗
 47 engagements · 7.8× usualPost ↗
GTM Tech Index
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
Featured trends
All topics
BetaFigures move as the panel grows and definitions sharpen.
+1.0%vs prior 30d+15.8%vs prior 30d-21.9%vs prior 30d+9.7%vs prior 30d-3.0%vs prior 30d-1.4%vs prior 30d -54.2%vs prior 30d-27.7%vs prior 30d
 +223%vs prior 30d+5.2%vs prior 30d-4.2%vs prior 30d+71.2%vs prior 30d-8.4%vs prior 30d+7.3%vs prior 30d+16.9%vs prior 30d
 +0.6%vs prior 30d+16.5%vs prior 30d+18.2%vs prior 30d-73.9%vs prior 30d+18.9%vs prior 30dNEWvs prior 30d-17.5%vs prior 30d-5.7%vs prior 30d+64.8%vs prior 30d+6.7%vs prior 30d+36.5%vs prior 30d+35.2%vs prior 30d-11.2%vs prior 30d-13.4%vs prior 30d+22.6%vs prior 30d
 -17.2%vs prior 30d+25.1%vs prior 30d-16.5%vs prior 30d-31.9%vs prior 30d-17.1%vs prior 30d+22.7%vs prior 30d+256%vs prior 30d-13.4%vs prior 30d
 +33.0%vs prior 30d
 -18.3%vs prior 30d-15.3%vs prior 30d
 -55.0%vs prior 30d-23.4%vs prior 30d
 -60.3%vs prior 30d
 +49.2%vs prior 30d
 -37.4%vs prior 30d
 +10.3%vs prior 30d
 +25.5%vs prior 30d
 -22.9%vs prior 30d+41.2%vs prior 30d
 +73.6%vs prior 30d
 +27.2%vs prior 30d
 -48.9%vs prior 30d
 -33.0%vs prior 30d
 ±0%vs prior 30d
 +33.3%vs prior 30d
 -4.3%vs prior 30d-39.3%vs prior 30d
 +6.1%vs prior 30d
 -9.6%vs prior 30d-82.7%vs prior 30d-21.6%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
Building GTM Agents remains a large conversation at 18.4% current share, but has broadly receded since April and is down 10.1% over the last 30 days. The posts show practical builds and new infrastructure rather than one shared catalyst: a Claude deal timeline, proposed business world models, and Zapier MCP alongside early access to Next Gen Zaps.
Posts to understand this · as of Oct 20
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 85 |
| 3 | Grok Bot | 73 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 92 |
| 6 | HubSpot | 88 |
| 7 | Salesforce | 94 |
| 8 | Lovable | 60 |
| 9 | Replit | 56 |
| 10 | Instantly | 64 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO reached its high in June, alongside HubSpot’s concrete pitch: use AEO to get Loverboy into AI cocktail recommendations. Share then declined through September, but the last 30 days are up 13.1%; Kyle Poyar’s survey now puts AEO first for adoption growth, suggesting a shift from experimentation toward channel investment.
Posts to understand this · as of Oct 22
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | Ahrefs | 51 |
| 3 | HubSpot | 88 |
| 4 | Semrush | 47 |
| 5 | Clay | 92 |
| 6 | Salesforce | 94 |
| 7 | Claude Code | 99 |
| 8 | AirOps | 41 |
| 9 | Grok Bot | 73 |
| 10 |  Customer.io | 39 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click discussion held a broad plateau from March through July, then weakened in August and September; the last 30 days show a 9% recovery. The recurring question is what earns attention without a forced conversion. October adds scrutiny of LinkedIn link penalties and gated-content incentives, alongside Wil Reynolds’s argument that AI recommendations depend on accumulated brand authority.
Posts to understand this · as of Oct 18
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | Ahrefs | 51 |
| 3 | HubSpot | 88 |
| 4 | Semrush | 47 |
| 5 | Clay | 92 |
| 6 | Claude Code | 99 |
| 7 | Salesforce | 94 |
| 8 | AirOps | 41 |
| 9 | Lovable | 60 |
| 10 | Customer.io | 39 |
The people, tools and operating model behind custom go-to-market systems.
GTM Engineering rose through May, then lost share each month through September; the last 30 days remain down 2.1%. No single post explains the decline: Clay’s CLI, internal tools and $115 million round kept supplying concrete examples, but even that sequence did not sustain the spring share of conversation.
Posts to understand this · as of Oct 22
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | HubSpot | 88 |
| 4 | Codex | 85 |
| 5 | Instantly | 64 |
| 6 | Prospeo | 53 |
| 7 | Salesforce | 94 |
| 8 |  FullEnrich | 44 |
| 9 | AI Ark | 47 |
| 10 | n8n | 59 |
How software exposes its data and actions so agents can use it directly.
Headless and agent interfaces jumped in April and May, then held a higher baseline through September despite a gradual retreat. Cloudflare’s monetization gateway, Notion’s developer tools and Templafy’s MCP illustrate recurring product activity rather than one defining event; the latest 15% decline over 30 days shows that activity has not sustained the earlier share.
Posts to understand this
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Clay | 92 |
| 5 | Codex | 85 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Grok Bot | 73 |
| 8 | Instantly | 64 |
| 9 | Lovable | 60 |
| 10 | n8n | 59 |
How teams use buyer signals to decide who to target, when and why.
Signal-based sales and ABM declined from 7.1% in March to 4% in August, recovered some ground in September, and is up 23.5% over the last 30 days. The posts connect April’s agent-built outbound workflows with Zoom’s October emphasis on conversation intelligence and deal context. That recurring focus on turning signals into action offers context for renewed interest, but no single post establishes its cause.
Posts to understand this · as of Oct 19
 inPlatform recognitionZoom reports Revenue Accelerator’s Strong Performer recognition in Forrester’s revenue orchestration evaluationML
 inOutbound workflowMichel Lieben outlines Claude Code prospecting, account scoring, and buying-signal workflowsHD
 inAgent coordinationHans Dekker describes shared-context agents for outbound, social signals, and automation
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 64 |
| 6 | n8n | 59 |
| 7 | AI Ark | 47 |
| 8 | Codex | 85 |
| 9 | HeyReach | 53 |
| 10 | Attio | 51 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Open versus closed models climbed sharply in June and July, with July posts supplying two concrete hooks: Nvidia’s support for open models and Together AI’s Kimi K3 cost comparison against Claude Fable 5. Share then declined through September and is down 18.9% over the last 30 days, despite Mistral Large 4’s October preview.
Posts to understand this
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 85 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | OpenRouter | 52 |
| 5 | Grok Bot | 73 |
| 6 |  Together AI | 35 |
| 7 | Vercel | 61 |
| 8 | ElevenLabs | 56 |
| 9 | Salesforce | 94 |
| 10 | Baseten | 45 |
How companies prove AI delivers enough value to move beyond a pilot.
AI ROI held around 7% to 8% from April through July before dropping in August and September; the last 30 days show a modest 6.9% recovery. The posts give that persistent conversation concrete substance: OpenAI’s token price cuts, task-based model choices, and Decagon’s guidance on independent agent operation. They show cost and execution questions, without a single event that explains the decline or recovery.
Posts to understand this · as of Oct 19
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Codex | 85 |
| 4 | Clay | 92 |
| 5 | Grok Bot | 73 |
| 6 | HubSpot | 88 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Nooks | 47 |
| 9 | OpenRouter | 52 |
| 10 | Vercel | 61 |
How large companies move AI from small pilots into secure, useful production work.
Enterprise adoption conversation eased from 7.3% in April to 4.6% in September, while the last 30 days are nearly flat at 1.3% growth. The posts offer a pattern rather than one cause: Vanta’s AI growth story and outbound teams’ use of AI alongside talent give way to a detailed account of process mapping, data access and ownership work before deployment.
Posts to understand this · as of Oct 18
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 92 |
| 4 | Grok Bot | 73 |
| 5 | HubSpot | 88 |
| 6 | Nooks | 47 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Midjourney | 35 |
| 9 | Vercel | 61 |
| 10 | Zapier | 55 |
How teams create, distribute and judge marketing content made with AI.
AI Content stayed near 4–5% of conversation from March through September, with an August bump that the posts do not explain. Profound’s $180 million raise and Higgsfield’s ChatGPT plugin show continued investment in production and distribution, while Jason Widup describes teams overwhelmed by AI output. The latest 7.7% decline fits a persistent debate about capacity and quality, without a single clear trigger.
Posts to understand this
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 39 |
| 2 | Runway | 37 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 73 |
| 5 | Clay | 92 |
| 6 | HubSpot | 88 |
| 7 |  HeyGen | 34 |
| 8 | Lovable | 60 |
| 9 | Apify | 52 |
| 10 | ElevenLabs | 56 |
How companies keep agents secure, accountable and under control as they take on real work.
Agent governance climbed from March through July, then lost share through September; the last 30 days show a 15.6% recovery. The evidence points to a recurring control problem rather than one event: Anthropic documented compromised eval integrity, Databricks packaged routing and cost controls, and LangChain’s Vivek Trivedy explained how to check whether agents actually finish tasks correctly.
Posts to understand this · as of Oct 19
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 85 |
| 3 | Salesforce | 94 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | HubSpot | 88 |
| 6 | Vercel | 61 |
| 7 | Grok Bot | 73 |
| 8 | OpenRouter | 52 |
| 9 | Clay | 92 |
| 10 | ElevenLabs | 56 |
How AI changes what software companies build, charge for and deliver.
Conversation share peaked in May, when ElevenLabs cut self-serve prices, then declined each completed month through September; the last 30 days are down another 8.2%. The posts show several business-model arguments rather than one sustained catalyst: cheaper AI services, Salesforce’s rebuttal to the SaaS collapse narrative, and Noble’s focus on delivering manual work through software before scaling.
Posts to understand this · as of Oct 20
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 92 |
| 3 | HubSpot | 88 |
| 4 | Vercel | 61 |
| 5 | Claude Code | 99 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Gong | 64 |
| 8 | Nooks | 47 |
| 9 | ZoomInfo | 51 |
| 10 | Lovable | 60 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal Agents more than doubled their share from August to September, and the latest 30 days are up 115.4%. The posts show a shift from individual experiments, like Brian Halligan’s Hal, toward shared infrastructure: Meta and Sierra announced Personal Agent Protocol, while Stripe hosted a discussion of agents replacing web forms. That broader commercial scope gives the rise fresh material.
Posts to understand this
 XShared standardMeta and Sierra announce a standard for personal agents interacting with businessesS
 inCommerce discussionStripe hosts Zuckerberg and Wang for a discussion including agentic commerceBH
 inPersonal deploymentBrian Halligan’s Hal handles email, projects and participation in Zoom meetings
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 73 |
| 2 | Claude Code | 99 |
| 3 | Codex | 85 |
| 4 | HubSpot | 88 |
| 5 | OpenClaw | 49 |
| 6 | Salesforce | 94 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Vercel | 61 |
| 9 | Clay | 92 |
| 10 | Granola | 52 |
How companies build trust and stand out when AI makes content cheap and abundant.
Brand & Authenticity held a broad conversation share through summer before a September drop; the latest 30 days are down 13.6%. The posts show a recurring concern rather than one launch: Handley challenged authenticity policing, Clay published an AI writing policy, and Herubel advocated visual frameworks and sales follow-ups as responses to crowded feeds.
Posts to understand this · as of Oct 21
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 94 |
| 5 | Codex | 85 |
| 6 | Lovable | 60 |
| 7 | Vercel | 61 |
| 8 | Customer.io | 39 |
| 9 |  Optimizely | 32 |
| 10 | Substack | 52 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
Human experience held near 2.4–2.5% through the summer before a September drop; the last 30 days show a 7.8% recovery, still below the longer-term level. The pattern is a recurring argument for identifiable people behind marketing, rather than one launch. Wispr Flow’s founder content and Chris Donnelly’s account of winning Bugatti and Aston Martin give that argument concrete examples.
Posts to understand this · as of Oct 22
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 88 |
| 4 | Lovable | 60 |
| 5 | Claude Code | 99 |
| 6 | Nooks | 47 |
| 7 | Customer.io | 39 |
| 8 | HeyReach | 53 |
| 9 | Instantly | 64 |
| 10 | Optimizely | 32 |
How AI changes software pricing, usage costs and gross margins.
Conversation share climbed through June, then declined through September; the last 30 days are down another 14%. No single post explains the retreat: OpenAI’s token price cuts, Peter Walker’s account of model competition, and Factory’s routing savings show a sustained cost-efficiency story even as the topic takes a smaller share of conversation.
Posts to understand this
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Codex | 85 |
| 3 | Clay | 92 |
| 4 | Vercel | 61 |
| 5 | Claude Code | 99 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | HubSpot | 88 |
| 8 | Grok Bot | 73 |
| 9 | OpenRouter | 52 |
| 10 | Gong | 64 |
How people and agents share work, hand off tasks and make decisions together.
Multi-player AI settled into a July-to-September plateau below its May high, even as Grok Bot entered beta and Notion added sub-agent handoffs. Those releases share a concrete theme: agents use tools, take delegated work and return results. They did not produce another visible surge, and conversation share is down 19.3% over the last 30 days.
Posts to understand this
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Attio | 51 |
| 6 | Codex | 85 |
| 7 | Grok Bot | 73 |
| 8 | Instantly | 64 |
| 9 | Gong | 64 |
| 10 | Cursor (Anysphere) | 78 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR conversation fell steadily from March through July, briefly recovered in August, then settled lower in September. The L30 measure is essentially flat at negative 0.3%, despite fresh product proof from ElevenLabs’ inbound voice agent and Clay’s October launch of an agent that builds campaigns and learns from results.
Posts to understand this · as of Oct 16
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 88 |
| 5 | Vercel | 61 |
| 6 | Grok Bot | 73 |
| 7 |  Sumble | 34 |
| 8 | ElevenLabs | 56 |
| 9 | Instantly | 64 |
| 10 | Lovable | 60 |
Growth driven by people using the product before they talk to sales.
PLG’s share fell from 3.05% in March to 1.21% in July, then held near 1.4% in August and September. The last 30 days rose 19.4%, though the 90-day move remains negative. Clay’s combined product-led and sales-led approach, Metronome’s self-serve launch, and PostHog’s free plan illustrate the themes, but these posts do not establish what drove the recent gain.
Posts to understand this · as of Oct 22
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 92 |
| 4 | Lovable | 60 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Replit | 56 |
| 7 | Ahrefs | 51 |
| 8 | Claude Code | 99 |
| 9 |  Primer | 30 |
| 10 | Codex | 85 |
How teams track and control the cost of models, tokens and agent work.
Token spend and cost controls rose from March through July, then lost share in August and September; the last 30 days are down 15.1%. The posts describe a recurring cost problem rather than a single catalyst for the rise: greater token use, model tradeoffs, and margin pressure. Rippling’s spend console and the reported Harvey margin squeeze kept that problem concrete during the retreat.
Posts to understand this · as of Oct 20
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 85 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Grok Bot | 73 |
| 4 | Claude Code | 99 |
| 5 | Clay | 92 |
| 6 | OpenRouter | 52 |
| 7 | HubSpot | 88 |
| 8 | Vercel | 61 |
| 9 | Baseten | 45 |
| 10 | ElevenLabs | 56 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context engineering rose steadily through June, alongside posts about harness engineering and shared intelligence layers for revenue teams. It then declined each full month through September and is down 9.8% over the last 30 days. The evidence moves from broad system design toward a concrete Clay workflow example, but does not establish a single cause for the retreat.
Posts to understand this · as of Oct 22
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | Codex | 85 |
| 4 | Grok Bot | 73 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | HubSpot | 88 |
| 7 | Salesforce | 94 |
| 8 | ZoomInfo | 51 |
| 9 |  Octave | 31 |
| 10 | Apify | 52 |
Low-quality AI content and the fight to make automated work worth reading.
AI slop held close to 2% of conversation from April through August before dropping in September; the last 30 days are nearly flat, down 0.8%. The posts show a recurring frustration rather than one trigger: generic output, pressure to prove human authorship, and repeated prompting that still produces mediocre drafts. Tahnee Perry's Claude guide turns that complaint toward workflow setup.
Posts to understand this · as of Oct 19
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 73 |
| 3 | Codex | 85 |
| 4 | HubSpot | 88 |
| 5 | Apify | 52 |
| 6 | Clay | 92 |
| 7 | Instantly | 64 |
| 8 | Substack | 52 |
| 9 | Webflow | 48 |
| 10 | Customer.io | 39 |
The argument that agents and custom software will break the classic SaaS model.
SaaSpocalypse lost roughly half its share between March and August, then held nearly flat in September; the last 30 days are down another 15.3%. The available posts show a rebuttal phase: Benioff cited Salesforce’s revenue growth and low attrition, Salesforce called the thesis a myth, and Dave Kellogg recast it as a SaaS renaissance.
Posts to understand this · as of Oct 18
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 92 |
| 3 | HubSpot | 88 |
| 4 | Vercel | 61 |
| 5 | Gong | 64 |
| 6 | Nooks | 47 |
| 7 | ZoomInfo | 51 |
| 8 | Apify | 52 |
| 9 | Claude Code | 99 |
| 10 | Cursor (Anysphere) | 78 |
The choice between building software internally and buying another product.
Build vs. Buy lost share through July, then held roughly level in August and September; the latest 30 days are down 28.7%. The posts move from Vercel’s broad claim that companies buy less software to Replit’s concrete example of a salesperson building tools. Intercom’s renewed help desk investment supplies the counterweight: internal builds and purchased workflows still coexist.
Posts to understand this
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 92 |
| 4 | Vercel | 61 |
| 5 | Apify | 52 |
| 6 |  Monaco | 26 |
| 7 | Profound | 52 |
| 8 | ZoomInfo | 51 |
| 9 | Cursor (Anysphere) | 78 |
| 10 |  Momentum | 25 |
Ways to verify whether digital content or online activity came from a person or AI.
August's spike lines up with Anthropic's watermarking FAQ and Eli Schwartz's response to SEO concerns about it. Share fell sharply in September and is nearly flat over the last 30 days, down 1.8%, despite a 104.2% gain over 90 days. Sitecore's later post shifts the discussion toward preserving content credentials within publishing workflows.
Posts to understand this · as of Oct 19
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 85 |
| 2 | Grok Bot | 73 |
| 3 | Claude Code | 99 |
| 4 | HeyGen | 34 |
| 5 | Instantly | 64 |
| 6 | Apify | 52 |
| 7 | Granola | 52 |
| 8 | Higgsfield | 39 |
| 9 | HubSpot | 88 |
| 10 | Replit | 56 |
AI tools that write, edit, test and operate software alongside a human builder.
Coding agents lost share from March through July, briefly recovered in August, then slipped again in September; the last 30 days are down 15.1%. The evidence spans ColdIQ’s ad operations and Notion’s workspace-as-code beta, alongside Tyler Denk’s costly custom software experience. Practical applications coexist with maintenance costs, without one event that explains the decline.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 85 |
| 3 | Grok Bot | 73 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 92 |
| 6 | HubSpot | 88 |
| 7 | Lovable | 60 |
| 8 | Replit | 56 |
| 9 | Salesforce | 94 |
| 10 | OpenClaw | 49 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO held near its May high through July before losing share in August and September; the last 30 days show a 9.5% recovery. The posts offer no single explanation for that arc, but show a practical debate over citation evidence, SEO fundamentals and attribution, with Ethan Smith’s reported ChatGPT tracking bug adding a fresh measurement problem.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | Ahrefs | 51 |
| 3 | Semrush | 47 |
| 4 | HubSpot | 88 |
| 5 | Clay | 92 |
| 6 | Claude Code | 99 |
| 7 | Salesforce | 94 |
| 8 | AirOps | 41 |
| 9 | Customer.io | 39 |
| 10 | Lovable | 60 |
The frontier models and labs that provide the base layer for AI products.
Foundation models show repeated bursts: April’s jump, a June–July climb, an August dip, and a September rebound. Anthropic’s Glasswing announcement, Sonnet 5’s June launch and August pricing decision, and OpenAI’s reported OpenRouter spending high supply recurring news hooks rather than one sustained catalyst. The last 30 days are down 33.7%, despite a positive 90-day move.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 85 |
| 3 | Grok Bot | 73 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Midjourney | 35 |
| 6 | Salesforce | 94 |
| 7 | HubSpot | 88 |
| 8 | OpenRouter | 52 |
| 9 | Vercel | 61 |
| 10 | OpenClaw | 49 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP nearly doubled its share from March to May, with Salesforce’s Agent Fabric pitch placing agent discovery, cost controls and governance in the spring conversation. Later ElevenLabs and Databox releases supplied specific uses, but share settled below May’s high and is down 10% over the last 30 days: continued product delivery without renewed acceleration.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Codex | 85 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Clay | 92 |
| 7 | Grok Bot | 73 |
| 8 | Instantly | 64 |
| 9 | Lovable | 60 |
| 10 | n8n | 59 |
Measuring whether AI answers mention, cite and recommend a brand.
AI Visibility climbed to a June high, held near that level through August, then dropped in September; the last 30 days are up 23.4%. No single event explains that rebound: the posts show a recurring tension between demand to shape AI brand descriptions and doubts that prompt tracking reliably measures or improves visibility.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | Semrush | 47 |
| 3 | AirOps | 41 |
| 4 | Ahrefs | 51 |
| 5 |  Similarweb | 34 |
| 6 | Vercel | 61 |
| 7 | Peec AI | 28 |
| 8 | Clay | 92 |
| 9 | Grok Bot | 73 |
| 10 | HubSpot | 88 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
Enterprise AI’s April high coincided with Mistral’s Workflows preview, backed by named users including ASML and ABANCA. Share declined through September and is now roughly flat over the last 30 days, down 0.3%; the recurring thread is the work between model capability and business value, from reliable production processes to trusted data and adoption.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 92 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Grok Bot | 73 |
| 6 | HubSpot | 88 |
| 7 | Nooks | 47 |
| 8 | Zapier | 55 |
| 9 |  6sense | 42 |
| 10 | Gong | 64 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid media recovered gradually from its April low, held above 2% from May onward and stepped higher in August before a September dip. The last 30 days are up 23.1%, with Anthropic’s search for a growth lead across performance marketing, lifecycle and SEO providing the clearest current signal.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Clay | 92 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 64 |
| 6 | Codex | 85 |
| 7 | Gong | 64 |
| 8 | Lovable | 60 |
| 9 | RB2B | 47 |
| 10 | Primer | 30 |
Email sent to people with no prior relationship to start a sales conversation.
Cold email peaked in May, when Jason Bay reported a jump from roughly 1% replies through a sequencer to 15%+ positive replies from his inbox. Share settled near 3.2–3.4% from July through September and is down 16% over the last 30 days. The recurring thread is practical troubleshooting: delivery, relevance and giving someone a reason to reply.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Claude Code | 99 |
| 3 | Instantly | 64 |
| 4 | HubSpot | 88 |
| 5 | Smartlead | 47 |
| 6 | Prospeo | 53 |
| 7 | Codex | 85 |
| 8 | Grok Bot | 73 |
| 9 | Salesforce | 94 |
| 10 | Lemlist | 49 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps declined from March through August, then held nearly flat in September; the last 30 days show a further 3.8% dip. No single event explains the slide, but the posts move from Apollo’s Pocus acquisition and stack friction toward concrete operating choices. The lower plateau still carries debate about software maintenance, CRM automation and account signals.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 92 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Gong | 64 |
| 6 | n8n | 59 |
| 7 | Instantly | 64 |
| 8 | Nooks | 47 |
| 9 | Codex | 85 |
| 10 | Grok Bot | 73 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer success lost share from March through July, briefly recovered in August, then fell again in September; the last 30 days are down 7.1%. No single event explains the slide. The posts put automation promises beside uneven customer outcomes: Rox launched renewal agents, Eddie Reynolds described unanswered Salesforce support requests, and Higgsfield reported expansion from a $99 subscription to a $6 million annual contract.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 92 |
| 4 | Lovable | 60 |
| 5 | Gong | 64 |
| 6 | Claude Code | 99 |
| 7 | Vercel | 61 |
| 8 | Attio | 51 |
| 9 | Grok Bot | 73 |
| 10 | Replit | 56 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Prospecting climbed through May around a run of automation launches, from Nooks AI Sequencing in February to Salesforce’s ZoomInfo-powered prospecting agent in April. Share then declined, briefly held level in July and August, and fell again in September. Clay’s API and CLI launch extended the agent workflow story, but the last 30 days remain down 17.3%.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | AI Ark | 47 |
| 5 | Instantly | 64 |
| 6 | Salesforce | 94 |
| 7 | HeyReach | 53 |
| 8 | Prospeo | 53 |
| 9 | Apollo.io | 51 |
| 10 |  Findymail | 43 |
Voice and chat software that talks with buyers and customers.
Conversation share rose from 1.46% in March to 2.04% in August, stayed near 2% in September, and is up 30.2% over the last 30 days. Recent examples focus on real-time voice agents: OpenAI’s September API release, followed by October launches from ElevenLabs and Mistral.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 73 |
| 2 | HubSpot | 88 |
| 3 | ElevenLabs | 56 |
| 4 | Salesforce | 94 |
| 5 | Clay | 92 |
| 6 | Docket | 32 |
| 7 | Vector | 36 |
| 8 | Claude Code | 99 |
| 9 | Attio | 51 |
| 10 | Cursor (Anysphere) | 78 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold outbound’s share fell in April, rebounded in May, then declined each month through September; the last 30 days show a modest 2.8% lift. The posts span Nooks expanding into sequencing, Origami automating lead generation, and Jaleh Rezaei sharing why buyers dismiss cold calls, showing both automation launches and practical call advice within a shrinking conversation.
Posts to understand this · as of Oct 22
 inOutbound sequencingNooks launches AI Sequencing for list building, account research, and emailsJR
 inBuyer attentionJaleh Rezaei shares Kyle Norton’s approach to overcoming automatic cold-call dismissalFM
 inLead generationOrigami launches AI lead generation with prompting, list feedback, and messaging
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Instantly | 64 |
| 5 | Salesforce | 94 |
| 6 | Prospeo | 53 |
| 7 |  BetterContact | 43 |
| 8 | HeyReach | 53 |
| 9 | Lemlist | 49 |
| 10 | Findymail | 43 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand Generation’s share roughly halved between March and September, with an August bounce that did not hold; the last 30 days are down another 3.9%. No single event explains the decline. The posts share a practical concern: AI changes how buyers find information, while Inflection.io and Webflow Campaigns address limits in marketing platforms and campaign production.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 92 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Codex | 85 |
| 6 | Gong | 64 |
| 7 | Docket | 32 |
| 8 | Primer | 30 |
| 9 | Smartlead | 47 |
| 10 | ZoomInfo | 51 |
The work of connecting marketing activity to pipeline and revenue.
Attribution settled near 1.5% share in August and September, then gained 53.8% over the last 30 days. The evidence points to a recurring measurement problem rather than a launch: n8n’s AI discovery case and October’s zero-click discussion expose what last-touch reports miss, while Adam Holmgren argues for connecting buyer engagement to later pipeline.
Posts to understand this · as of Oct 22
 inMeasurement argumentAdam Holmgren argues attribution should connect buyer engagement with later pipelineES
 inAttribution examplen8n case study uses self-reported discovery to address last-touch blind spotsSS
 inBuyer behaviorSara Stella Lattanzio explains discovery and shortlisting without website visits
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 92 |
| 4 | Gong | 64 |
| 5 | Docket | 32 |
| 6 | Claude Code | 99 |
| 7 | Grok Bot | 73 |
| 8 | Instantly | 64 |
| 9 | Semrush | 47 |
| 10 | Similarweb | 34 |
Sales and marketing coordinating around a defined set of target accounts.
ABM fell from March’s level, settled near 1.8% in August and September, and is up 33% over the last 30 days. Vector’s September launch gives the renewed discussion a concrete focus: contact-level activity, actionable account scores, ads, and deal attribution. Clay’s earlier ads beta reflects the same push to connect buyer signals with campaign execution.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | 6sense | 42 |
| 6 | Instantly | 64 |
| 7 | Nooks | 47 |
| 8 | AI Ark | 47 |
| 9 | Findymail | 43 |
| 10 | FullEnrich | 44 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Data enrichment lost share from March through September, apart from a May bounce; the last 30 days show a 10.9% recovery. Clay’s March data price cuts and October’s Gong Enrich launch frame a shift toward enrichment inside broader GTM workflows. Gong’s earlier RightBound acquisition supplies background to that pattern, rather than an explanation for this period’s decline.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 64 |
| 5 | Prospeo | 53 |
| 6 | n8n | 59 |
| 7 | AI Ark | 47 |
| 8 | HeyReach | 53 |
| 9 | RB2B | 47 |
| 10 | BetterContact | 43 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
AI video jumped in August and held that higher share in September, alongside fal’s live generation launch and HeyGen’s research on business owners’ reluctance to publish video. That plateau spans both technical capability and a practical customer problem. Higgsfield’s OpenAI marketplace entry adds a purchasing route, though the last 30 days are down 9.1%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 39 |
| 2 | Runway | 37 |
| 3 | HeyGen | 34 |
| 4 | Claude Code | 99 |
| 5 | Grok Bot | 73 |
| 6 | ElevenLabs | 56 |
| 7 | Replit | 56 |
| 8 | HubSpot | 88 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Lovable | 60 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Evals climbed into July, then held near 2.1% in August and September; the last 30 days are up 33.2%. That plateau matters because the evidence spans several recurring uses: Vercel’s regression checks, Sierra’s competitive voice leaderboard, and a geographic model probe. No single launch explains the curve; testing serves both practical reliability and public model comparisons.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 85 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 94 |
| 5 | OpenRouter | 52 |
| 6 | Grok Bot | 73 |
| 7 | Devin | 38 |
| 8 | Vercel | 61 |
| 9 |  Cline | 30 |
| 10 | ElevenLabs | 56 |
Mapping and winning the committee of people involved in a business purchase.
Buying groups lost share through summer and barely moved in September; a 32.8% last-30-day rebound still leaves the 90-day move down 21.5%. No single launch explains the turn. The recurring thread is practical deal work: Clay’s executive outreach, Gal Aga’s emphasis on internal consensus, and October advice to map champions, skeptics, and decision influencers.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 92 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Vector | 36 |
| 6 | HeyReach | 53 |
| 7 | Instantly | 64 |
| 8 | Nooks | 47 |
| 9 | 6sense | 42 |
| 10 | AI Ark | 47 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability climbed to a May high, then fluctuated below it; no single post explains that spike. The recurring pattern is infrastructure investment alongside skepticism about how deliverability gets sold, from Infobip’s SocketLabs acquisition to criticism of fear-based pitches. Resend’s Forge launch adds a concrete announcement as share rises 10.3% over the last 30 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Instantly | 64 |
| 4 | Claude Code | 99 |
| 5 | Prospeo | 53 |
| 6 | Smartlead | 47 |
| 7 | AI Ark | 47 |
| 8 | Lemlist | 49 |
| 9 | n8n | 59 |
| 10 | Salesforce | 94 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
GTM Data Infrastructure nearly regained its March share in June, then declined through September and another 11.1% over the last 30 days. March’s evidence pairs Pocus joining Apollo with a Databricks report on unified data architecture. The later Mobi Solutions acquisition brings the discussion down to implementation and cleanup, but the posts do not explain June’s bounce.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 92 |
| 4 | Claude Code | 99 |
| 5 | n8n | 59 |
| 6 | Nooks | 47 |
| 7 | Gong | 64 |
| 8 | Instantly | 64 |
| 9 |  GrowthLoop | 29 |
| 10 | 6sense | 42 |
Programmable tools used to build custom go-to-market systems, agents and automations.
The climb from March to May coincided with shared Claude skills and examples of Claude Code connecting GTM tools. Share then declined through August before a modest September recovery; the last 30 days are up 5.5%. October’s full-stack GTM engineering playbook extends the same practical pattern: reusable systems for research, enrichment, outreach, and CRM updates.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Prospeo | 53 |
| 2 | Clay | 92 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 88 |
| 5 | Instantly | 64 |
| 6 | FullEnrich | 44 |
| 7 | AI Ark | 47 |
| 8 | Findymail | 43 |
| 9 | BetterContact | 43 |
| 10 | HeyReach | 53 |
People asking AI assistants for answers instead of using a traditional search engine.
AI search conversation climbed to a June high, then declined through September and remains down 3.4% over the last 30 days. The posts trace a debate from AutoRFP’s reported ChatGPT lead gains to AI citations surviving Google de-indexing and concerns about lost organic clicks. That gives the curve a recurring discovery-and-measurement theme, without a single documented catalyst.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 47 |
| 2 | Clay | 92 |
| 3 | Salesforce | 94 |
| 4 | Profound | 52 |
| 5 | Ahrefs | 51 |
| 6 | 6sense | 42 |
| 7 | Claude Code | 99 |
| 8 | Exa.ai | 48 |
| 9 | Gamma | 45 |
| 10 | Gong | 64 |
The choice of go-to-market motion and the plan for making it work.
GTM strategy returned to its March level in May, then broadly lost share through September; the last 30 days are nearly flat at +1.9%. No single event explains the curve. The continuing thread is how AI changes the motion itself: Swan AI’s agent-run pipeline, Notion’s builder-led account ownership, and questions about selling to buyers who delegate decisions to agents.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Nooks | 47 |
| 5 | Gong | 64 |
| 6 | AI Ark | 47 |
| 7 | Findymail | 43 |
| 8 | Apollo.io | 51 |
| 9 | BetterContact | 43 |
| 10 | Codex | 85 |
The debate over AI risk, alignment, regulation and responsible development.
September broke a relatively steady baseline as Microsoft’s superintelligence principles, discussion of a reported Replit database incident, and Databricks’ skepticism about existential risk put different safety questions into circulation. This was a cluster of debates, not one announcement. Conversation share is down 22.9% over the last 30 days, but remains up 90.7% over 90 days.
Posts to understand this
 XLeadership principleMicrosoft shares Satya Nadella’s humanity-centered principle for superintelligence developmentSN
 inOperational riskSteve Nouri cites a reported Replit database incident to promote governanceD
 inRisk counterpointDatabricks CEO Ali Ghodsi describes current existential risk as near zero
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 85 |
| 2 | Claude Code | 99 |
| 3 | beehiiv | 51 |
| 4 | Grok Bot | 73 |
| 5 | Midjourney | 35 |
| 6 | Runway | 37 |
| 7 | Attio | 51 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | ElevenLabs | 56 |
| 10 | Granola | 52 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise sales lost share from March through September, with brief rebounds along the way; the last 30 days are up 15.3%. No single event explains that turn. The posts keep returning to practical deal execution: Clay’s million-dollar sellers, roles that span sales and renewals, and the technical, business and procurement wins needed to close.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Clay | 92 |
| 4 | HubSpot | 88 |
| 5 | Gong | 64 |
| 6 | 6sense | 42 |
| 7 | Profound | 52 |
| 8 | 1mind | 39 |
| 9 |  Clarify | 29 |
| 10 | ElevenLabs | 56 |
The training, fine-tuning and modeling work underneath AI products.
Machine Learning rose steadily from June through September and remains up 2.5% over the last 30 days, with a 28.6% gain over 90 days. The evidence spans several sources of attention: Skild AI’s one-example robot model, World Labs’ announcement that it would join AMD, and Meta’s training infrastructure. That breadth fits a sustained rise better than a single launch spike.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 85 |
| 3 | Grok Bot | 73 |
| 4 | Baseten | 45 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Cline | 30 |
| 7 | HubSpot | 88 |
| 8 | Midjourney | 35 |
| 9 | OpenRouter | 52 |
| 10 | LangChain | 46 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence slid from March through June, rebounded in July, then eased across August and September. The L30 measure is nearly flat at positive 1.4%, which makes the current level more of a plateau than a recovery; conversation analysis now appears inside broader revenue orchestration, coaching, and custom RevOps workflows.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 88 |
| 4 | Clay | 92 |
| 5 | Claude Code | 99 |
| 6 | Vercel | 61 |
| 7 | Zapier | 55 |
| 8 | n8n | 59 |
| 9 | Grok Bot | 73 |
| 10 | 6sense | 42 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product marketing’s share fell from 3.5% in March to 1.3% in September and is down another 19% over the last 30 days. No single event explains the decline; the posts show a debate over who owns the work, with Profound and Google introducing marketing engineers while Sjeel K. defends PMM’s role in launches, messaging, and sales readiness.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 94 |
| 5 | Gong | 64 |
| 6 | Codex | 85 |
| 7 |  Ploy | 30 |
| 8 | Primer | 30 |
| 9 | FullEnrich | 44 |
| 10 | Lovable | 60 |
How companies create demand, build trust and reach buyers at other businesses.
B2B marketing’s modest June lift gave way to lower share through September; a 16.2% gain over the last 30 days sits within a 35.9% decline over 90 days. No single launch explains that shape. The recurring debate is where trust and distribution come from, with posts advocating owned audiences, creator partnerships and employee voices beyond the founder.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 92 |
| 4 | Claude Code | 99 |
| 5 | Customer.io | 39 |
| 6 | Optimizely | 32 |
| 7 | Gong | 64 |
| 8 | Primer | 30 |
| 9 | Ahrefs | 51 |
| 10 | Profound | 52 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search strategy nearly doubled from April to June, then declined through September; the last 30 days remain down 6.1%. The posts show a shift in emphasis rather than a single catalyst: Ryan Law’s AI-native content workflow, scrutiny of citation metrics, and Austin Armstrong’s combined SEO and AEO plan. The common problem is how to connect discovery work to useful outcomes.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 47 |
| 2 | Claude Code | 99 |
| 3 | Ahrefs | 51 |
| 4 | AirOps | 41 |
| 5 | Codex | 85 |
| 6 | HubSpot | 88 |
| 7 | Similarweb | 34 |
| 8 | Customer.io | 39 |
| 9 |  Demandbase | 33 |
| 10 | FullEnrich | 44 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Revenue Agents reached their high in April around launches such as Fin’s sales role, then fell steeply through August. A small September lift did not hold, with the latest 30 days down 7.5%. The evidence shifted from broad agent claims toward harder operating questions: Ami stresses outbound fundamentals, while performance systems ask which tools move KPIs.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | Nooks | 47 |
| 5 | HubSpot | 88 |
| 6 | Sumble | 34 |
| 7 |  Attention | 28 |
| 8 |  Clearskies | 24 |
| 9 | Codex | 85 |
| 10 |  Rox | 31 |
How companies sell to other companies and how business buyers make decisions.
B2B sales is up 40.1% over the last 30 days after September’s low, but remains down over 90 days. The recurring thread is buyer friction: Maja Voje credits research-led outreach, Aligned raised $60 million around shared deal workspaces, and Morgan J Ingram describes renewed demand for face-to-face contact as generic AI outreach wears thin.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | HubSpot | 88 |
| 5 | 6sense | 42 |
| 6 |  DemandScience | 27 |
| 7 | Hermes Agent | 35 |
| 8 | OpenClaw | 49 |
| 9 | Primer | 30 |
| 10 | Ahrefs | 51 |
B2B brands paying creators and independent voices to reach trusted audiences.
Conversation share has seesawed since March, with June and August highs followed by a September dip. The latest 30 days are up 77.7%, while the 90-day move is just 2.5%, pointing to a recent rebound. The evidence spans Demandbase hiring for influencer marketing, Limelight reporting $3 million paid to B2B creators, and an October account of six-figure creator earnings.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | ElevenLabs | 56 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Primer | 30 |
| 6 | FullEnrich | 44 |
| 7 | Gamma | 45 |
| 8 | Lovable | 60 |
| 9 | Ploy | 30 |
| 10 | Prospeo | 53 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales leadership reached its highest share in April and May, with Replit’s Ghazi Masood arguing that leaders must recruit, coach, prospect and close. Attention dropped sharply in June and softened through September, though the last 30 days are up 10.4%. The continuing thread is talent development: spotting potential early and keeping reps long enough to build expertise.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Gong | 64 |
| 3 | Clay | 92 |
| 4 | HubSpot | 88 |
| 5 | Claude Code | 99 |
| 6 | Codex | 85 |
| 7 | Attio | 51 |
| 8 | ElevenLabs | 56 |
| 9 | Grok Bot | 73 |
| 10 | TitanX | 34 |
The durable knowledge and memory an agent can use across tasks and sessions.
Agent memory and context climbed through June, then faded into a lower August-September plateau; the last 30 days are up 16%. The evidence shifts from Kieran Flanagan’s personal Claude Code and Obsidian system to organizational context: ZoomInfo’s Workbounce acquisition and an argument for warehouse-backed agents. That gives the recent pickup a concrete enterprise focus, though it remains below the earlier high.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 88 |
| 4 | ZoomInfo | 51 |
| 5 | Claude Code | 99 |
| 6 | Grok Bot | 73 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Clearskies | 24 |
| 9 | Gong | 64 |
| 10 | Octave | 31 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth marketing dropped sharply after March and has stayed below 1% since June, with essentially flat share over 90 days and a 3% decline over the last 30. No single event explains the lower plateau. The durable conversation is about experiment economics: Clay reported cheaper acquisition, Anthropic described internal growth automation, and Andrew Yan argued for experiment volume over hit rate.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | HubSpot | 88 |
| 4 | Primer | 30 |
| 5 | Codex | 85 |
| 6 | Grok Bot | 73 |
| 7 | Ploy | 30 |
| 8 | Salesforce | 94 |
| 9 | Ahrefs | 51 |
| 10 | Customer.io | 39 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement declined through August and September before a 52.7% last-30-day rebound; it remains down 24.5% over 90 days. The posts point to a recurring demand for coaching that changes behavior, rather than one event behind the turn. Vanta’s Hyperbound results and an October account of habits retained for 18 months make that demand concrete.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 |  Highspot | 29 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Clay | 92 |
| 6 | Customer.io | 39 |
| 7 |  Seismic | 29 |
| 8 | Apollo.io | 51 |
| 9 | Instantly | 64 |
| 10 |  Mutiny | 31 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing’s share peaked in May, briefly rebounded in August, then fell sharply in September; the rolling 30-day change is down 15.9%. June posts pushed cohesive strategy and connected workflows, while September’s critique of posting quotas carries that thread forward: build around one validated idea, then distribute it across formats.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 47 |
| 2 | Claude Code | 99 |
| 3 | Clay | 92 |
| 4 | Customer.io | 39 |
| 5 | HubSpot | 88 |
| 6 | Ahrefs | 51 |
| 7 | Codex | 85 |
| 8 | Grok Bot | 73 |
| 9 | Optimizely | 32 |
| 10 | AirOps | 41 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Executive and employee social held near 0.9–1% through summer, dropped in September, and is up 50.7% over the last 30 days. The 90-day decline of 26.4% keeps that rebound in perspective. October posts share a practical focus on making executive content repeatable: Wispr Flow’s founder approach, agency writer accountability, and a construction CEO’s LinkedIn and YouTube results.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HeyReach | 53 |
| 3 | Instantly | 64 |
| 4 | Apify | 52 |
| 5 | HubSpot | 88 |
| 6 |  Chili Piper | 36 |
| 7 | Claude Code | 99 |
| 8 | Grok Bot | 73 |
| 9 | Lovable | 60 |
| 10 | Optimizely | 32 |
Scoring leads and accounts to decide who deserves attention first.
Lead Scoring declined from May through September before a 26.8% lift over the latest 30 days, still down 41.5% over 90 days. The recent posts frame scoring as part of an operating workflow: Fivos Aresti describes narrowing roughly 66,000 companies to 5,700 accounts, while others connect prioritization to daily actions and changing account conditions. Practical execution is the common thread.
Posts to understand this
 XAccount filteringFivos Aresti describes narrowing roughly 66,000 companies to 5,700 target accountsSC
 inSeller workflowStevie Case recommends account scoring and daily next action prioritizationMD
 inDynamic targetingMaxence de Villepion argues account changes should determine downstream sales plays
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 92 |
| 3 | Salesforce | 94 |
| 4 | Instantly | 64 |
| 5 | Claude Code | 99 |
| 6 | Gong | 64 |
| 7 | HeyReach | 53 |
| 8 | Prospeo | 53 |
| 9 | RB2B | 47 |
| 10 | Lemlist | 49 |
Starting and running a business, including the economics and experience of the founder path.
Entrepreneurship stayed within a fairly narrow band through June, dipped in July, then recovered in August before easing again. No single event drove the pattern: bootstrapped growth stories from Tally and Tenex, plus HubSpot Next’s YouSpot for one-person companies, sustained the conversation, while the L30 measure is now down 33.5%.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Smartlead | 47 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 51 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | HeyReach | 53 |
| 8 | Instantly | 64 |
| 9 | Zapier | 55 |
| 10 | 6sense | 42 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting reached its highest share in May, after Rox’s Autopilot launch and HockeyStack’s $50 million announcement put revenue agents into the conversation, though neither establishes the cause of that high. Share softened through late summer and is down 28.8% over 30 days; October’s revenue-platform shortlist reflects continued category coverage without evidence of a fresh catalyst.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 92 |
| 4 | Gong | 64 |
| 5 | n8n | 59 |
| 6 | Claude Code | 99 |
| 7 |  Clari | 32 |
| 8 |  Fireflies | 39 |
| 9 | Instantly | 64 |
| 10 | Intercom | 43 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent Skills rose to a May high on applied proof such as $300K per month in ad spend managed through Claude Code, then declined through September. Vercel’s August open standard drew attention but did not reverse the broader slide. The L30 is down only 4.0%, which points to a lower plateau as skills settle into practical workflows such as OKR review.
Posts to understand this · as of Oct 15
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | Codex | 85 |
| 4 | HubSpot | 88 |
| 5 | Salesforce | 94 |
| 6 | Nooks | 47 |
| 7 | Apify | 52 |
| 8 | Attio | 51 |
| 9 | Clarify | 29 |
| 10 | Customer.io | 39 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Forward deployed engineering peaked in May and declined through September, with a 38.7% recovery over the last 30 days. The evidence supports a recurring debate over the model, not an adoption surge: May Habib questioned customer dependence on engineers, Brian Halligan challenged the relabeling of services, and Dave Kellogg shared a critique from former Palantir FDE leaders.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Braze | 36 |
| 3 | Claude Code | 99 |
| 4 | Nooks | 47 |
| 5 | Clay | 92 |
| 6 | Codex | 85 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Gong | 64 |
| 9 | AirOps | 41 |
| 10 |  Consensus | 27 |
The point where a product solves a real need for a market that will buy it.
Product-market fit declined from April to July, then settled into a lower August–September range; the last 30 days are up 21.1%. No single event explains the renewed attention. The recurring argument is that fit needs more frequent validation: Lenny Rachitsky’s Lovable takeaways describe a three-month cycle, while ClickUp’s September hackathon post compresses that to weeks.
Posts to understand this · as of Oct 22
 inGrowth lessonsLenny Rachitsky shares Elena Verna’s lessons on repeatedly earning AI product-market fitC
 inProduct developmentClickUp’s Cabo hackathon post describes product-market fit refreshing every few weeksAC
 inFunding assumptionsAndrew Chen questions software validation assumptions for hardware, robotics, and deeptech
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Gamma | 45 |
| 4 | Lovable | 60 |
| 5 | Profound | 52 |
| 6 | Ahrefs | 51 |
| 7 | Attio | 51 |
| 8 | Claude Code | 99 |
| 9 | Granola | 52 |
| 10 | Replit | 56 |
A go-to-market operating model where agents execute work across the revenue motion.
Agentic GTM has an uneven curve rather than a steady climb, but August’s recovery held much of its ground in September and the latest 30 days are up 17.3%. The posts connect team redesign and limited hands-off adoption with a concrete investment: Clay’s $115 million Series D and stated ambition to build a self-learning revenue engine.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Attio | 51 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 88 |
| 5 | Salesforce | 94 |
| 6 | 6sense | 42 |
| 7 | Apollo.io | 51 |
| 8 | Codex | 85 |
| 9 | Instantly | 64 |
| 10 | RB2B | 47 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Share stepped up from 0.47% in July to 0.70% in August, then held near that level through September and the partial October reading. The posts span partner-led pipeline, formal agency programs, and AI-assisted affiliate operations; the last 30 days slipped 4%, pointing to a mild recent cooling.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Instantly | 64 |
| 5 | Gong | 64 |
| 6 | HeyReach | 53 |
| 7 | Lovable | 60 |
| 8 | Webflow | 48 |
| 9 | Claude Code | 99 |
| 10 | Grok Bot | 73 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce has a clear conference-shaped curve: an August buildup, a September spike, and a 76.7% decline over the last 30 days. Informatica’s debut as part of Salesforce and Crossbeam’s AgentExchange launch partnership supplied concrete September news, while debate over conference ROI broadened the conversation. The retreat fits attention concentrated around the event.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | ZoomInfo | 51 |
| 4 | Clay | 92 |
| 5 | Apify | 52 |
| 6 | Codex | 85 |
| 7 | Claude Code | 99 |
| 8 |  Lightfield | 27 |
| 9 | Octave | 31 |
| 10 | Primer | 30 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting climbed steadily into June, when Unify repositioned beyond basic email copy and Corey Haines argued that weak offers, not wording, often cause poor conversion. It then declined through September. The latest 30 days are up 23.2%, with early October evidence returning to concrete craft through Anyword’s AIDA, PAS and baseline comparison.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Clay | 92 |
| 4 | Instantly | 64 |
| 5 | n8n | 59 |
| 6 | AI Ark | 47 |
| 7 | Smartlead | 47 |
| 8 | Codex | 85 |
| 9 | Customer.io | 39 |
| 10 | Gong | 64 |
The software stack marketers use to plan, run, measure and improve their work.
Martech held a steady March-to-May baseline before losing share, with only a brief August rebound; the latest 30 days are down 21.1%. No single event explains the decline. The recurring debate is stack architecture: Scott Brinker’s Databricks report questions more layers, Joe Chernov warns agents can recreate bloat, and Gradial’s Dreamforce session returns to the collapsing stack.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Braze | 36 |
| 4 | GrowthLoop | 29 |
| 5 | Docket | 32 |
| 6 |  Salesloft | 40 |
| 7 |  allGood | 19 |
| 8 | Hightouch | 32 |
| 9 |  Hootsuite | 21 |
| 10 |  Influ2 | 26 |
How marketing teams use AI, where it helps and how it changes the job.
AI in Marketing fell from March to May, then settled into a lower band with a modest August-to-September recovery; the last 30 days are down 15.6%. The recurring thread is how teams organize the work: Google’s marketing-engineer hire, Andy Mowat’s move to Inflection.io and criticism of unchanged processes after AI pilots keep the discussion grounded in roles and systems.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | ElevenLabs | 56 |
| 5 | Granola | 52 |
| 6 | Grok Bot | 73 |
| 7 | Lovable | 60 |
| 8 | Midjourney | 35 |
| 9 | Profound | 52 |
| 10 | Salesloft | 40 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing Operations lost share from March through July, briefly recovered in August, then fell again in September; the latest 30 days show an 18.6% lift. No single event explains that long decline, but the posts expose a recurring tension: Conversion promises agent-led campaign execution, Nvidia seeks operations leadership, and Jon Miller challenges the old marketing automation playbook.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 92 |
| 3 | Salesforce | 94 |
| 4 |  Conversion | 28 |
| 5 | Salesloft | 40 |
| 6 | allGood | 19 |
| 7 | Claude Code | 99 |
| 8 | Docket | 32 |
| 9 | Grok Bot | 73 |
| 10 | Gong | 64 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing automation declined through June, then recovered steadily through September; share is up 42.8% over the last 30 days. The posts show a broader discussion of what workflows should do: HubSpot launched Agent Hub and Agent Builder, Jev illustrated ad-analysis tasks, and Tom Fishburne challenged automated funnels that ignore customer intent. That mix supports a recurring conversation beyond one launch.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Braze | 36 |
| 4 | Conversion | 28 |
| 5 | Clay | 92 |
| 6 | Grok Bot | 73 |
| 7 | n8n | 59 |
| 8 |  ActiveCampaign | 32 |
| 9 | Apollo.io | 51 |
| 10 | Claude Code | 99 |
AI agents that discover, compare and buy products on a person's behalf.
After an uneven summer, Agents as Buyers recovered in September and is up 23.4% over the last 30 days. The evidence spans checkout infrastructure and retailer use: Shopify announced a Muse partnership for agentic checkout with Shop Pay, while JD Sports and Lampenwelt described AI product discovery. October commentary adds the marketing question: how do brands sell to agents?
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 |  Browserbase | 33 |
| 3 | Exa.ai | 48 |
| 4 | Vercel | 61 |
| 5 | 1mind | 39 |
| 6 | Claude Code | 99 |
| 7 | Grok Bot | 73 |
| 8 | Substack | 52 |
| 9 | Ahrefs | 51 |
| 10 | AirOps | 41 |
AI agents that create, launch, buy and optimize advertising.
AI-driven advertising rose from April through August, held near that level in September, and is up another 62.5% over the last 30 days. The evidence points to a widening set of practical uses rather than one launch: solo operators running ads, Higgsfield creative for Netflix Latin America, and Roadway agents that handle campaign setup and optimization.
Posts to understand this · as of Oct 22
 inOperating modelJonathan Metrick describes experts using agents to run one-person marketing teamsAM
 inCampaign exampleVertex CGI uses Higgsfield for Netflix Latin America’s Moria campaignEK
 inProduct demonstrationEmily Kramer describes Roadway agents handling campaign setup and proactive optimization
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Lovable | 60 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 73 |
| 5 | Salesforce | 94 |
| 6 | Clay | 92 |
| 7 | Codex | 85 |
| 8 | Granola | 52 |
| 9 | Similarweb | 34 |
| 10 |  Tealium | 20 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
The May high came amid concrete pricing changes, including monday.com’s credit launch and April shifts at Clay, Anthropic, and ServiceNow. Share settled onto a lower band from July through September and is down 19.9% over the last 30 days. AiSDR’s October beta adds another example, but the curve shows less conversation despite continued experimentation.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Gong | 64 |
| 3 | Replit | 56 |
| 4 | Clay | 92 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | HubSpot | 88 |
| 7 | Lovable | 60 |
| 8 | Vercel | 61 |
| 9 | OpenRouter | 52 |
| 10 | Supabase | 49 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Sales development lost share each month from May through September, but the last 30 days show a 47.6% rebound. No single event explains the turn; the posts trace a debate over the function’s design, from failed AI SDR replacements and broader seller responsibilities to October’s Clay and Notion discussion of signals, automation and pipeline per rep.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 92 |
| 4 | Gong | 64 |
| 5 | HubSpot | 88 |
| 6 |  Outreach | 45 |
| 7 |  Unify | 30 |
| 8 | FullEnrich | 44 |
| 9 | Salesloft | 40 |
| 10 | ZoomInfo | 51 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
After a March peak and an uneven summer, conversation dipped in September and is now up 37.4% over the last 30 days. Recent posts pair a call for face-to-face selling amid AI outreach fatigue with practical discussion of measuring event pipeline influence and building relationships through small dinners.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Lovable | 60 |
| 3 | Clay | 92 |
| 4 | HubSpot | 88 |
| 5 | Ahrefs | 51 |
| 6 | Apify | 52 |
| 7 | Customer.io | 39 |
| 8 | Gong | 64 |
| 9 | HeyReach | 53 |
| 10 | Primer | 30 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
The April high and strong May share coincide with arguments for rebuilding company processes and hiring CMOs who automate work themselves. June through August held a lower, steady level before September softened; attention is down another 29.4% over the last 30 days, with October’s discussion focused on the unresolved work of skills development and career paths.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | HubSpot | 88 |
| 3 | Granola | 52 |
| 4 | Lovable | 60 |
| 5 | Clay | 92 |
| 6 | Codex | 85 |
| 7 | ElevenLabs | 56 |
| 8 | Salesforce | 94 |
| 9 | Vercel | 61 |
| 10 | beehiiv | 51 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales Ops reached its highest monthly share in May, then broadly declined; the last 30 days are down another 14%. No single event in these posts explains the slide: the recurring debate is whether quotas and compensation match reality, from Collin Cadmus's quota critique to revenue-based SDR commissions and seven-figure earners at private companies.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 92 |
| 4 | Codex | 85 |
| 5 | Vercel | 61 |
| 6 | n8n | 59 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Gong | 64 |
| 9 | HubSpot | 88 |
| 10 | Zapier | 55 |
Websites and docs structured so AI crawlers and agents can read and use them.
After a relatively steady April through June, attention settled into a lower July through September plateau; the last 30 days now show a 36.6% rebound. The recurring question is which site changes actually pay off: Webflow’s earlier conversion claims and May’s dispute over Google’s guidance now meet October interest in agent optimization tactics and proof of ROI.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | Ahrefs | 51 |
| 3 | Gamma | 45 |
| 4 | Semrush | 47 |
| 5 | Vercel | 61 |
| 6 | Claude Code | 99 |
| 7 | Codex | 85 |
| 8 | Grok Bot | 73 |
| 9 | HubSpot | 88 |
| 10 | Peec AI | 28 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Salesforce’s Headless 360 launch anchors April’s spike: Salesforce, Agentforce and Slack became accessible through APIs, MCP and CLI. Share faded through July, recovered through September, and is now down 28% over the last 30 days. October’s discussion tests the promise against specifics, including quoting inside Claude and Matthew Volm’s account of Revenue Cloud dropping its Agentforce name.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 92 |
| 4 | Claude Code | 99 |
| 5 | Apify | 52 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Firecrawl | 40 |
| 8 | Replit | 56 |
| 9 | ZoomInfo | 51 |
| 10 | Braze | 36 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing rose sharply through summer and held near 1.1% share in August and September, before a 34.3% decline over the last 30 days. Cognition’s Devin Fusion cost claim and OpenRouter’s Stripe announcement give the expansion concrete anchors; September commentary on Harvey’s reported margin squeeze kept model economics in view, though these posts do not explain the recent decline.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Grok Bot | 73 |
| 3 | OpenRouter | 52 |
| 4 | Salesforce | 94 |
| 5 | HubSpot | 88 |
| 6 | Lovable | 60 |
| 7 | Midjourney | 35 |
| 8 | Nooks | 47 |
| 9 | Profound | 52 |
| 10 | Airtable | 48 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
The rise from March to July tracks a concrete sequence: Claude Code playbooks in May, then Clay’s CLI and API launch alongside working outbound examples in July. Share eased in August and September, and the last 30 days are down 45.1%; the September discussion had shifted toward how Clay fits inside Claude Code, Codex and Cursor workflows.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | Codex | 85 |
| 4 | HubSpot | 88 |
| 5 | Salesforce | 94 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Instantly | 64 |
| 8 | n8n | 59 |
| 9 | AI Ark | 47 |
| 10 | Exa.ai | 48 |
The work of earning awareness, trust and preference for a company over time.
Brand building stayed near 1% of conversation through June, then weakened unevenly before September’s sharp drop; the latest 33.6% decline extends that direction. No single event explains the fall. The posts expose a recurring budget problem: Fin celebrates awareness gains, while Peep Laja and Ramp’s attribution example show why those gains can struggle to earn financial credit.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Optimizely | 32 |
| 2 | Salesforce | 94 |
| 3 | Customer.io | 39 |
| 4 | HubSpot | 88 |
| 5 | Semrush | 47 |
| 6 | Supabase | 49 |
| 7 | Vercel | 61 |
| 8 | 6sense | 42 |
| 9 | Ahrefs | 51 |
| 10 | Braze | 36 |
Teams building internal software with AI instead of buying another SaaS product.
Conversation share peaked in April, fell sharply through June, then stayed below spring levels through September. The last 30 days are up 7%, while the last 90 remain down 12%. The debate pits savings from replacing SaaS with custom workflows against maintenance costs and engineers’ time away from the core product.
Posts to understand this · as of Oct 20
 inMaintenance costsTeams cancelling SaaS inherit maintenance, security, support, and opportunity costsE
 inEngineering tradeoffBuilding internal replacements takes engineers away from the core productJD
 inSavings caseProposes replacing major SaaS tools with purchased building blocks and custom workflows
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 92 |
| 4 | Vercel | 61 |
| 5 | Monaco | 26 |
| 6 | Apify | 52 |
| 7 | Clarify | 29 |
| 8 | Claude Code | 99 |
| 9 | ElevenLabs | 56 |
| 10 |  Klaviyo | 39 |
Deciding what to build, why it matters and which product bets come first.
Product strategy settled into an August–September plateau after spring swings; its share is now up 9.6% over the last 30 days. The posts point to a recurring question about what companies actually sell, rather than one shared catalyst. Mycroft narrowed its offer to CMMC certification, while Automation Anywhere’s agreement to acquire boost.ai extends its bet into customer-facing conversational and voice AI.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 92 |
| 4 | Claude Code | 99 |
| 5 | Vercel | 61 |
| 6 | ElevenLabs | 56 |
| 7 | OpenRouter | 52 |
| 8 | Substack | 52 |
| 9 |  11x | 24 |
| 10 | 1mind | 39 |
Systems where several agents divide a job, coordinate their work and combine the result.
Multi-agent systems peaked in May and lost share each full month through September; the last 30 days are down 18.5%. The evidence shows concrete deployments and deals throughout that slide, rather than a single setback. Workato’s Airo expansion, Mercor’s 100-plus-subagent run and ZoomInfo’s DoubleO.ai acquisition center the discussion on workflow execution and reliability.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Clay | 92 |
| 4 | Grok Bot | 73 |
| 5 | HubSpot | 88 |
| 6 | n8n | 59 |
| 7 | Instantly | 64 |
| 8 | AI Ark | 47 |
| 9 | Codex | 85 |
| 10 | Cursor (Anysphere) | 78 |
Tracing and monitoring what a model or agent did during a production run.
Observability held a steady base through July, gained share in August and September, and is up 42.9% over the last 30 days. The evidence points to a recurring product and purchasing need rather than one breakout event: Intercom launched controls for Fin, Cloudflare unified its AI control plane, and CrewAI encountered enterprise resistance to buying observability separately.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Codex | 85 |
| 4 | Clay | 92 |
| 5 | Salesforce | 94 |
| 6 | Vercel | 61 |
| 7 | Attention | 28 |
| 8 | Browserbase | 33 |
| 9 | Clarify | 29 |
| 10 | Clearskies | 24 |
Multi-step work planned and executed by agents instead of fixed automation rules.
Agentic workflows rebounded in September after a slide from May through August, and attention is up 35.1% over the last 30 days. October’s posts add concrete fuel: Clay introduced its global agent at Sculpt, while Aurasell reported 70 new logos and a $10M annual run rate with four reps supported by 67 agents. They support the current momentum without explaining September’s initial rebound.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 92 |
| 3 | 6sense | 42 |
| 4 | Claude Code | 99 |
| 5 | Demandbase | 33 |
| 6 | Gong | 64 |
| 7 | Grok Bot | 73 |
| 8 | Instantly | 64 |
| 9 | Nooks | 47 |
| 10 | Salesloft | 40 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI Security stayed in a roughly 0.5–0.6% share band from March through August, then fell to 0.34% in September; the last 30 days are down another 1.6%. September posts address agent objectives and access controls, while October’s authorization experiment exposes a concrete permission failure. These show continuing security gaps, but do not establish what sustained the earlier band or caused the decline.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Midjourney | 35 |
| 3 | Codex | 85 |
| 4 | Grok Bot | 73 |
| 5 | Salesforce | 94 |
| 6 | Vercel | 61 |
| 7 | Attio | 51 |
| 8 |  E2B | 21 |
| 9 | ElevenLabs | 56 |
| 10 | Firecrawl | 40 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-serve fell sharply from March to May, recovered into a July-August plateau, then softened in September; the last 30 days are up just 3.8%. The summer posts capture competing directions: Metronome opened self-serve access, while Elena Verna used the reported Airtable deal to question enterprise-first priorities. More recently, 1up’s pitch centers on shorter buyer waits rather than a broader adoption surge.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 92 |
| 4 | Replit | 56 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Lovable | 60 |
| 7 | Vercel | 61 |
| 8 | Ahrefs | 51 |
| 9 | Apollo.io | 51 |
| 10 | Gamma | 45 |
Approval and review steps that keep a person involved in an agent's work.
Human in the Loop rebounded in August, fell in September, and is now nearly flat, up 2.7% over the latest 30 days. The meaningful pattern is specificity: Healey discusses autonomy and accountability, Brinker separates review by expertise and time, and Tenex packages permissions, approvals, and audit trails into its agent launch.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | HubSpot | 88 |
| 4 | Instantly | 64 |
| 5 | Salesforce | 94 |
| 6 | Apollo.io | 51 |
| 7 | Attio | 51 |
| 8 | HeyReach | 53 |
| 9 | Nooks | 47 |
| 10 | Outreach | 45 |
A shared revenue knowledge layer that people and agents can query and update.
GTM Brain jumped in June and held a higher range through September; the posts point to repeated examples of shared context, rather than one identifiable trigger. Swan AI described 120-plus agents fed by its GTM brain, while ZoomInfo showed Uber’s account context in one record. The latest 30 days are down 14.7%, so those concrete examples now sit alongside softer attention.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Apify | 52 |
| 3 | Codex | 85 |
| 4 | HubSpot | 88 |
| 5 | ZoomInfo | 51 |
| 6 | Clay | 92 |
| 7 | Fireflies | 39 |
| 8 | Instantly | 64 |
| 9 | Prospeo | 53 |
| 10 | Attio | 51 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound systems peaked in May and lost share each completed month through September, with another 31.6% decline over the last 30 days. August's gtmskills.com expansion and Xbow's use of Rox did not interrupt that slide. The posts show competing approaches, from complete agent workflows to Tsuki Matcha's manual café visits, without a single event that explains the decline.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Attio | 51 |
| 4 | Instantly | 64 |
| 5 | Smartlead | 47 |
| 6 |  Deepline | 35 |
| 7 | Salesforce | 94 |
| 8 | TitanX | 34 |
| 9 | 6sense | 42 |
| 10 | AI Ark | 47 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Content at scale peaked in May, declined through summer and barely moved in September; the last 30 days show a further 34.7% drop. No single event explains the retreat: Higgsfield and Figma offer more production capabilities, while Eli Schwartz warns about AI spam, so the posts pair faster output with questions about its consequences.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Apify | 52 |
| 2 | Ahrefs | 51 |
| 3 | AirOps | 41 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 48 |
| 6 | Lovable | 60 |
| 7 | Substack | 52 |
| 8 | n8n | 59 |
| 9 | Airtable | 48 |
| 10 | Apollo.io | 51 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales Tech's June bounce gave way to three months of decline, with share down another 24.2% over the last 30 days. No single event explains the slide; the posts move from Europe's expanding tool landscape and Airscale's data APIs to a concrete complaint about AI dialers. Josh Braun wanted context about Oracle layoffs, not just more calls.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 92 |
| 3 | Gong | 64 |
| 4 | Common Room | 35 |
| 5 | Apify | 52 |
| 6 | Apollo.io | 51 |
| 7 | Attention | 28 |
| 8 |  Aurasell | 17 |
| 9 |  Backstory | 19 |
| 10 | Braze | 36 |
Founders running early sales themselves before handing the motion to a sales team.
Founder-led sales rebounded sharply from May’s low to July’s high, alongside free access to Founding Sales and a warning about premature sales delegation. Share eased through September, but the last 30 days are nearly flat at minus 1%. The continuing thread is how long founders should keep selling, with Rippling’s event recap arguing that AI administration support extends that runway.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 |  Passionfroot | 22 |
| 4 | Ploy | 30 |
| 5 | Primer | 30 |
| 6 | Sumble | 34 |
| 7 | HubSpot | 88 |
| 8 | Salesforce | 94 |
| 9 | 6sense | 42 |
| 10 | Codex | 85 |
The runtime around an agent that provides tools, state, controls and stopping rules.
Agent Harnesses shows repeated bursts rather than a sustained climb, with June’s high unexplained by the supplied posts. DeepSeek’s August developer preview coincides with the next rebound, while Anthropic’s engineering account and Greg Isenberg’s explainer show the broader pattern of implementation stories and category education. Share is down 19.4% over the latest 30 days, but only 2.5% over 90.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Codex | 85 |
| 4 | Clay | 92 |
| 5 |  GitHub Copilot | 35 |
| 6 | Hermes Agent | 35 |
| 7 |  Kiro | 24 |
| 8 | LangChain | 46 |
| 9 | OpenRouter | 52 |
| 10 | Salesforce | 94 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
May’s high coincided with Gong reporting more than $500 million ARR and citing customer consolidation as a growth driver. Conversation then contracted, with share down 51.1% over 90 days and 15.6% over 30 days. ZoomInfo’s point-tool drop data and Apollo’s complete AI GTM system keep the theme concrete, but have not sustained spring’s conversation share.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 92 |
| 3 | Gong | 64 |
| 4 | HubSpot | 88 |
| 5 | Claude Code | 99 |
| 6 | Common Room | 35 |
| 7 |  Fathom | 32 |
| 8 | Nooks | 47 |
| 9 | Clari | 32 |
| 10 | Clarify | 29 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
AI Employees peaked in May, but the supplied posts do not explain that spike. Later evidence made the category concrete: Viktor reported a $20 million annualized revenue run rate and expanded to Teams, while Company Brain offered an open-source Slack employee. Those examples did not sustain May’s attention, and share is down 20% over the latest 30 days.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 |  Viktor | 33 |
| 4 | Granola | 52 |
| 5 | Salesforce | 94 |
| 6 | Attio | 51 |
| 7 | Grok Bot | 73 |
| 8 | Primer | 30 |
| 9 | beehiiv | 51 |
| 10 | Ahrefs | 51 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
AI sameness spiked in April and faded each month through September; the latest 94.1% bounce still sits within a 39.2% decline over 90 days. The posts suggest a shift from criticism toward practical fixes: Santiago Faus calls out formulaic ChatGPT posts, while Diandra Escobar offers a Claude skill with explicit rules and examples for LinkedIn hooks.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Codex | 85 |
| 4 | Substack | 52 |
| 5 | Apify | 52 |
| 6 | Clay | 92 |
| 7 | Customer.io | 39 |
| 8 | Exa.ai | 48 |
| 9 |  Grammarly | 28 |
| 10 | Optimizely | 32 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium hit a July trough, then rebounded across August and September as the posts tied free access to distinct business models. OpenAI framed ads as support for ChatGPT’s free tier, while PostHog made its 97% free-customer base a proof point; the L30 move is now down 33%, so that late-summer lift is not carrying into the current window.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Codex | 85 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Lovable | 60 |
| 5 | Ahrefs | 51 |
| 6 | Clay | 92 |
| 7 | Grok Bot | 73 |
| 8 | HubSpot | 88 |
| 9 | Replit | 56 |
| 10 | Attio | 51 |
Time-limited access that lets a buyer test a product before paying.
Free Trial is up 85.5% over the last 30 days, but remains down 29.5% over 90 days after a weaker August and September. The evidence points to recurring conversion friction, rather than one breakout event: MillionVerifier flags disposable signups, Stripe addresses token theft and trial abuse, and Sam Kuehnle describes attribution rules that delayed sales follow-up.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Gong | 64 |
| 4 | Ahrefs | 51 |
| 5 | Clay | 92 |
| 6 | Lovable | 60 |
| 7 |  AthenaHQ | 20 |
| 8 | Attio | 51 |
| 9 |  Calendly | 39 |
| 10 | Canva | 50 |
Using AI to tailor outreach and marketing to each person at scale.
AI personalization’s spring high gave way to a steady decline through September, with another 20.3% drop over the last 30 days. The posts show a consistent critique rather than one triggering event: Kyle Asay narrows account lists with AI, Nick Palasz distinguishes relevance from observations, and John Barrows favors researched substance over formulaic outreach.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Salesforce | 94 |
| 3 | Braze | 36 |
| 4 | Claude Code | 99 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | HubSpot | 88 |
| 7 | Klaviyo | 39 |
| 8 | Outreach | 45 |
| 9 | beehiiv | 51 |
| 10 | 11x | 24 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
AI-native GTM spiked in May, then lost ground unevenly through September; share is down another 9.6% over the last 30 days. Replit’s May example gave the discussion a concrete operating model: build workflows, retain core software, and hire salespeople. Justin Norris’s October move into Zendesk’s GTM AI leadership adds a dedicated role to that pattern, without establishing a broader rebound.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Lovable | 60 |
| 4 | Nooks | 47 |
| 5 | Profound | 52 |
| 6 | Rox | 31 |
| 7 | Salesforce | 94 |
| 8 | Substack | 52 |
| 9 | Sumble | 34 |
| 10 | Vector | 36 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
Conversation share peaked in May, fell through August, and is recovering: up 34.8% over the last 30 days, though still down 29.4% over 90 days. October discussion spans Gupta’s comments on Braze and stack integration, Miro’s experiments with synthetic customers for campaign testing, and Optimove’s addition of Messenger to existing customer journeys.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | Gong | 64 |
| 5 | GrowthLoop | 29 |
| 6 | beehiiv | 51 |
| 7 | Apollo.io | 51 |
| 8 | Braze | 36 |
| 9 |  Centralize | 26 |
| 10 | Customer.io | 39 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise marketing conversation rose through the summer, peaked in August, then fell in September; its share is down 22.7% over the last 30 days. Recent posts focus on concrete internal work: reducing approval and handoff overhead, tracking brand visibility in AI answers, and personalizing customer experiences at scale.
Posts to understand this
 inProcess frictionGradial’s incoming CMO describes briefs, approvals, and handoffs consuming marketing workGR
 inChannel measurementEasyVista tracks AI answer visibility with baselines, targets, and weekly reviewsETinCustomer personalizationDermalogica uses Klaviyo and Composer to support personalized customer experiences
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Aurasell | 17 |
| 4 | Clay | 92 |
| 5 | Grok Bot | 73 |
| 6 | Lightfield | 27 |
| 7 | Lovable | 60 |
| 8 | OpenRouter | 52 |
| 9 | Replit | 56 |
| 10 | AirOps | 41 |
Writing and structuring the instructions a model follows.
Prompt Engineering lost share through September despite a June bounce, but the latest 30 days show a modest 5.7% lift. The posts describe a consistent shift away from asking every employee to master prompts and toward context, harnesses and prepared workflows. Glean makes that shift concrete: it cut its system prompt by more than 45% after rebuilding its harness.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 92 |
| 3 | Salesforce | 94 |
| 4 | HubSpot | 88 |
| 5 | Zapier | 55 |
| 6 | Attio | 51 |
| 7 |  Breeze | 23 |
| 8 | Codex | 85 |
| 9 | Viktor | 33 |
| 10 | Apify | 52 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
HubSpot’s April rename from INBOUND to UNBOUND produced the first burst, followed by a lull and a much larger September conference spike. Partner Day and accounts of the event’s scale explain that September concentration. The last 30 days are down 67.1%, consistent with attention easing after the event rather than a sustained monthly climb.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Apify | 52 |
| 4 | Claude Code | 99 |
| 5 | Clay | 92 |
| 6 | Lightfield | 27 |
| 7 | ZoomInfo | 51 |
| 8 | Codex | 85 |
| 9 | Firecrawl | 40 |
| 10 | Grok Bot | 73 |
How sales teams use AI and how it changes the work of selling.
AI in sales held nearly steady in June–July before a sharp August–September contraction; the last 30 days are roughly flat, up 1.5%. The posts offer no single cause for the decline, but expose a recurring test: whether AI improves actual sales work. Cursor’s reported ChatGTM gains and Ami’s launch put concrete execution beside explicit criticism of AI SDR promises.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Mutiny | 31 |
| 2 |  CallRail | 23 |
| 3 | Clarify | 29 |
| 4 | Clay | 92 |
| 5 | Clearskies | 24 |
| 6 | Codex | 85 |
| 7 | Gong | 64 |
| 8 | Grok Bot | 73 |
| 9 | Klaviyo | 39 |
| 10 | Outreach | 45 |
The strategy of naming, defining and leading a new market.
Category creation’s share eased from March through July, recovered in August, then fell sharply in September. The last 30 days are down another 9.3%. The selected posts question the value of category names and AI’s effect on category building, while arguing that adoption depends on a clear customer job and people who spread the idea.
Posts to understand this · as of Oct 19
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Braze | 36 |
| 4 | Gong | 64 |
| 5 | Granola | 52 |
| 6 | Primer | 30 |
| 7 | Ahrefs | 51 |
| 8 |  AppsFlyer | 18 |
| 9 | Attio | 51 |
| 10 |  Bland | 19 |
How AI changes headcount, entry-level work and the jobs people still need to do.
Conversation share has contracted substantially since March, with a May rebound and a further 9.3% decline over the last 30 days. No single event in these posts explains the slide; the recurring tension is between lean-team revenue claims and evidence that human roles persist. OpenAI’s SDR hiring and Kyle Lacy’s account of marketers’ anxiety keep that tension concrete.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | Grok Bot | 73 |
| 3 | Vercel | 61 |
| 4 | 11x | 24 |
| 5 | 1mind | 39 |
| 6 | Claude Code | 99 |
| 7 | Conversion | 28 |
| 8 | Docket | 32 |
| 9 |  Framer | 32 |
| 10 | HubSpot | 88 |
AI-generated creators, avatars and user-style content used in marketing.
April's spike coincided with Avatar V's pitch: one short recording could support different outfits and settings without losing personal expressions. Share then faded through August before September's rebound, with the last 30 days up 64.7%. Recent HeyGen posts revisit the same obstacle from two angles: owners reluctant to publish videos and a marketer testing her own avatar.
Posts to understand this · as of Oct 20
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 73 |
| 2 | Instantly | 64 |
| 3 | Apify | 52 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 48 |
| 6 | Gamma | 45 |
| 7 | HeyGen | 34 |
| 8 | Higgsfield | 39 |
| 9 | HubSpot | 88 |
| 10 |  People Data Labs | 23 |
Advantages that grow stronger as more people, data or participants join a product.
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Clay | 92 |
| 4 | Codex | 85 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | ElevenLabs | 56 |
| 7 | Granola | 52 |
| 8 | Grok Bot | 73 |
| 9 | Replit | 56 |
| 10 | Vercel | 61 |
The online channel mix used to reach, convert and retain customers.
Digital Marketing’s share climbed from March to a June peak, then fell through September before rebounding 67% over the last 30 days. The selected posts show channel strategy spanning parallel traffic sources, product data for AI recommendations, and personalization across digital channels. That recent pickup follows a sustained decline, with share still down 47.6% over the last 90 days.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 47 |
| 2 | AI Ark | 47 |
| 3 | Ahrefs | 51 |
| 4 | Apollo.io | 51 |
| 5 | Chili Piper | 36 |
| 6 | Clay | 92 |
| 7 |  Default | 27 |
| 8 | Demandbase | 33 |
| 9 |  Freckle.io | 34 |
| 10 | HeyReach | 53 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
Outcome-Based Pricing rose through May, faded through August, then recovered some share in September; the last 30 days still show a 6% decline. The evidence moves from pricing announcements toward operating details: HubSpot introduced per-result agent charges, Salesforce agreed to acquire m3ter for flexible billing, and Intercom addressed spend forecasts. That pattern suggests practical follow-through after the spring attention.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 92 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | HubSpot | 88 |
| 5 | Intercom | 43 |
| 6 | Lovable | 60 |
| 7 |  Metronome | 25 |
| 8 |  UiPath | 26 |
| 9 | Vercel | 61 |
| 10 | 1mind | 39 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
Conversation share rose in April, dipped in May, then held near 0.6% from June through August before falling in September; the latest 30 days are down 55.2%. Zapier's September expansion in Claude and October's fal and LocalFalcon connectors show releases continuing across business tools, media generation, and local business tasks as conversation share falls.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Codex | 85 |
| 3 | Claude Code | 99 |
| 4 | HeyGen | 34 |
| 5 |  Lambda | 26 |
| 6 | Lovable | 60 |
| 7 | Replit | 56 |
| 8 | Salesforce | 94 |
| 9 | Semrush | 47 |
| 10 | Zapier | 55 |
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
Open Source AI spiked in July, then faded through September; none of the supplied posts identifies July’s trigger. Subsequent discussion spans infrastructure, cheaper usage and disputes over incumbent power, from the Larsen & Toubro-Vyoma partnership to Bolt Forge. That mix has not sustained the spike: the latest 30 days are down 24.8%, despite a positive 90-day comparison.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Cline | 30 |
| 2 | Cursor (Anysphere) | 78 |
| 3 |  Groq | 25 |
| 4 | Baseten | 45 |
| 5 | ElevenLabs | 56 |
| 6 |  Harmonic | 20 |
| 7 |  Manus | 30 |
| 8 | OpenRouter | 52 |
| 9 |  Parallel | 34 |
| 10 | Salesforce | 94 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
August’s sharp spike has a clear common thread: Anthropic’s watermarking FAQ, Synthesia’s marking update, and commentary on generation and detection tools all centered on transparency requirements. Share dropped back in September, which fits a concentrated compliance discussion rather than sustained expansion. The last 30 days are nearly flat at plus 1.5%, despite the much larger 90-day gain.
Posts to understand this
 XCompliance explanationAnthropic says watermarking implementation is intended to comply with EU rulesMR
 inIndustry commentaryMelissa Rosenthal examines companies that offer both AI generation and detectionS
 inProduct implementationSynthesia describes automatic machine-readable marking and C2PA credentials for relevant videos
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 85 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 73 |
| 4 | HeyGen | 34 |
| 5 | Granola | 52 |
| 6 | Runway | 37 |
| 7 | Vercel | 61 |
| 8 | Docket | 32 |
| 9 |  Ghost | 18 |
| 10 | Higgsfield | 39 |
Rule-based software that moves business work through predefined steps and systems.
Conversation share peaked in April, then generally declined through September; the latest 30 days are down 65%. These posts cover automating sales busywork, adding AI steps to connected workflows, and processing purchase orders. They show concrete uses for automation, but do not establish why its share of conversation fell.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | n8n | 59 |
| 5 | AI Ark | 47 |
| 6 | RB2B | 47 |
| 7 | Ahrefs | 51 |
| 8 | Airtable | 48 |
| 9 | Apify | 52 |
| 10 | Attio | 51 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory reached its high in April, when Matt Heinz argued that fractional CMOs could be permanent leadership for $5m–$50m B2B companies. Share settled lower through summer; the last 30 days are up 7.7%. The posts show a practical thread rather than one catalyst: senior judgment, packaged marketing plans, and HubSpot diagnosis before more ad spend.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | AirOps | 41 |
| 2 | Consensus | 27 |
| 3 | Gamma | 45 |
| 4 | Gong | 64 |
| 5 | HubSpot | 88 |
| 6 | Lovable | 60 |
| 7 | Profound | 52 |
| 8 | Salesforce | 94 |
| 9 | Webflow | 48 |
AI-native firms that sell finished work instead of software, delivered by agents and a small human team.
Services-as-software held roughly level in May and June before a sharp July drop, with the last 30 days down another 15.1%. The evidence shows a recurring investment thesis rather than one decisive catalyst: Emergence’s operating lessons, Daydream’s $15 million Series A, and September commentary about Sequoia. Those arguments persist, but conversation share remains well below spring levels.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 |  Crunchbase | 33 |
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
Share slid from March through August, apart from a small May lift, then rebounded in September before the L30 fell 43.1%. Polsia’s one-employee run-rate story supplied the May proof point; September revived the theme through Swan AI’s $10M ARR-per-employee goal and RB2B’s lean-company ranking, but that burst did not hold.
Posts to understand this · as of Oct 15
| Brand | GTM Index | |
|---|---|---|
| 1 | Lovable | 60 |
| 2 |  Base44 | 22 |
| 3 | Canva | 50 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Gamma | 45 |
| 6 |  Lusha | 29 |
| 7 | Replit | 56 |
| 8 |  Twilio | 43 |
| 9 | Vercel | 61 |
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing rose to a July high, then contracted through September before a 20.2% lift over the last 30 days. The renewed attention comes with criticism of token consumption: Sierra argues for outcome pricing, Databricks demonstrates budget controls, and Dennis Sevilla collects executives’ complaints about costs without results. That pattern suggests the debate has shifted toward value, rather than renewed enthusiasm for spending.
Posts to understand this · as of Oct 21
Software designed for agents to operate as the primary user.
Agents as users grew from almost nothing in June, dipped in September, and is now up 447.4% over the last 30 days from a small base. Concrete traffic reports and product responses give the jump context: Lorikeet launches agent detection, CHEQ reports a surge after consumer-agent launches, and Melissa Rosenthal examines why ad-supported businesses restrict agent access.
Posts to understand this · as of Oct 22
 inProduct launchLorikeet launches detection to identify and manage inbound AI agent trafficMRinAccess economicsMelissa Rosenthal connects agent restrictions with advertising economics at Amazon and CloudflareC
 inTraffic signalCHEQ reports a hundredfold agentic traffic surge after consumer AI agent launches
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 73 |
| 2 | Vercel | 61 |
| 3 | Attio | 51 |
| 4 | Claude Code | 99 |
| 5 | Midjourney | 35 |
| 6 | Ahrefs | 51 |
| 7 | Breeze | 23 |
| 8 | Canva | 50 |
| 9 |  Cartesia | 28 |
| 10 | Clay | 92 |
The argument over requiring a form before someone can access useful content.
Conversation share fell after March, briefly recovered in May, then slid through September. It is up 60.9% over the last 30 days, but remains down 39.8% over 90 days. September’s evidence questions blanket bans on gating; October’s posts criticize gated campaigns built to generate MQLs and argue that forms block content from AI search.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 92 |
| 2 | HubSpot | 88 |
| 3 | AI Ark | 47 |
| 4 | Apify | 52 |
| 5 |  BuiltWith | 32 |
| 6 |  Ocean.io | 38 |
| 7 | RB2B | 47 |
| 8 | Salesforce | 94 |
| 9 | ActiveCampaign | 32 |
| 10 | Ahrefs | 51 |
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent loops rose sharply into June and stayed near that level in July, when Palantir launched Agent Engine and Agent SDK and Salesforce connected loops to measurable business outcomes. Those posts give the summer plateau substance, though they do not explain June’s jump; subsequent monthly declines and a 51.7% drop over the last 30 days show attention has faded.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Attio | 51 |
| 3 | Claude Code | 99 |
| 4 | Clay | 92 |
| 5 | Codex | 85 |
| 6 | Deepline | 35 |
| 7 | HubSpot | 88 |
| 8 | OpenClaw | 49 |
Pushback against AI from customers, workers and the public, and brands repositioning as pro-human.
AI backlash moves in bursts rather than a sustained climb: May’s high coincides with Rand Fishkin’s consumer-versus-business adoption argument, while the posts do not explain August’s rebound. September’s billboard vandalism account adds a concrete example of public hostility, but attention is down 57% over the last 30 days and nearly flat over 90 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Primer | 30 |
| 2 | 11x | 24 |
| 3 | 1mind | 39 |
| 4 |  AiSDR | 20 |
| 5 | Apify | 52 |
| 6 | Braze | 36 |
| 7 | Claude Code | 99 |
| 8 | Clay | 92 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Docket | 32 |
Interfaces that let agents understand and operate software built for human users.
Agent interfaces saw a May spike, a June drop, and a July rebound before attention eased through September; the last 30 days are down 34.7%. The posts explain the summer thread better than May’s spike: multiple GTM vendors shipped interfaces agents can call, and Salesforce teased its Agentforce Experience Layer. Hightouch’s later AXO pitch extends that discussion into shopping, without a broad attention recovery.
Posts to understand this · as of Oct 18
| Brand | GTM Index | |
|---|---|---|
| 1 | Browserbase | 33 |
| 2 | Claude Code | 99 |
| 3 | Exa.ai | 48 |
| 4 | Resend | 30 |
| 5 | Salesforce | 94 |
| 6 |  StackAdapt | 22 |
| 7 | Vercel | 61 |
Brands use human authorship and craft as a reason to trust or value their work.
Human-made claims appear in bursts rather than a sustained climb, with May and August stronger than the months around them and the last 30 days down 27.1%. The recurring thread is human expertise alongside AI: Dave Gerhardt’s case for authenticity, a marketplace of human-crafted GTM skills, and Contentful’s human-made, agent-ready message. No single launch explains the uneven curve.
Posts to understand this · as of Oct 19
 inBrand applicationContentful discusses human-made, agent-ready experiences with Mercedes-Benz and Deloitte DigitalDG
 inAuthenticity argumentDave Gerhardt makes the case for human authorship and imperfect craft
| Brand | GTM Index | |
|---|---|---|
| 1 | Clearskies | 24 |
| 2 | Attention | 28 |
| 3 | Clarify | 29 |
| 4 | Clay | 92 |
| 5 | Nooks | 47 |
| 6 | Rox | 31 |
| 7 | Sumble | 34 |
| 8 | Claude Code | 99 |
| 9 | Codex | 85 |
| 10 | Baseten | 45 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
Trust-based marketing remains a small, uneven conversation: June and July strength gave way to an August dip and September recovery, with the last 30 days roughly flat at +2.2%. No single event drives the pattern. Across the posts, the recurring argument is that credibility must precede the ask, from Jon Miller’s critique of transactional marketing to Unbounce’s advice on proof and demo pages.
Posts to understand this · as of Oct 19
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
AI Detection’s July spike held through August, when posts debated LinkedIn’s new “seems like AI slop” feature and whether detection works on social posts. That controversy provides a concrete focus for the summer plateau, distinct from Semrush’s earlier search-ranking analysis; share dropped sharply in September and is down 64.8% over the latest 30 days.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Substack | 52 |
| 2 | Fathom | 32 |
| 3 | Grammarly | 28 |
| 4 | Lightfield | 27 |
| 5 | Replit | 56 |
Using product activity to identify, time and support sales opportunities.
Product-Led Sales remains tiny and episodic, with several zero months rather than a sustained curve. The latest 30 days are up 11.1% from a very low base, while the evidence points to a category absorbed by larger platforms: Pocus joined Apollo, and HubSpot supports enterprise product-usage signals through a broader data stack.
Posts to understand this · as of Oct 16
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
How model costs, services and agent work put pressure on software gross margins.
This is a sparse conversation, with a brief April high of 0.031% and zero-share months in May and July. The current L30 move is down 60%, and the evidence remains split between lower AI gross margins and a services model where smaller engagements can unlock a larger market.
Posts to understand this · as of Oct 9
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Claude Code’s share fell from 11.6% in March to 4.6% in September, while the last 30 days show a smaller 5% decline. The posts trace certification, frustration with the terminal, and a concrete outbound system built on Supabase and Attio. That mix shows continued practical use, but no single event explains the long slide.
Posts to understand this · as of Oct 21
Cursor is an AI code editor with agents that write, edit and review code.
Cursor’s share declined from March through July, rebounded in August, then fell in September; the L30 move is down 27.7%. August announcements covered SpaceX’s acquisition of Cursor closing and Vercel’s agent plugins collaboration with Cursor. A September post highlighted Nvidia’s use of Cursor, but the selected evidence does not establish what caused the August rebound.
Posts to understand this
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay’s share peaked in May, declined through September, and is now recovering: L30 is up 13.8%, though L90 remains down 23.2%. October posts cover Clay’s place in a growing GTM stack, Eric Nowoslawski’s return and the revenue-agent mission, and hands-on testing of the new agent. These show what people are discussing, without establishing what caused the rebound.
Posts to understand this · as of Oct 21
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n’s May–June surge coincided with its SAP partnership announcement, a concrete expansion into Joule Studio after Gamma’s April integration. Share then declined through September, but the last 30 days show a 16.9% recovery. Qdrant’s research-agent session supplies a practical use case for the continuing conversation, though these posts do not establish what caused the recent bounce.
Posts to understand this
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable’s March high coincided with its free build day and a parent’s report of his daughter launching an app after attending. Conversation share fell through July, then partly recovered in August and September, when MotherDuck highlighted Lovable’s web growth alongside the continued dominance of older publishing platforms. The recovery remains limited: share is down 4.3% over the last 30 days.
Posts to understand this · as of Oct 19
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit’s May high gave way to a lower summer baseline, with an August lift alongside OpenAI’s announcement that GPT-5.6 Luna powered Free Mode. The London office opening and Runway integration added fresh reasons to talk about Replit; share is up 16.5% over the last 30 days, but down 15.2% over 90 days.
Posts to understand this
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
OpenClaw’s share declined every completed month from March through September, after February’s news that creator Peter Steinberger would join OpenAI. Later evidence shifts to DeepSeek compatibility and a comparison with Grok’s bot, rather than another comparable announcement; the decline has slowed to 4.9% over the last 30 days, but the curve has not reversed.
Posts to understand this · as of Oct 18
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
Codex’s share rose from 1.8% in March to 3.0% in May, then held near 3.1% through September; the last 30 days are down 1.7%. April posts described building startup demos and Salesforce agents with Codex. July’s Clay integration added terminal access to search data, run functions, and create or trigger workflows.
Posts to understand this · as of Oct 20
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Hermes Agent went from no March share to a May high, then lost ground through September. Higgsfield’s April MCP announcement gives that early burst a concrete integration story, but the later voice-access post does not explain the sustained decline. The last 30 days are up 7.7%, with Microsoft Store availability adding a fresh distribution event after the long fade.
Posts to understand this · as of Oct 20
 inDistribution expansionNous Research announces one-click Hermes Agent installation through the Microsoft StoreHA
 XContent integrationHiggsfield announces MCP content creation access through Hermes Agent and other agentsLH
 XVoice accessLuke Harries shares ElevenLabs developers’ invitation to call a Hermes agent
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce held near 4% share through summer before September's jump, when Informatica announced its Dreamforce debut as part of the company. The last 30 days are down 31.2%, so that lift has not held. June's roughly $3.6 billion Fin acquisition agreement and October's Salesforce-in-Claude forecasting example show separate sources of attention across deals, events, and everyday use.
Posts to understand this · as of Oct 20
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
HubSpot peaked in May, declined through August, then recovered some share in September; the last 30 days are up 13.1%, despite a 25% decline over 90 days. The supplied posts do not explain May's peak, and June's Warmly acquisition announcement did not halt the slide. October's layoff discussion adds a concrete new reason for attention.
Posts to understand this · as of Oct 20
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Gong’s share eased after April, despite May’s announcement of $500 million in ARR and 55%+ annual growth. The posts trace a gap between broad platform positioning and concrete uses: August brought criticism of its “Revenue AI OS” language, while October highlighted churn analysis from calls. The last 30 days show a modest 5.2% lift within a longer decline.
Posts to understand this
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
Vercel’s share has oscillated rather than sustained a climb, with August’s high followed by a September drop and a nearly flat last 30 days at +0.4%. The posts show recurring exposure through Grok’s connector, Rillet’s agent workflow, and developer stack recommendations. That pattern fits ongoing visibility across use cases, though it does not identify a cause for August’s spike.
Posts to understand this · as of Oct 21
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Cowork’s conversation share fell each month from March’s 3.29% to September’s 0.54%, with another 23% decline over the last 30 days. February’s prospecting build and April’s live content demo show concrete workflows behind the earlier conversation; September’s Docusign integration added a contract workflow story as overall attention continued to shrink.
Posts to understand this · as of Oct 20
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly's share climbed through June, roughly halved in July, then held near that lower level through September; the last 30 days are down 2.6%. No supplied post explains the June peak. The later plateau has concrete usage behind it: a 200-mailbox workflow connected to Slack and Attio, an outbound hiring request, and a first-campaign meeting report.
Posts to understand this · as of Oct 19
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter’s conversation share climbed unevenly into an August peak, fell sharply in September, and is up 14.1% over the last 30 days. Recent posts highlight OpenAI overtaking Anthropic in weekly user spending, DeepSeek’s earlier token-volume gains, and a founder podcast following Stripe’s acquisition. These show the discussion continuing, but do not establish what caused August’s spike.
Posts to understand this · as of Oct 21
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
Substack’s uneven spring gave way to a July bounce and renewed decline through September; share is down 17.1% over the last 30 days. The posts show competing pulls rather than one decisive event: Elena Verna describes a substantial newsletter audience, while Adam Schoenfeld explains his move to beehiiv for customization. Karlie Kloss’s October launch adds a new creator story.
Posts to understand this
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Semrush rose in May and reached its highest share in June, with the Lovable partnership providing a concrete expansion into app-building workflows. The posts do not explain the full June spike or subsequent retreat, but September’s recovery and a 9.3% last-30-day gain accompany a different conversation: reliable search data and how marketers should measure AI visibility.
Posts to understand this · as of Oct 20
 inProduct partnershipLovable adds Semrush data for keyword research, landing pages, and SEO auditsS
 inData continuitySemrush says Google redirect changes have not affected its tracking or accuracyMS
 inMeasurement debateMarcel Santilli previews a Semrush Spotlight talk challenging brand visibility scores
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva’s April high faded through September, and neither Grok’s May connector announcement nor September’s 100 upgrades produced a sustained monthly rise. Share is now up 36.5% over the last 30 days, with a concrete workflow example: Tom Mansfield reports that Claude built editable Canva decks and cut his presentation build time by at least 80%.
Posts to understand this
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Ahrefs jumped sharply in May, held much of that level in June, then reset lower through July-September. The L30 move is now up 34.8%, although the 90-day view remains down 26.9%; conversation spans praise for its marketing, criticism that AI workflows can replace SEO dashboards, and Ahrefs’ response to Google’s /goto redirects.
Posts to understand this · as of Oct 16
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier’s spring conversation centered on AI GTM teams and practical trigger-and-action workflows, with May followed by a broad decline through September. The October SpaceX Super Intelligence partnership adds an agent connectivity story across 9,000-plus apps, but the last 30 days remain down 11.2%. The evidence shows continued product relevance without a sustained lift in conversation share.
Posts to understand this
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
ZoomInfo’s June bump coincided with Exa Connect making its data available to agents, followed by three consecutive monthly declines through September. Share is down another 17.8% over the last 30 days. The posts frame ZoomInfo both as agent infrastructure and a replacement target, with Ava 2.0 and Moltsets making competitive claims; they do not establish what caused the decline.
Posts to understand this · as of Oct 18
Profound measures and improves how brands appear in AI answers.
Profound’s April and July increases coincided with criticism of customer content quality and measurement reliability, while September’s rebound brought a $180 million Series D. The curve reflects alternating scrutiny and funding news, rather than a steady climb. Conversation share is down 17.5% over the last 30 days, despite a modest 90-day gain.
Posts to understand this
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
ElevenLabs’ conversation share rose through May, then fell unevenly to an August low before recovering in September, when posts highlighted reported ARR growth and enterprise hiring. Share is up 58.3% over the last 30 days. The October 20 Realtime launch adds a product story, but arrived after the recovery began and has no demonstrated effect on the curve yet.
Posts to understand this · as of Oct 20
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio’s spring climb coincided with Intercom’s Fin for Sales launch and its own GTM Atlas release, with share highest in May before a decline through September. The last 30 days show a modest 9.8% recovery. October’s evidence concerns positioning: Peep Laja cites Attio’s move to “CRM for agentic revenue” as part of a broader spread of agentic language.
Posts to understand this · as of Oct 21
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo’s spring surge coincided with users moving prospecting and enrichment into Claude, with Apollo as the underlying data source. Share peaked in May, held near a lower level through August, then softened; it is down 16.5% over the last 30 days. September’s ApolloNext vision for three connected products has not yet produced a sustained rebound.
Posts to understand this
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify rose sharply into May and held near that level through July, with posts demonstrating Claude social analysis and competitor ad research. Those repeatable workflows give the plateau a concrete theme beyond a single launch. Share eased in August and September and is down 31.9% over the latest 30 days, despite a fresh pitch for Apify’s agent tools.
Posts to understand this
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Granola fell sharply from May through July, recovered somewhat in August, then eased again in September. The latest 30 days are up 20.1%, while early October offers only preliminary context; attention spans product expansion through Apple Watch, inclusion in Grok’s sales integrations, and concern that a stronger Siri could erase standalone tools.
Posts to understand this · as of Oct 16
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
HeyReach rose into a May-June plateau, then settled lower, with share down 11% over the latest 30 days. The evidence points to recurring inclusion in outbound playbooks rather than a single launch: Voje and Ruha place it in specific GTM stacks, while Masood questions whether an automation-heavy stack actually generates business.
Posts to understand this · as of Oct 21
RB2B identifies the people and companies visiting a website so sales can follow up.
RB2B climbed to a June high after a May post reported $9.1 million-plus ARR, then fell sharply through August. September recovered some ground and the last 30 days are up 28.6%; recent posts put RB2B inside repeatable outbound systems, where website visits trigger outreach, rather than center the company’s own growth story.
Posts to understand this · as of Oct 22
Intercom is a customer messaging platform built around Fin, its AI support agent.
Fin’s observability launch gave Intercom a concrete March announcement, but the posts do not explain June’s rebound or July’s sharp drop. August and September stayed well below those earlier levels despite Lemkin’s account of a $3B-plus Salesforce exit. Attention is down 43.5% over the last 30 days, even as Adam Robinson describes Fin as central to RB2B’s lean support model.
Posts to understand this · as of Oct 18
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
LangChain fell hard in April, rebuilt through June, and then held a narrow July-September range, with September the strongest month since June. The L30 move is down a modest 5.5%, so the shape is more plateau than break: discussion spans its GTM agent results, production-grade agent tooling, and September evaluation work.
Posts to understand this · as of Oct 16
Baseten deploys and runs custom AI models in production.
Baseten’s July–August rise coincided with Kimi K3 launch support and free access to Inference Engineering, before share eased in September. Harvey’s September partnership added an M&A diligence use case, but the last 30 days are down 23.7% despite a 21.6% gain over 90 days. The evidence points to several distinct announcements rather than one sustained launch cycle.
Posts to understand this · as of Oct 22
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Nooks’ share climbed from March through July, fell in August, then rebounded in September. May’s Replit example showed continued use for dialing; October posts covered customer research and infrastructure for revenue agents. Those newer topics accompany a softer current trend, with share down 13.4% over the last 30 days.
Posts to understand this
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Common Room climbed steadily from March to a July high, then dropped sharply in August and again in September after Zoom announced its acquisition on July 2. The L30 measure is nearly flat at negative 2.1%, so the curve now looks like a low plateau after the deal, within a wider run of GTM platform consolidation.
Posts to understand this · as of Oct 16
Exa.ai is a web search API designed for models and AI agents.
Exa’s share has been uneven, with a July high followed by an August dip and September recovery; the last 30 days are up 28.1%. Exa 3.0 gives the current move a concrete launch, while Sean Wilson’s outbound stack and Paul Klein’s retrieval-versus-action framing show a broader pattern of practical uses for agent search.
Posts to understand this · as of Oct 22
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly’s steady spring rise culminated in July, when posts discussed HubSpot’s acquisition alongside Zoom buying Common Room. Share dropped sharply in August and stayed low in September; the last 30 days are down 18%. The evidence fits an acquisition attention cycle, with later discussion treating Warmly as an example of GTM consolidation.
Posts to understand this · as of Oct 21
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode’s gradual spring rise accelerated in July and August, with Grok’s invitation to try Grok 4.6 in OpenCode landing in its highest completed month. September cooled, and the last 30 days are down 16.5%. The broader pattern is ecosystem support: Linear offered issue handoffs before the rise, and Databricks later included OpenCode in centralized agent management.
Posts to understand this · as of Oct 20
Gamma turns prompts into presentations, documents, websites and images.
Gamma’s share fell from March to July and stayed below its spring levels through September; the latest 30 days are up 33%. Integrations are the recurring thread, from a Claude connector to Confluence and then September’s two-way Atlassian integration. That gives the recent lift a concrete product context, although the 90-day trend remains down 7.1%.
Posts to understand this
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps’ May spike coincided with AirOps Next and Quill, a release described as lowering the learning curve for content workflows. Share then settled much lower through September, so the event attention did not hold. The latest 30 days are up 20.7%, with fresh citation research from Ross Simmonds and AirOps supplying a practical reason to revisit the product.
Posts to understand this · as of Oct 18
1mind provides AI sales agents for websites, demos, live calls and customer success.
1mind’s share declined from June through September, then gained 73.6% over the latest 30 days, while remaining down 33.1% over 90 days. Its October Elite Growth Summit supplies a fresh conversation hook, with an attendee reporting more than 100 GTM leaders. Earlier posts establish the product story through buyer access and reported sales results, but do not explain the recent lift.
Posts to understand this
Firecrawl turns websites into clean, structured data for models and agents.
Firecrawl’s curve is uneven rather than a sustained climb: May and July bumps gave way to a quieter August and September. The posts supply recurring reasons to talk about it, from Claude Code lead research to credits for community actions and Lovable’s built-in access. Share is up 47.3% over 30 days but only 1.9% over 90 days, a rebound within that pattern.
Posts to understand this · as of Oct 18
Higgsfield generates video and images for ads and social content.
Higgsfield held roughly steady in June and July before an August drop; its latest 34.6% gain is a recovery within a weaker 90-day picture. June’s Pokémon asset giveaway illustrates creator use, while the October 2 AI Influencer launch supplies a fresh product hook. Together AI’s August customer announcement did not coincide with a broader monthly rise.
Posts to understand this · as of Oct 22
Grok Bot is an always-on agent that learns routines and completes work across existing software.
Grok Bot entered the conversation with its August early beta, followed by a user account of autonomous service cancellation; share grew from 1.3% in August to 2% in September. Runway’s October integration adds another capability, but the last 30 days are essentially flat at minus 1.4%, so the launch momentum has settled into a plateau.
Posts to understand this
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce entered the conversation with its August launch, then gained share in September as Dreamforce put Claude alongside Slack in Salesforce’s interface story. That launch and conference sequence fits the initial rise, but attention is now down 82.7% over the last 30 days, despite Jason Lemkin’s October demo pitch for running Salesforce through agents.
Posts to understand this
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
GPT-6 jumped from barely visible to 5.1% of conversation in September, alongside concrete evidence of performance and use: Perplexity’s top WANDR score, OpenAI’s reported OpenRouter spending record, and Supabase’s unlimited Astra tokens. Share is down 37% over the last 30 days as that September burst cools; the posts offer no specific explanation for the retreat.
Posts to understand this · as of Oct 19
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Fable broke into the conversation in June, when Cognition added Fable 5 to Devin and reported a first-place FrontierCode result, then reached its highest share in July. August’s safeguard update and September’s Opus 5.5 comparison kept it in view, but the September rebound did not hold: conversation share is down 60.1% over the last 30 days.
Posts to understand this · as of Oct 18
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
GPT-5’s share dropped sharply after April and stayed low from May through September; the latest 30 days are nearly flat, down 2.5%. The posts do not explain the initial drop, but show the conversation that persists: benchmark comparisons and cost tradeoffs. Palantir reports Tampa General Hospital cut costs 68% with GPT-5 mini, while João Moura questions frontier-model price increases.
Posts to understand this · as of Oct 18
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Opus has a recurring spike pattern, with April and May strength, a June drop and renewed September attention. April’s Perplexity and Harvey integrations and September’s Opus 5.5 arrival in Cursor give two of those bursts concrete anchors. The current move is up 305.5% over 30 days, alongside Cursor’s claim of a leading benchmark score and 40% lower task costs.
Posts to understand this · as of Oct 18
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Grok 4 conversation jumped in July when Grok 4.5 reached Perplexity and topped an automation benchmark, then cooled through August and September. The last 30 days are up 82.3%, with Grok 4.7’s reported agentic coding position giving the conversation a fresh benchmark-led catalyst.
Posts to understand this · as of Oct 16
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Sonnet’s June spike aligns with Sonnet 5’s launch and Legora’s early testing, then attention faded through August despite permanent introductory pricing. September regained some ground, and the last 30 days are up 422.2%, with an October Sonnet 5.5 coding example in the mix. That example gives the renewed attention a concrete use case, but cannot explain the whole move.
Posts to understand this · as of Oct 18
Muse Spark is Meta's AI model for running coding and other agents.
Muse Spark moved from sparse spring mentions to successive gains from July through September, and the last 30 days are up 62.8%. October supplies several reasons for attention rather than one clean success story: Baseten added Muse Spark Open, Surge compared Spark 1.3 against Mistral, and Arena reported Muse Wonder replacing it as Meta’s top model.
Posts to understand this · as of Oct 22
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Gemini Flash spiked in May around the Gemini 3.5 Flash release, early Databricks availability, and a leading Apex Agents benchmark result. September held near August levels as Gemini 3.8 Flash reached security work through Wiz and Google DeepMind, but the L30 measure is now down 50.4%, a sharp cooling after that support.
Posts to understand this · as of Oct 16
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
Kimi’s sharp July spike coincided with Together AI’s claim that K3 matched Claude Fable 5 on software engineering tasks at roughly 35% of the price. Share then receded through September despite Harvey’s Kimi-based legal model and free access in Cline. The last 30 days are down 17.2%, consistent with attention fading after the comparison burst.
Posts to understand this
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen surged in July and August, then lost more than half its share in September; the latest 30 days are down 22.4%. The n8n Qwen Cloud node launch supplies a concrete integration story near the summer climb, though these posts don’t establish what drove August’s high. September’s Qwen-Image-2.1 announcement and local deployment example show continued activity despite the retreat.
Posts to understand this · as of Oct 20
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM jumped in June and held a higher baseline through August, alongside praise for GLM 5.2’s local coding capabilities and free access in Devin. September’s Bolt post added usage evidence: GLM 5.3 Flash led its open model choices at 54%. Conversation share nevertheless fell in September and is down 46.2% over 30 days; product uptake did not sustain the earlier attention.
Posts to understand this · as of Oct 18
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos shows two bursts in April and June, followed by a quieter July through September; the posts do not identify what triggered either spike. The pattern is attention that releases and security concerns have not sustained: September’s Mythos 5.1 announcement and October’s report of Bank of America’s patching effort sit against a 39.3% decline over the last 30 days.
Posts to understand this
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney’s June spike coincided with posts about its community-funded model and Gamma’s use of its tools for an entire brand system. Share dropped sharply in July and stayed below June through September, with the latest 30 days down 18%. The later short-film post puts Midjourney inside a Claude-led workflow, but the evidence offers no single cause for the sustained decline.
Posts to understand this · as of Oct 20
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Devin’s share peaked in April, fell through June, rebounded into August, then slipped in September. The latest 30 days are down 13.4%. Windsurf’s April launch highlighted cloud delegation; October evidence centers on Pylon’s support bug handoffs and CodeRabbit’s security benchmark, without explaining the summer rebound.
Posts to understand this · as of Oct 22
Runway is an AI platform for generating and editing video and images.
Runway’s share more than doubled in September after a quiet July and August, with the last 30 days up another 11.3%. No supplied post explains the September jump directly. The evidence spans solo ad production, Pika’s price comparison against Runway Dev, and October discussion of 60 Minutes coverage, rather than one identifiable launch.
Posts to understand this · as of Oct 21
Jev is TypeSafe AI's decision model, which returns typed answers such as choices, probabilities and scores instead of text.
Jev appeared abruptly in September, then accelerated again over the last 30 days. LangChain’s evaluation supplied technical validation, while HeyGen and Ira Bodnar showed the model making concrete decisions across lead routing, ad analysis, brief scoring and search-term classification.
Posts to understand this · as of Oct 16
Muse is Meta's personal AI agent, which connects to a person's email, calendar and payments to shop, book and schedule for them.
Muse moved from almost no share in August to 1.2% in September as Notion and Stripe announced integrations for workspace updates and business payments. The last 30 days are up 222.9%; October’s discussion also includes Liza Adams’ concerns about personal agents acting without approval, so the conversation now spans both practical capabilities and trust.
Posts to understand this
Instinct is a personal AI agent with its own email address that creates accounts, contacts businesses and handles support requests for its user.
Instinct went from no recorded share through July to a sharp September rise, alongside reports of rapidly higher valuations. Its latest 81.4% gain has fresh partnership context: participation in Meta and Sierra’s Personal Agent Protocol and a Decagon collaboration. The conversation now has business integration news alongside the funding story.
Posts to understand this
Muse Wonder is Meta's most capable model series, built for personal and work agents that keep track of goals across long tasks, including coding.
Muse Wonder is new in the last 30 days after no recorded share from March through September. Its early October presence has a concrete distribution story: fal demonstrated image and video connections, Genspark added it across three products, and Cursor announced availability with a CursorBench score. These clustered announcements explain its arrival, but do not yet establish sustained momentum.
Posts to understand this · as of Oct 21
Join 19,539+ GTM leaders and practitioners. Free, unsub anytime.
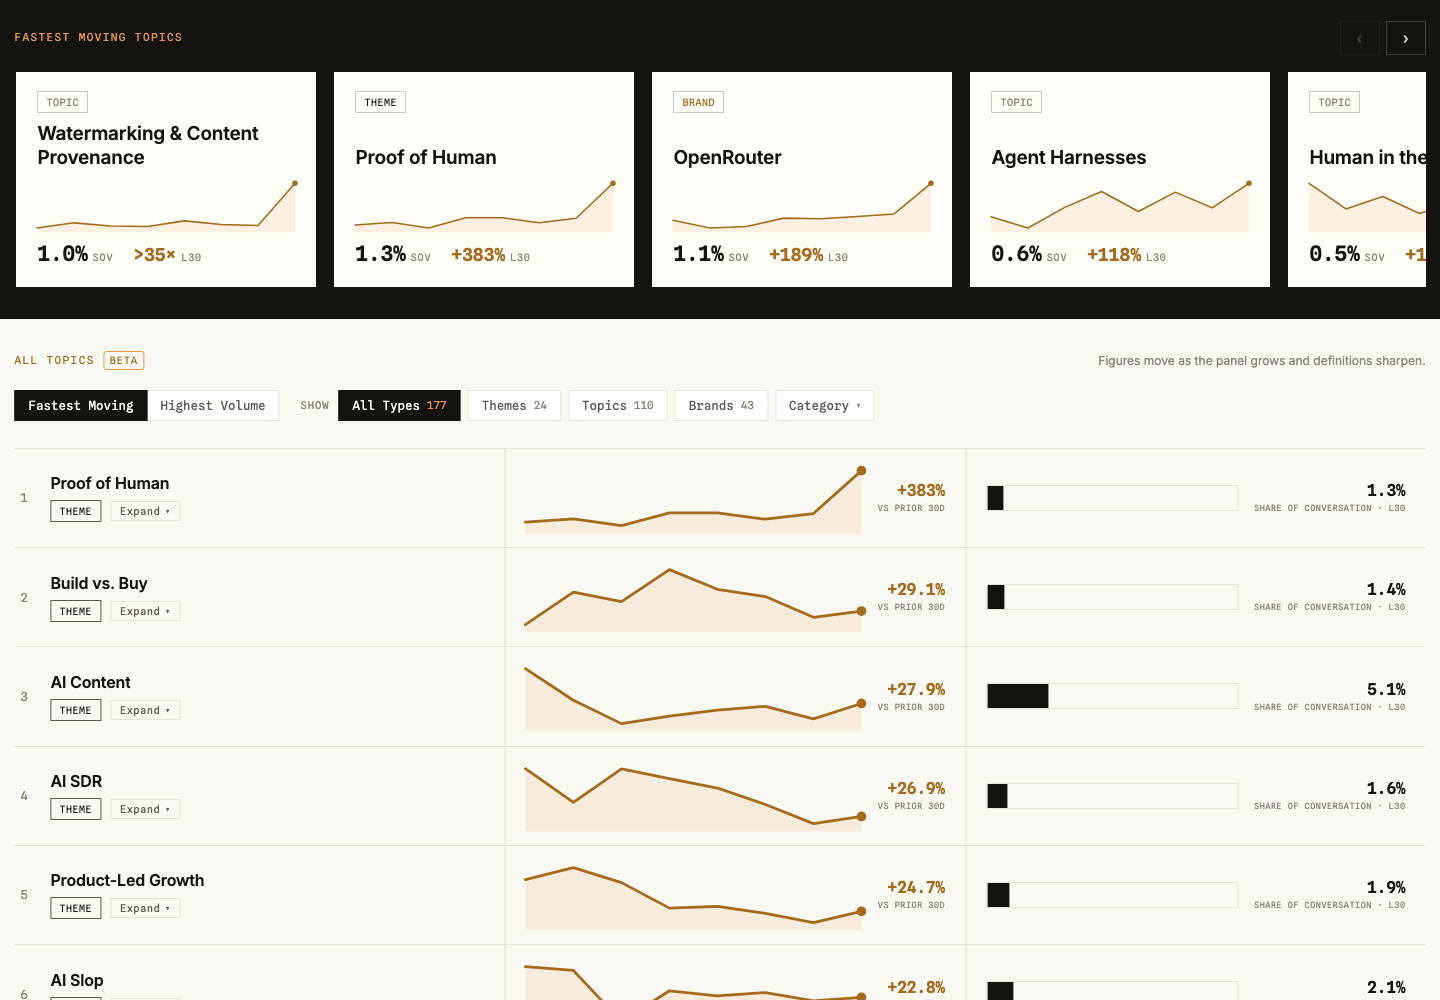
Loading people…
join 19,539+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-10-24.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,539+ gtm leaders, unsub anytime.