What’s moving now
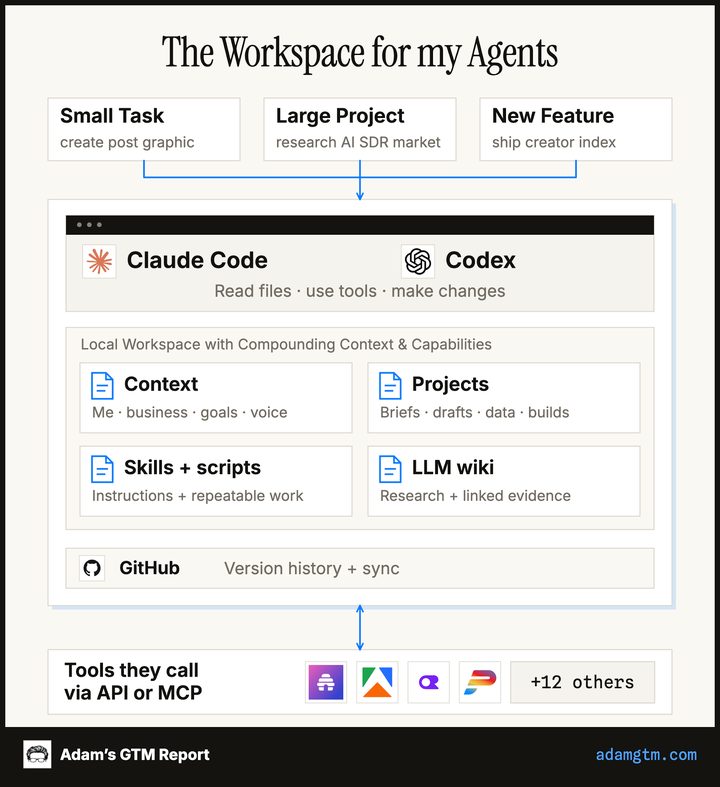 How I'm buildingOct 8 · the agents, workflows, and tools behind my one-person busi
 13.8× the usual response · 248 engagements
 D12.9× the usual response · 1,391 engagements
 10.0× the usual response · 1,236 engagements10.0× the usual response · 1,236 engagements
 6.2× the usual response · 275 engagements
 Kyle NortonIn an Anthropic-sponsored post, the author reports building an adjustable sales forecast with Claude and Salesforce in two days, identifying missing lead sources that could skew conversions.
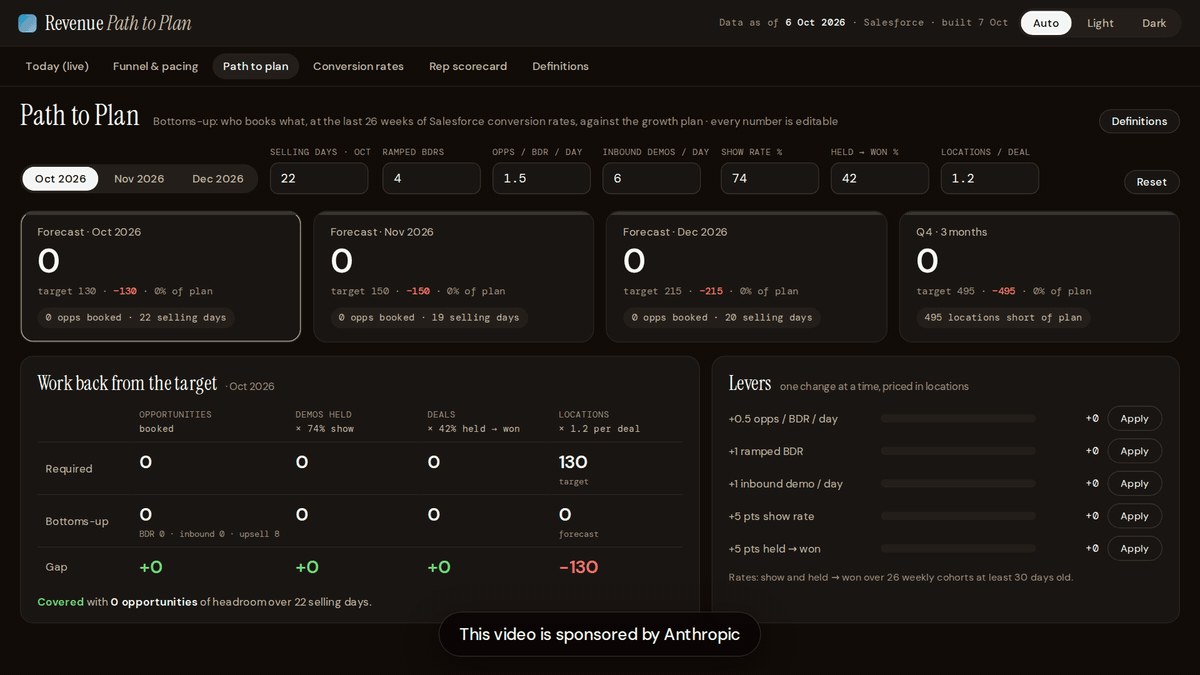 596 interactions · 2d agoTrending Creator
 Anthony PierriJokes that LinkedIn stops seeming cringe when a positioning consultancy reaches $5 million in revenue.
 575 interactions · 1d agoTrending Creator
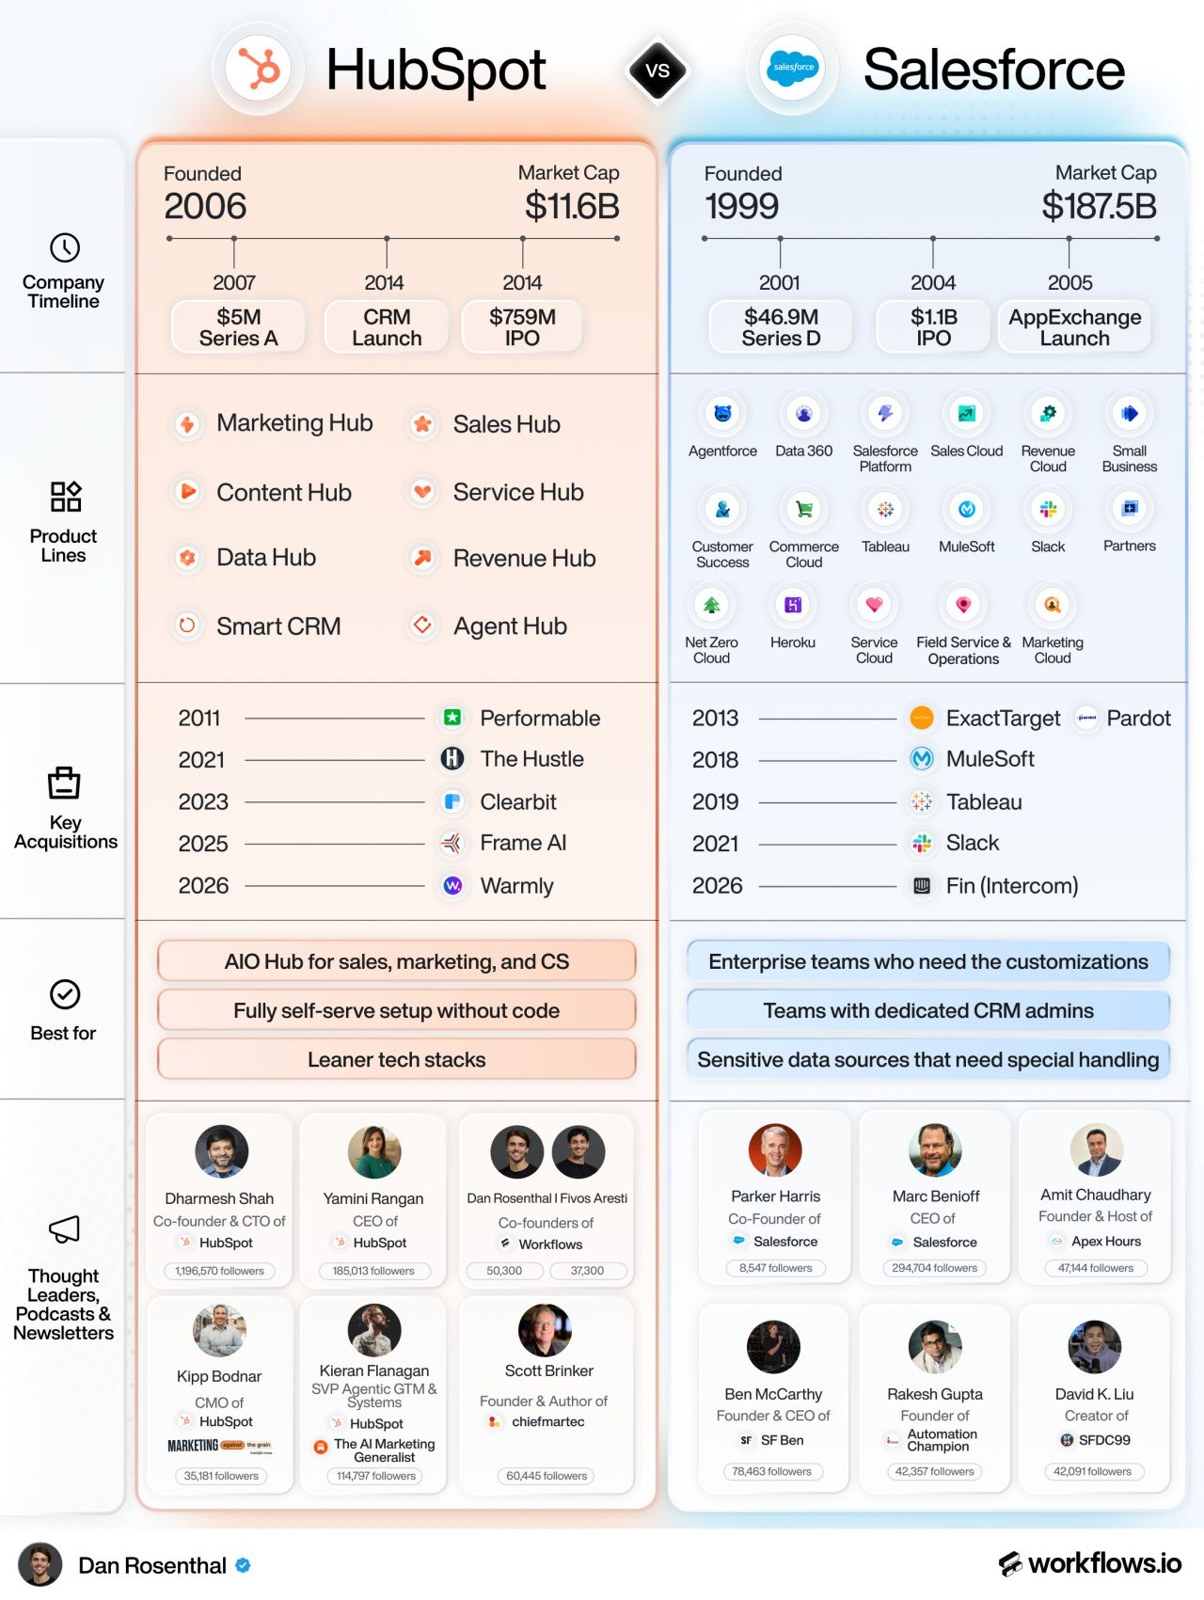
 Dan RosenthalCompares HubSpot and Salesforce, favoring HubSpot for simpler setup and leaner operations while recommending Salesforce for larger enterprises with complex data needs.
 468 interactions · 2d agoTrending Creator
 Diandra EscobarDescribes an SEO consultant attracting learners instead of paying CMOs and founders, arguing that audience alignment matters more than posting volume.
 444 interactions · 2d agoTrending Creator
 Christopher LochheadCriticizes the New York Times framing of AI agents going rogue, arguing that developers and companies should remain accountable for software failures.
 408 interactions · 1d agoTrending Creator
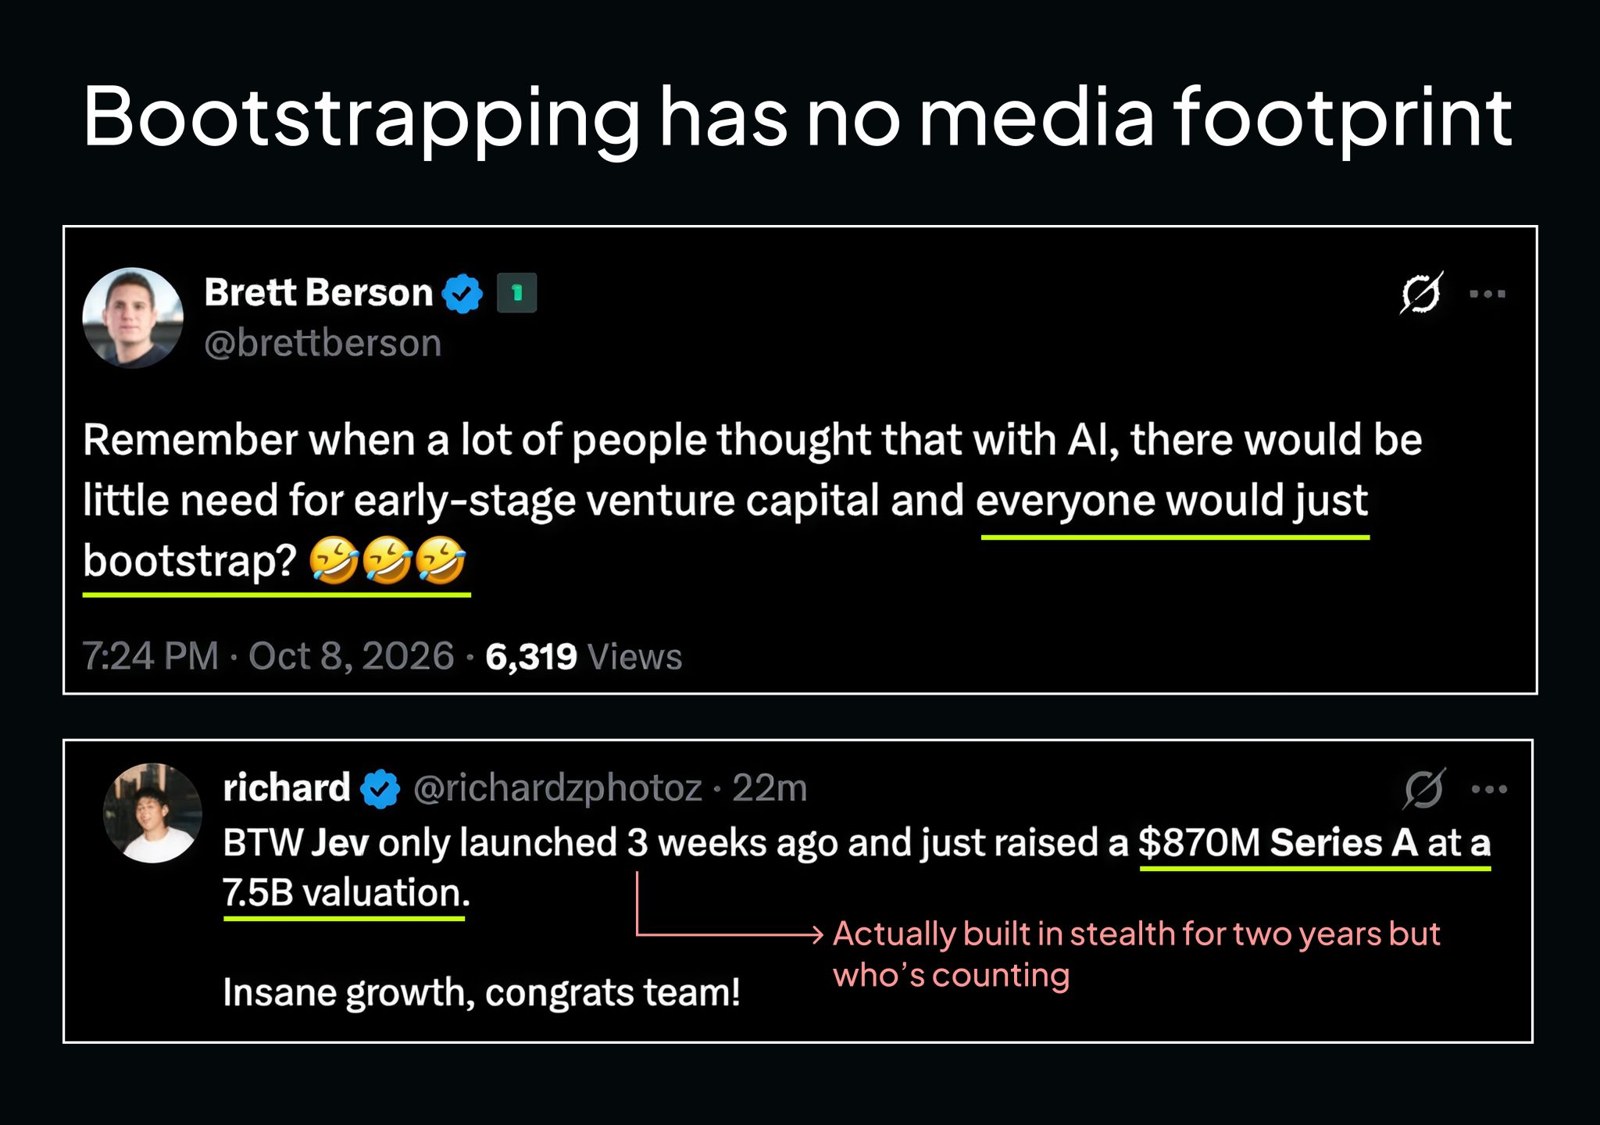
 Peter WalkerArgues that bootstrapping AI businesses brings visibility and recruitment challenges but may yield greater financial rewards for founders than venture funding.
 325 interactions · 2d agoTrending Creator
 Alex VaccaPresents an ABM technology stack covering account selection, personalized campaigns, and intent attribution, arguing account lists and spending should adapt to demonstrated interest.
 262 interactions · 2d agoTrending Creator
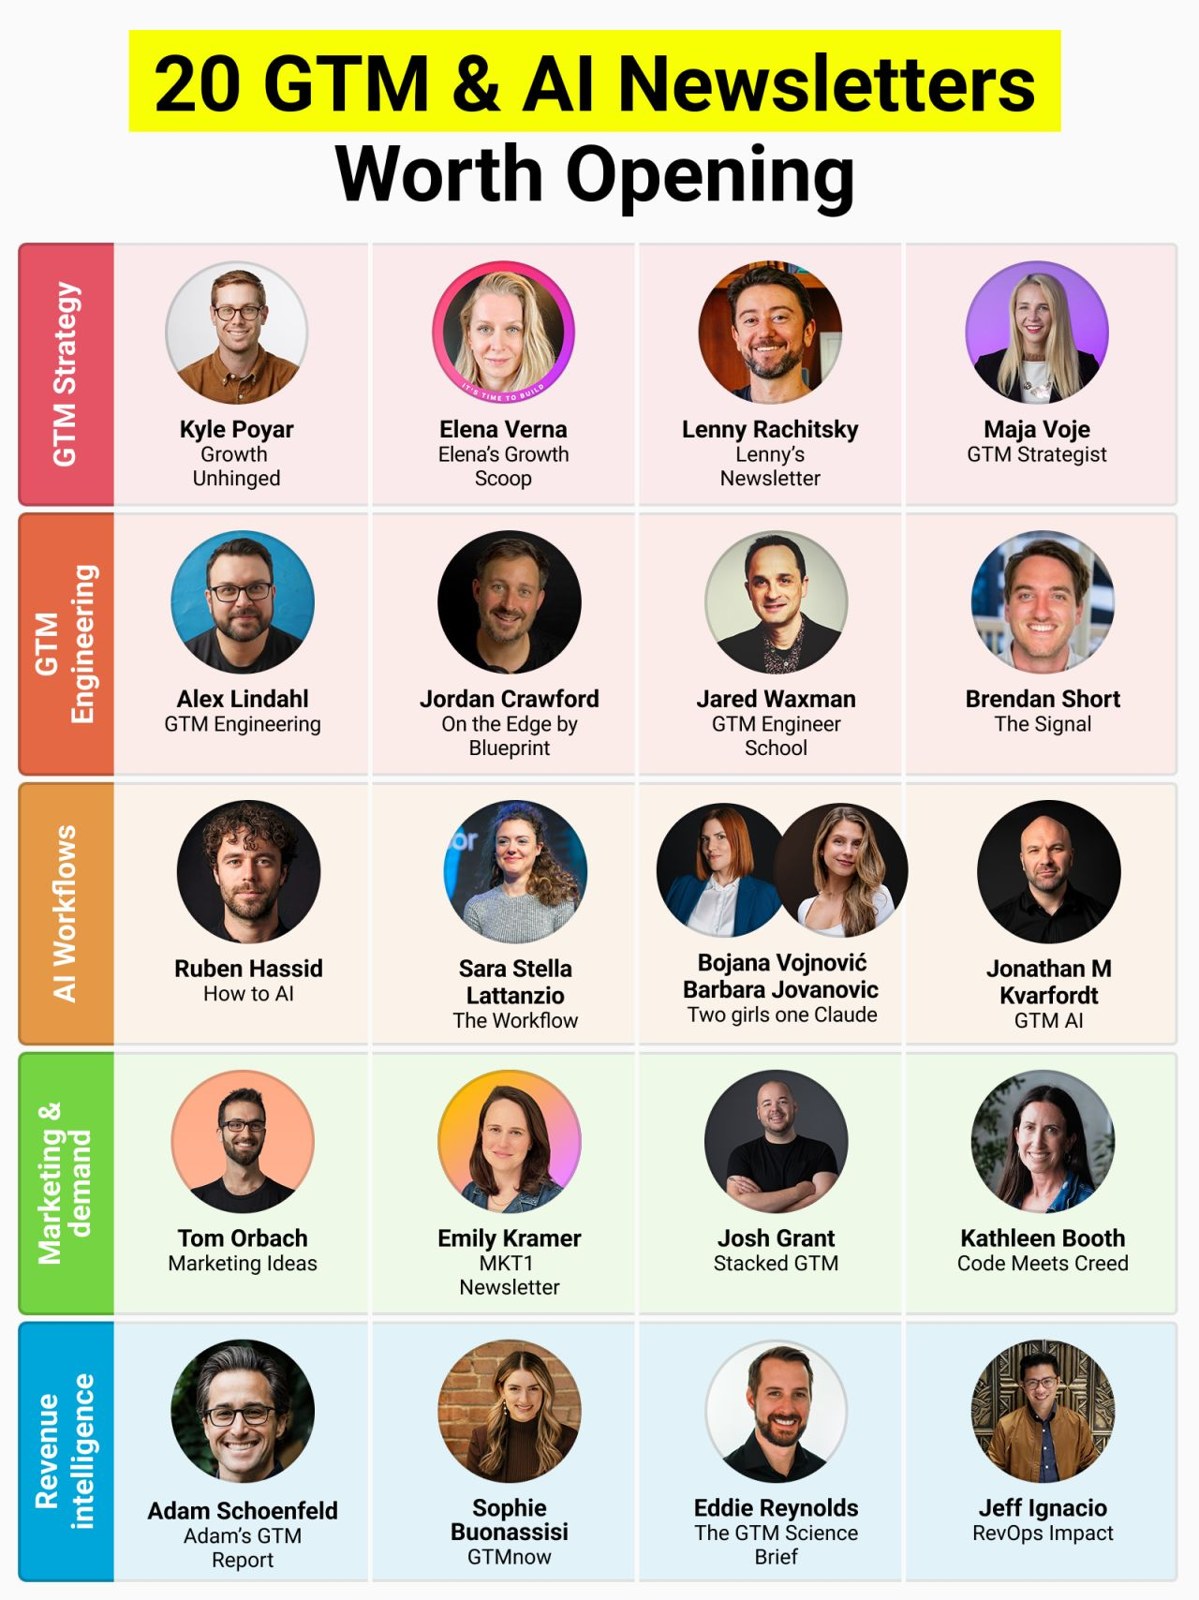
 Maja VojeRecommends 20 newsletters from 207 subscriptions, covering GTM strategy, GTM engineering, AI workflows, marketing and demand, and revenue intelligence.
 236 interactions · 17h agoTrending Creator
 Ross HudgensReports Ramp attributed 30–40% of direct visits to AI and proposes identifying AI referrals through direct traffic to long-tail pages with search-like behavior.
 212 interactions · 2d agoTrending Creator
 Fivos ArestiLists 25 buying signals across first-party, second-party, and third-party data, with applications in ad retargeting, automated outreach, sales alerts, and awareness scoring.
 201 interactions · 2d agoTrending topicAI Safety+115% vs prior 30d · 2.1% of the conversationTrending topicAI-Driven Advertising+75.4% vs prior 30d · 0.7% of the conversationTrending topicObservability+40.0% vs prior 30d · 0.5% of the conversationTrending topicMarketing Automation+29.2% vs prior 30d · 0.7% of the conversationTrending topicAttribution+29.1% vs prior 30d · 2.0% of the conversation
 Docket↑27 places in AI-Native GTM Challengers
 Ploy↑9 places in AI-Native GTM Challengers
 Cline↑8 places in Coding Agents & Harnesses for GTM
 Sequel↑39 places in Traditional SaaS Going Headless
 LeanData↑37 places in Traditional SaaS Going Headless
Trending Topics
Market Moves
 M207 engagements · 2.8× usualPost ↗D1,391 engagements · 12.9× usualPost ↗blog ↗
 Post ↗
 Post ↗275 engagements · 6.2× usualPost ↗
 S167 engagements · 3.6× usualPost ↗
GTM Tech Index
Latest Posts
Oct 8How I'm buildingthe agents, workflows, and tools behind my one-person business.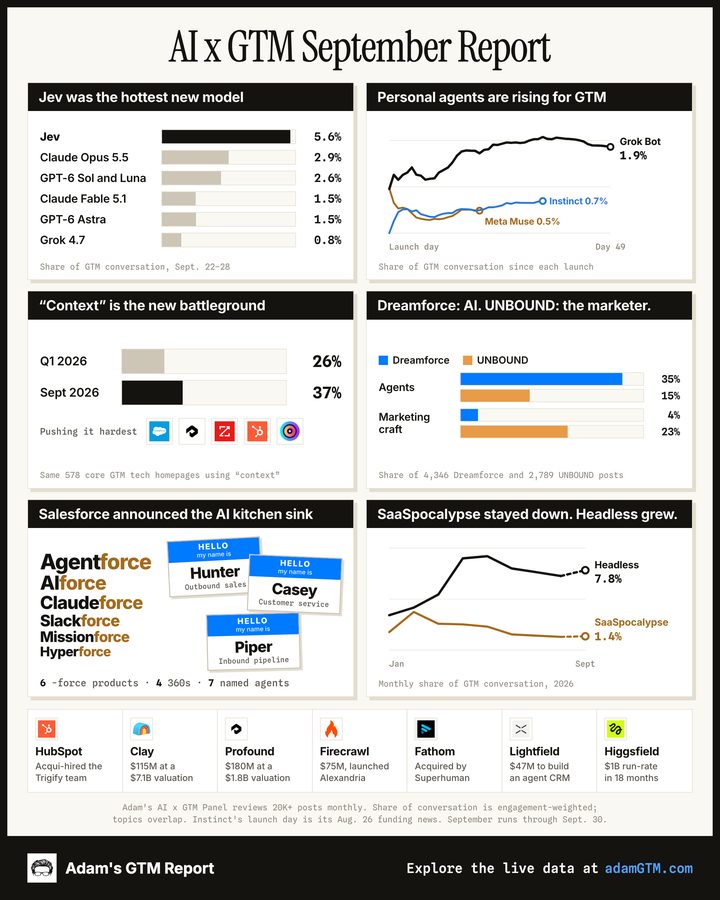 Oct 1Everything I measured in AI x GTM -- September reportfull EOM readout: 73 market moves, personal agents vs models, GTM's big rounds, the battle for GTM context, and Dreamforce vs Unbound.
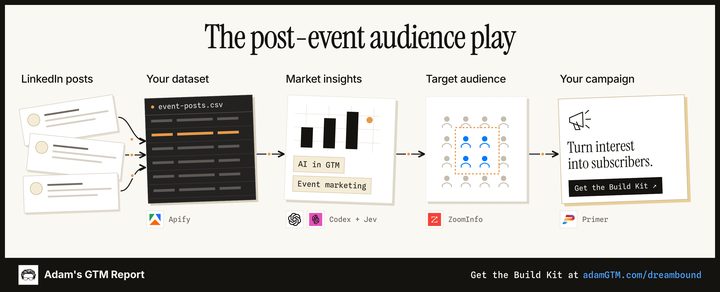 Sep 24My post-conference playbookHow to collect the conversation, find an angle, and build a unique audience. Lessons from Dreamforce and UNBOUND.
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
All topics
BetaFigures move as the panel grows and definitions sharpen.
+11.3%vs prior 30d-14.3%vs prior 30d-5.8%vs prior 30d+18.4%vs prior 30d+3.3%vs prior 30d-12.5%vs prior 30d-5.1%vs prior 30d-42.3%vs prior 30d+7.0%vs prior 30d +227%vs prior 30d-15.1%vs prior 30d-58.7%vs prior 30d-23.2%vs prior 30d+45.8%vs prior 30d-21.4%vs prior 30d-5.2%vs prior 30d
 -3.3%vs prior 30d+12.5%vs prior 30d-37.2%vs prior 30d+24.9%vs prior 30d
 +13.8%vs prior 30d-0.4%vs prior 30d+1.3%vs prior 30d+10.8%vs prior 30d-4.6%vs prior 30d+66.0%vs prior 30d-26.7%vs prior 30d-25.6%vs prior 30d
 -25.1%vs prior 30d-44.1%vs prior 30d-28.5%vs prior 30d+3.7%vs prior 30d
 -37.5%vs prior 30d+11.1%vs prior 30d+414%vs prior 30d-45.9%vs prior 30d+14.6%vs prior 30d
 -12.4%vs prior 30d-43.6%vs prior 30d-46.1%vs prior 30d-5.3%vs prior 30d
 -9.9%vs prior 30d-23.4%vs prior 30d
 -69.1%vs prior 30d
 +17.5%vs prior 30d
 -45.9%vs prior 30d
 -36.1%vs prior 30d
 +5.6%vs prior 30d
 -41.8%vs prior 30d
 +4.4%vs prior 30d
 -5.0%vs prior 30d-36.8%vs prior 30d
 +1.9%vs prior 30d
 -3.9%vs prior 30d
 -51.2%vs prior 30d
 -24.3%vs prior 30d
 -27.1%vs prior 30d-43.3%vs prior 30d
 +15.0%vs prior 30d-16.7%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
Conversation declined gradually from 27.6% in April to 19.7% in September, with L30 down 8.9% and L90 down 18.9%. No single event caused the slide. The posts show a fragmented build phase: useful Claude skills, hard infrastructure constraints, and early ideas about world models rather than one dominant launch.
Posts to understand this · as of Oct 4
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 70 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Clay | 90 |
| 6 | Salesforce | 93 |
| 7 | HubSpot | 88 |
| 8 | Lovable | 59 |
| 9 | Replit | 57 |
| 10 | OpenClaw | 51 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO rose from 9.1% in April to 12.0% in June, then declined for three straight full months to 8.5% in September. The L30 remains down 10.7%; the evidence points to a shift from category excitement toward practical products and a renewed insistence on SEO fundamentals.
Posts to understand this · as of Oct 7
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Ahrefs | 50 |
| 3 | HubSpot | 88 |
| 4 | Semrush | 48 |
| 5 | Clay | 90 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 38 |
| 8 | Salesforce | 93 |
| 9 |  Customer.io | 39 |
| 10 |  Optimizely | 31 |
How software exposes its data and actions so agents can use it directly.
Headless and agent interfaces jumped from March into April and May, then settled into a durable 7% to 8% band through September. The L30 is essentially flat, which makes the plateau meaningful. Cloudflare monetization, Notion’s developer surface, and Templafy’s MCP show agents gaining direct access to software, payments, and finished work.
Posts to understand this
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 88 |
| 5 | Clay | 90 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Grok Bot | 70 |
| 8 | Instantly | 63 |
| 9 | Lovable | 59 |
| 10 | Exa.ai | 46 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click marketing briefly recovered to 9.4% in May, then declined across the next four full months to 6.2% in September. The L30 is down 8.9%, as conversation shifts from format advocacy toward durable distribution, real brand authority, and criticism of gated lead-generation systems.
Posts to understand this · as of Oct 7
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Ahrefs | 50 |
| 3 | HubSpot | 88 |
| 4 | Semrush | 48 |
| 5 | Clay | 90 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 38 |
| 8 | Customer.io | 39 |
| 9 | Instantly | 63 |
| 10 | Optimizely | 31 |
The people, tools and operating model behind custom go-to-market systems.
GTM engineering climbed to 9.2% in May, then declined every full month through September; the L30 is down 11.6%. The conversation remains active but concentrated around Clay, whose funding, internal stack, CLI, and agent plugin supplied distinct bursts without reversing the broader cooling pattern.
Posts to understand this · as of Oct 5
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Codex | 84 |
| 5 | Instantly | 63 |
| 6 | Salesforce | 93 |
| 7 | Prospeo | 52 |
| 8 |  FullEnrich | 44 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | AI Ark | 46 |
How companies prove AI delivers enough value to move beyond a pilot.
Conversation stayed in a durable 6.4% to 7.7% range from March through July, then fell across August and September. The current L30 move is down 9.8% as the debate shifts from raw efficiency claims toward cost per task, productive use of saved time, and the governance needed to move beyond experiments.
Posts to understand this · as of Oct 9
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 88 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Grok Bot | 70 |
| 7 | OpenRouter | 52 |
| 8 | Clay | 90 |
| 9 | ElevenLabs | 55 |
| 10 | Nooks | 48 |
How teams use buyer signals to decide who to target, when and why.
Signal-based sales and ABM declined from March through August, then recovered some ground in September. The L30 is up 8%, but the L90 remains down 23%, so this is a modest current lift within a longer contraction. Recent evidence favors operational proof: Orb connected scattered intent data, while Zoom tied signals to revenue action.
Posts to understand this
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | HubSpot | 88 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 93 |
| 5 | Instantly | 63 |
| 6 | Codex | 84 |
| 7 | Nooks | 48 |
| 8 | Attio | 52 |
| 9 |  6sense | 41 |
| 10 | AI Ark | 46 |
How large companies move AI from small pilots into secure, useful production work.
Conversation share peaked in April as Vanta described AI running continuous security work, then eased through summer. It fell more sharply in August and September and remains down 5.3% over the last 30 days, while recent discussion centers on undocumented workflows, governance, model routing, and process management.
Posts to understand this · as of Oct 6
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 70 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Midjourney | 36 |
| 7 | Nooks | 48 |
| 8 | Clay | 90 |
| 9 | Codex | 84 |
| 10 | Lovable | 59 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Open versus closed models surged from June to a July peak, then declined through August and September. Nvidia’s open-model letter and Kimi K3’s claimed price-performance advantage helped fuel the peak; Mistral’s €3 billion round reinforced the sovereignty case later, but the L30 move is still down 20.4% while the 90-day level remains elevated.
Posts to understand this · as of Oct 6
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | OpenRouter | 52 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Salesforce | 93 |
| 6 | Grok Bot | 70 |
| 7 | Baseten | 47 |
| 8 | Vercel | 60 |
| 9 |  Together AI | 33 |
| 10 | HubSpot | 88 |
How companies keep agents secure, accountable and under control as they take on real work.
Share climbed steadily from March through July, then fell in August and September; the last 30 days are down 5%, while October remains partial. The conversation now spans centralized routing and observability, task-level evals in safe environments, and stepwise autonomy that keeps security risks visible and bounded.
Posts to understand this
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 93 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Grok Bot | 70 |
| 7 | OpenRouter | 52 |
| 8 | Vercel | 60 |
| 9 | LangChain | 47 |
| 10 | Clay | 90 |
How teams create, distribute and judge marketing content made with AI.
Conversation rose into May, softened in early summer, then jumped in August as new tools connected generation to delivery workflows. September gave back that spike, and L30 is down 13.9% as discussion shifts toward creating inside existing tools and checking AI content against company-specific performance data.
Posts to understand this · as of Oct 9
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Claude Code | 99 |
| 3 | Runway | 36 |
| 4 | HubSpot | 88 |
| 5 | Salesforce | 93 |
| 6 | Grok Bot | 70 |
| 7 | Clay | 90 |
| 8 | Codex | 84 |
| 9 | HeyGen | 32 |
| 10 | Lovable | 59 |
How AI changes what software companies build, charge for and deliver.
The conversation peaked in May, then declined steadily through September and is down another 11% over the last 30 days. The evidence shifted from broad disruption claims toward operating proof: ElevenLabs cut usage prices, Intercom paired Fin with renewed help desk investment, and Salesforce reported stronger seats, upgrades and agentic usage.
Posts to understand this · as of Oct 7
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Lovable | 59 |
| 6 | ZoomInfo | 50 |
| 7 | Nooks | 48 |
| 8 | Replit | 57 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Gong | 65 |
How companies build trust and stand out when AI makes content cheap and abundant.
Brand and authenticity briefly recovered in August, then dropped sharply in September; the L30 is down 27.6%. August’s bump centered on AI authorship anxiety, from Ann Handley’s critique of detection culture to Clay’s public writing policy, but that concentrated debate did not sustain broader conversation.
Posts to understand this · as of Oct 5
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 90 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 93 |
| 5 | Lovable | 59 |
| 6 | Nooks | 48 |
| 7 |  Clarify | 30 |
| 8 | Codex | 84 |
| 9 | Grok Bot | 70 |
| 10 | Substack | 53 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal agents broke out in September after months below 1%, and the L30 is up 166%. Meta’s Muse created a new commerce surface, followed by Sierra and major partners proposing the Personal Agent Protocol for business access. October’s partial bar offers early context, while the completed data and L30 already show a sharp acceleration.
Posts to understand this
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 70 |
| 2 | Codex | 84 |
| 3 | OpenClaw | 51 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 88 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Midjourney | 36 |
| 8 | Salesforce | 93 |
| 9 | Vercel | 60 |
| 10 | ElevenLabs | 55 |
How people and agents share work, hand off tasks and make decisions together.
Multi-Player AI spiked in May around Dust’s case for shared human-agent systems, then settled into a lower, unusually steady band from July through September. Grok Bot and Notion’s sub-agent handoffs kept the operating model concrete, but they did not restart the climb. The L30 move is now slightly negative.
Posts to understand this
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 93 |
| 5 | Clay | 90 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Attio | 52 |
| 8 | Granola | 51 |
| 9 | Grok Bot | 70 |
| 10 |  Viktor | 32 |
How AI changes software pricing, usage costs and gross margins.
Discussion rose from March through June, then fell each full month through September and is down 19.2% over the last 30 days. The debate has narrowed from exploding token demand to cost control: open models pushed prices down, enterprises set spending limits, and Factory reported production inference savings as routed volume grew.
Posts to understand this · as of Oct 7
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Codex | 84 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Vercel | 60 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Clay | 90 |
| 8 | Lovable | 59 |
| 9 | OpenRouter | 52 |
| 10 | Replit | 57 |
How teams track and control the cost of models, tokens and agent work.
Cost talk more than doubled from March to a July high as token volume exploded and teams wanted to see the bill. In August, Rippling's AI Spend Console tied OpenAI, Anthropic and Cursor usage to teams and roles. Share has cooled since, down 19% over 30 days, though Harvey's swing from 50% to -50% gross margin gave September its sharpest example.
Posts to understand this · as of Oct 3
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Grok Bot | 70 |
| 5 | OpenRouter | 52 |
| 6 | Salesforce | 93 |
| 7 | LangChain | 47 |
| 8 | Vercel | 60 |
| 9 | Baseten | 47 |
| 10 | Cline | 28 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
Conversation fell from March’s high, briefly rebounded in May, then softened into September; the L30 is down 35.8%. April’s marketer whiplash, June’s case for authentic product marketing, and September’s personal-brand results show the thread moving from broad frustration to concrete examples of trust earned through real voices.
Posts to understand this · as of Oct 6
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | Nooks | 48 |
| 4 | Salesforce | 93 |
| 5 | HubSpot | 88 |
| 6 | Lovable | 59 |
| 7 | Ahrefs | 50 |
| 8 | Grok Bot | 70 |
| 9 |  Attention | 30 |
| 10 | Clarify | 30 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context Engineering in GTM rose steadily from March to a June high, then declined through September; L30 is essentially flat at plus 0.6%. The lower plateau still has concrete product support: Clay combines CRM, usage, calls, email, and web signals, while the broader discussion has shifted from prompt craft toward persistent context and agent harnesses.
Posts to understand this · as of Oct 6
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 93 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | HubSpot | 88 |
| 5 | Codex | 84 |
| 6 | Grok Bot | 70 |
| 7 | Profound | 53 |
| 8 | Clay | 90 |
| 9 | Apify | 52 |
| 10 | Granola | 51 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR conversation declined steadily from March through July, saw a modest August lift, then weakened again, with the last 30 days down 6.7%. The pattern moved from broad replacement claims and Ava 2.0’s autonomous BDR launch toward narrower operating proof, such as ElevenLabs using its own voice-based AI SDR for inbound.
Posts to understand this · as of Oct 8
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Clay | 90 |
| 3 | Claude Code | 99 |
| 4 | Lovable | 59 |
| 5 | Grok Bot | 70 |
| 6 | HubSpot | 88 |
| 7 | Instantly | 63 |
| 8 | Nooks | 48 |
| 9 |  Outreach | 46 |
| 10 | Attio | 52 |
Growth driven by people using the product before they talk to sales.
Product-Led Growth fell steadily from March through July, then stabilized in August and September; L30 is now up 14.9%. The recent lift has no single launch behind it: PostHog’s generous free tier supports renewed free-plan interest, while the broader discussion frames PLG and enterprise sales as motions companies eventually combine.
Posts to understand this · as of Oct 6
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Lovable | 59 |
| 5 | Replit | 57 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Nooks | 48 |
| 8 | Vercel | 60 |
| 9 | Ahrefs | 50 |
| 10 | Canva | 49 |
Low-quality AI content and the fight to make automated work worth reading.
AI Slop climbed sharply in April and held near its high through June, then cooled unevenly, with an August bounce followed by a steeper September drop. The conversation shifted from broad frustration toward operating fixes: stronger context, governance, and repeatable Claude workflows. That practical turn has not stopped the decline, with L30 down 5.7%.
Posts to understand this
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Codex | 84 |
| 5 | Salesforce | 93 |
| 6 | Webflow | 48 |
| 7 | Grok Bot | 70 |
| 8 | Midjourney | 36 |
| 9 | Substack | 53 |
| 10 |  Vector | 37 |
The argument that agents and custom software will break the classic SaaS model.
SaaSpocalypse discussion declined from March through August, then held roughly flat in September. The 2% L30 increase suggests stabilization, not a renewed surge. Concrete results weakened the replacement thesis: Salesforce reported growing seats and low attrition, Gong passed $500 million ARR, and beehiiv still buys core SaaS despite its ability to build.
Posts to understand this · as of Oct 7
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 50 |
| 6 |  Monaco | 25 |
| 7 | Attio | 52 |
| 8 | Clarify | 30 |
| 9 | Gong | 65 |
| 10 | Apify | 52 |
The choice between building software internally and buying another product.
Build-vs-buy discussion fell steadily from March through July, then held near 1% share in August and September; the L30 move is essentially flat. Recent posts frame the current debate around marketers and salespeople building their own tools, while Replit shows non-engineers using those tools in daily sales work.
Posts to understand this · as of Oct 7
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | ZoomInfo | 50 |
| 5 | Monaco | 25 |
| 6 | Claude Code | 99 |
| 7 | Apify | 52 |
| 8 |  Lightfield | 26 |
| 9 |  Momentum | 25 |
| 10 | Profound | 53 |
Ways to verify whether digital content or online activity came from a person or AI.
Conversation stayed small until an August spike around Anthropic’s EU AI Act watermarking plans and the immediate SEO debate. September gave most of that spike back, and the L30 measure is down 60.3%; Sitecore’s later C2PA workflow shows the issue narrowing from broad reaction to practical disclosure controls.
Posts to understand this
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Grok Bot | 70 |
| 3 | Claude Code | 99 |
| 4 | HeyGen | 32 |
| 5 | Granola | 51 |
| 6 | HubSpot | 88 |
| 7 | Replit | 57 |
| 8 | Runway | 36 |
| 9 | Substack | 53 |
| 10 | Vercel | 60 |
AI tools that write, edit, test and operate software alongside a human builder.
Conversation share slid steadily from 21.7% in March to 12.6% in September, with the L30 down another 18.7%. No single event explains the decline: practical launches from ColdIQ, Notion, and Databricks kept the category active, but none reversed the broader loss of attention.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 70 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Clay | 90 |
| 6 | Lovable | 59 |
| 7 | HubSpot | 88 |
| 8 | Replit | 57 |
| 9 | OpenClaw | 51 |
| 10 | Salesforce | 93 |
The frontier models and labs that provide the base layer for AI products.
Foundation-model share has moved in waves, with surges in June, July, and September rather than one sustained climb. September reached 10.6% as OpenAI hit 31% of OpenRouter spend and release cycles tightened; the L90 remains up 22.7%, though the L30 has eased 14.8%.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 70 |
| 4 | HubSpot | 88 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Salesforce | 93 |
| 7 | OpenClaw | 51 |
| 8 | OpenRouter | 52 |
| 9 | Midjourney | 36 |
| 10 | Vercel | 60 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP spiked in April and May, then cooled through the summer and recovered slightly in September. Early experimentation, Anthropic’s Stainless acquisition, and later operational connectors show adoption broadening from simple generation into governed business actions. Still, the 2.5% L30 decline leaves the conversation slightly softer, with October only partial context.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 88 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Clay | 90 |
| 7 | Grok Bot | 70 |
| 8 | Instantly | 63 |
| 9 | FullEnrich | 44 |
| 10 | Gong | 65 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO reached 7.958% in May, held near that level in June, then declined to 5.342% by September. The current L30 move is down 8.1%, despite concrete commercial proof such as Daydream’s $15 million round and a reported 25% revenue contribution from AI search, which suggests adoption persists while broad conversation cools.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Ahrefs | 50 |
| 3 | HubSpot | 88 |
| 4 | Semrush | 48 |
| 5 | Clay | 90 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 38 |
| 8 | Customer.io | 39 |
| 9 | Optimizely | 31 |
| 10 | Instantly | 63 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
Enterprise AI reached 5.5% in April, then declined gradually to 3.5% by September. The L30 is nearly flat at minus 2.7%, which suggests a lower plateau rather than a fresh break; discussion has moved from production infrastructure launches toward the harder gap between available capability and captured value.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | HubSpot | 88 |
| 5 | Nooks | 48 |
| 6 | 6sense | 41 |
| 7 | ElevenLabs | 55 |
| 8 | Grok Bot | 70 |
| 9 | OpenRouter | 52 |
| 10 |  Braze | 26 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce was nearly absent through June, rose in August, then spiked to 3.8% in September around the conference. The L30 remains up 185.7%; the first five October days are only early context. Salesforce’s Informatica debut and Crossbeam’s AgentExchange launch partnership gave the event concrete product news alongside the usual ROI debate.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Apify | 52 |
| 4 | Codex | 84 |
| 5 | ZoomInfo | 50 |
| 6 | Clay | 90 |
| 7 | Outreach | 46 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Grok Bot | 70 |
| 10 | Lightfield | 26 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps declined steadily from 4.535% in March to 2.656% in August, then flattened: September edged up and the L30 is nearly unchanged at 0.1%. The conversation now centers less on the function itself and more on its new operating choices, from rebuilding SaaS internally to Claude-based forecasting and a signal-driven RevOps playbook. October’s partial bar is only early context.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Gong | 65 |
| 6 | n8n | 59 |
| 7 | Instantly | 63 |
| 8 | Attio | 52 |
| 9 | Lovable | 59 |
| 10 | RB2B | 47 |
Measuring whether AI answers mention, cite and recommend a brand.
Share peaked at 4.0% in June, remained elevated through August, then fell to 2.7% in September. Recent posts shifted from hands-on citation tactics to doubts about tracking reliability and evidence that citations fade quickly; with October still partial, the L30 measure shows the conversation down 16.7%.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | Profound | 53 |
| 3 | Ahrefs | 50 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 88 |
| 6 | AirOps | 38 |
| 7 | Grok Bot | 70 |
| 8 |  Similarweb | 33 |
| 9 | Vector | 37 |
| 10 | Clay | 90 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid Media has moved in waves rather than one clean trend: it recovered from April, jumped in August, then gave back share in September. No single post explains the swings. The L30 and L90 moves are positive, with early October attention spanning Anthropic’s performance-marketing hire and low-cost automation for ad analysis and fatigue checks.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 90 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 63 |
| 5 | Salesforce | 93 |
| 6 | Gong | 65 |
| 7 | Granola | 51 |
| 8 | HeyReach | 52 |
| 9 | Lovable | 59 |
| 10 | Ahrefs | 50 |
Email sent to people with no prior relationship to start a sales conversation.
Cold Email reached a May high, fell sharply through July, and continued a slower decline afterward; L30 is down 7.7%. The May spike aligns with Jason Bay’s 15x reply-rate claim for direct inbox sends, while later posts narrowed the discussion to relevance, personalization, and value-first tactics rather than broad channel enthusiasm.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Instantly | 63 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 | HubSpot | 88 |
| 5 | Lemlist | 48 |
| 6 | Prospeo | 52 |
| 7 | Apollo.io | 52 |
| 8 | Codex | 84 |
| 9 | Salesforce | 93 |
| 10 | AI Ark | 46 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer success has declined from March through September, apart from a brief August lift, and the L30 is down 25.9%. The conversation moved from Rox automating renewals and expansion toward organizational consolidation at Vanta and a sharp Salesforce support failure, a pattern that puts efficiency promises beside unresolved service basics.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Lovable | 59 |
| 5 | Gong | 65 |
| 6 | Replit | 57 |
| 7 | ZoomInfo | 50 |
| 8 | Grok Bot | 70 |
| 9 |  Qualified | 25 |
| 10 | Attio | 52 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Conversation rose steadily from March through July, then dropped in August and held almost flat in September. No single event owns the curve: posts moved from Composio’s model-to-model agent tests to Vercel’s production feedback loop and Morgan’s cross-model benchmark work; the 26.2% L30 gain shows renewed momentum after that plateau.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Salesforce | 93 |
| 5 | Grok Bot | 70 |
| 6 | LangChain | 47 |
| 7 | HubSpot | 88 |
| 8 | OpenRouter | 52 |
| 9 | Vercel | 60 |
| 10 | Clay | 90 |
Voice and chat software that talks with buyers and customers.
Conversational AI climbed gradually from spring through August and held nearly flat in September, a plateau that matters because adoption evidence kept broadening. Fiserv’s planned scale to millions of voice and chat conversations, GPT-live-1’s API release, and ElevenLabs’ multilingual India pilot support the renewed 11.7% L30 rise.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | ElevenLabs | 55 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 70 |
| 5 | Instantly | 63 |
| 6 | Vector | 37 |
| 7 | Codex | 84 |
| 8 | Docket | 31 |
| 9 | LangChain | 47 |
| 10 | Midjourney | 36 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold outbound share started high, briefly rebounded in May, then fell steadily through September as the conversation moved from AI sequencing launches to the harder reality of getting buyers to engage. Recent posts return to cold-call fundamentals and buyer resistance, but the L30 move is still down 7.9%.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Instantly | 63 |
| 5 | Nooks | 48 |
| 6 | HeyReach | 52 |
| 7 | Salesforce | 93 |
| 8 | Gong | 65 |
| 9 | FullEnrich | 44 |
| 10 | Prospeo | 52 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Prospecting climbed into May, then declined across June through September; the last 30 days are down 23%. Big launches from Nooks and Salesforce with ZoomInfo helped define the earlier high, while Clay’s September API and CLI release shows attention shifting from standalone research toward agent-run prospecting workflows.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 93 |
| 4 | HubSpot | 88 |
| 5 | AI Ark | 46 |
| 6 | Instantly | 63 |
| 7 | Grok Bot | 70 |
| 8 | Apollo.io | 52 |
| 9 | Codex | 84 |
| 10 | Gong | 65 |
The debate over AI risk, alignment, regulation and responsible development.
AI safety stayed near a low baseline through August, then spiked in September; both the 30-day and 90-day views remain more than 100% higher. The rise came from several fronts at once: Mistral shipped an open moderation model, a widely shared workplace-risk post cited an agent database failure, and Microsoft elevated humanity as the constraint on superintelligence.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | beehiiv | 50 |
| 4 | Salesforce | 93 |
| 5 | Grok Bot | 70 |
| 6 | HubSpot | 88 |
| 7 | Runway | 36 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | ElevenLabs | 55 |
| 10 | Midjourney | 36 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand generation has trended down from March, with only a brief August lift before September weakened again; the L30 move is down 20.1%. No launch drove the curve. The pattern is a broader rethink of the function as zero-click research erodes capture tactics, founders change early marketing hires, and teams question lead-quality signals.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Docket | 31 |
| 6 | Gong | 65 |
| 7 | Codex | 84 |
| 8 | Instantly | 63 |
| 9 | Profound | 53 |
| 10 | Vector | 37 |
The work of connecting marketing activity to pipeline and revenue.
Attribution fell from March, bounced in May, then settled into a narrow July-to-September plateau. The 36.6% L30 move shows current interest rising as zero-click discovery makes last-touch reporting less credible, while the sustained debate centers on combining self-reported sources, buyer engagement, and later pipeline rather than claiming simple causation.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Webflow | 48 |
| 6 | Semrush | 48 |
| 7 |  Twilio | 43 |
| 8 | Docket | 31 |
| 9 | Gamma | 44 |
| 10 | Gong | 65 |
Sales and marketing coordinating around a defined set of target accounts.
ABM’s share fell from a March peak to a July low, then held roughly flat through August and September; the latest L30 reading is up 4.5%. Recent conversation centers on ABM’s economics versus PLG, launches challenging legacy account-level signals, and buying-group approaches that look beyond individual leads.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 90 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 93 |
| 5 | Instantly | 63 |
| 6 | 6sense | 41 |
| 7 | Nooks | 48 |
| 8 | FullEnrich | 44 |
| 9 | Codex | 84 |
| 10 | HeyReach | 52 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Data enrichment trended down from March through September, with the 90-day view still off 39%. The last 30 days are up 7%, and Gong Enrich supplies a concrete current catalyst by bringing ten named third-party providers into Gong; earlier Clay moves show enrichment becoming infrastructure inside broader workflows rather than the whole product.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Instantly | 63 |
| 5 | Salesforce | 93 |
| 6 | AI Ark | 46 |
| 7 | Prospeo | 52 |
| 8 | Codex | 84 |
| 9 | Apollo.io | 52 |
| 10 |  BetterContact | 42 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
AI video generation rose in April, slid through July, then jumped in August and held close to that level in September. H3 Max’s faster-than-real-time launch and Higgsfield’s placement inside existing creative tools gave the category concrete catalysts; the L30 has eased 6.9%, even as HeyGen framed a persistent small-business production barrier.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Runway | 36 |
| 3 | Grok Bot | 70 |
| 4 | HeyGen | 32 |
| 5 | Replit | 57 |
| 6 | Salesforce | 93 |
| 7 | Claude Code | 99 |
| 8 | HubSpot | 88 |
| 9 | ElevenLabs | 55 |
| 10 |  Synthesia | 25 |
Mapping and winning the committee of people involved in a business purchase.
Buying Groups dropped sharply after March, recovered partway in May, then settled near a lower plateau before another step down in August. September held that level and the L30 measure is up 6.6%, suggesting durable attention to committee deals rather than a breakout, supported by practical playbooks for multithreading, tailored assets, and procurement.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | AI Ark | 46 |
| 6 |  BuiltWith | 33 |
| 7 | HeyReach | 52 |
| 8 | Instantly | 63 |
| 9 | RB2B | 47 |
| 10 | Vector | 37 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
GTM Data Infrastructure declined from March through May, rebounded in June, then fell each completed month through September. The L30 measure is down another 13.4%, while the first eight October days provide only early context. The posts show consolidation and interface change: Pocus joined Apollo, Salesforce connected CRM data to Claude, and RevOps stacks shifted toward agents and orchestration.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Gong | 65 |
| 6 | Attio | 52 |
| 7 | Nooks | 48 |
| 8 | n8n | 59 |
| 9 | Codex | 84 |
| 10 | Grok Bot | 70 |
The training, fine-tuning and modeling work underneath AI products.
Machine learning rose steadily from July through September, supported by concrete model progress in robotics and world-action systems. Skild AI introduced one-shot task learning, Black Forest Labs paired stronger benchmark results with fewer parameters, and AMD’s World Labs deal tied model development more closely to hardware; L30 remains up 5.9%.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | LangChain | 47 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Grok Bot | 70 |
| 6 | Baseten | 47 |
| 7 | OpenRouter | 52 |
| 8 | Vercel | 60 |
| 9 | Cline | 28 |
| 10 | OpenClaw | 51 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise Sales has trended down from March, with only a brief August lift before another September decline. No single event explains the curve. The posts show attention concentrating around production readiness, moving consumer adoption upmarket, and the craft behind large deals; the L30 move is only slightly positive against a weaker 90-day trend.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Salesforce | 93 |
| 3 | HubSpot | 88 |
| 4 | Clay | 90 |
| 5 | 6sense | 41 |
| 6 | Gong | 65 |
| 7 | Lovable | 59 |
| 8 | 1mind | 37 |
| 9 | Clarify | 30 |
| 10 | Claude Code | 99 |
People asking AI assistants for answers instead of using a traditional search engine.
AI Search discussion built from April to a June high, then declined for three straight months. AutoRFP’s reported ChatGPT traffic gains helped make the channel tangible early, while later evidence split Google ranking from AI citations. Even strong September claims about AI Overviews cutting clicks did not arrest the cooling, and L30 is down 22.7%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | Profound | 53 |
| 3 | Ahrefs | 50 |
| 4 | HubSpot | 88 |
| 5 | Clay | 90 |
| 6 | Gamma | 44 |
| 7 | Gong | 65 |
| 8 | 6sense | 41 |
| 9 |  AthenaHQ | 19 |
| 10 | Clarify | 30 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability rose steadily to a May peak, declined through July, briefly recovered in August, then softened again. With L30 down 31% and L90 down 17.2%, no single event explains the curve; attention follows recurring operational pain, infrastructure deals like Infobip buying SocketLabs, and practical guidance on authentication, reputation, and spam placement.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Instantly | 63 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Prospeo | 52 |
| 6 | Apollo.io | 52 |
| 7 | Lemlist | 48 |
| 8 | Salesforce | 93 |
| 9 | ZoomInfo | 50 |
| 10 | AI Ark | 46 |
Programmable tools used to build custom go-to-market systems, agents and automations.
Share accelerated into a May high as Claude Code became a programmable layer for cold email and connected GTM stacks. It then declined through August and stabilized slightly in September; the 27.7% L30 drop shows that October’s early stack discussion has not yet rebuilt the spring momentum.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Prospeo | 52 |
| 2 | FullEnrich | 44 |
| 3 | Clay | 90 |
| 4 | Instantly | 63 |
| 5 | HubSpot | 88 |
| 6 | Claude Code | 99 |
| 7 | AI Ark | 46 |
| 8 |  Findymail | 41 |
| 9 | BetterContact | 42 |
| 10 | HeyReach | 52 |
The choice of go-to-market motion and the plan for making it work.
GTM Strategy peaked in May, then lost share through September; the L30 move is down another 24%. No single event drove the slide. The posts instead trace a shift toward AI-owned and builder-led motions, from Swan AI’s agent workflows and Intercom’s Fin to Notion’s workflow-first account model.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | Nooks | 48 |
| 4 | Salesforce | 93 |
| 5 | HubSpot | 88 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Gong | 65 |
| 8 | Apollo.io | 52 |
| 9 | Attio | 52 |
| 10 |  Docusign | 34 |
How companies create demand, build trust and reach buyers at other businesses.
B2B marketing fell hard from March to April, stabilized through June, then moved to a lower band from July through September. No single launch explains the decline. The posts show a fragmented playbook across paid, AI search, founder social, creators, and human credibility, while the L30’s 2.6% gain suggests stabilization rather than a clear comeback.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Claude Code | 99 |
| 4 | Webflow | 48 |
| 5 | Clay | 90 |
| 6 | Customer.io | 39 |
| 7 | Gong | 65 |
| 8 | Optimizely | 31 |
| 9 |  Primer | 27 |
| 10 | Profound | 53 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
HubSpot UNBOUND had two event-led bursts: the April rebrand announcement, then a much larger September surge around the Boston conference. The September peak was backed by 1,300 partners and roughly 13,000 attendees; L30 share is still up 105.1%, while the first eight October days are only early context.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 90 |
| 3 | Salesforce | 93 |
| 4 | Claude Code | 99 |
| 5 | Profound | 53 |
| 6 | Apify | 52 |
| 7 |  Breeze | 24 |
| 8 | Lightfield | 26 |
| 9 | Vector | 37 |
| 10 | ZoomInfo | 50 |
The durable knowledge and memory an agent can use across tasks and sessions.
Agent memory rose steadily into June, then dropped hard in August and stayed nearly flat in September. The evidence moved from personal second-brain systems toward shared, continuously refreshed company context, including ZoomInfo data inside Slack and current account relationships. L30 is up 16.1%, pointing to renewed attention after that lower plateau.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Cursor (Anysphere) | 77 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Profound | 53 |
| 6 | Attio | 52 |
| 7 | Gong | 65 |
| 8 | Grok Bot | 70 |
| 9 | Vercel | 60 |
| 10 | Apify | 52 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence slid from 1.682% in March to 0.894% in June, rebounded to 1.494% in July, then eased through September. The L30 is nearly flat at -0.5%, while September’s conversation centered on two revenue orchestration leader placements and Momentum’s role in Salesforce Hunter’s data foundation.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 65 |
| 2 | Salesforce | 93 |
| 3 | HubSpot | 88 |
| 4 | Clay | 90 |
| 5 | Outreach | 46 |
| 6 |  Salesloft | 41 |
| 7 | Claude Code | 99 |
| 8 | Grok Bot | 70 |
| 9 | Lovable | 59 |
| 10 | Clarify | 30 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales Leadership held near 2.3% in April and May, then declined steadily; its L30 share is down 12.7%. The conversation has narrowed around what leaders do directly: Replit wants a hands-on VP of Sales, while other posts stress spotting talent early and retaining reps long enough to build expertise.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Gong | 65 |
| 3 | HubSpot | 88 |
| 4 |  MoEngage | 22 |
| 5 |  TitanX | 32 |
| 6 | 6sense | 41 |
| 7 | Airtable | 48 |
| 8 | Claude Code | 99 |
| 9 | Clay | 90 |
| 10 | Codex | 84 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Conversation peaked in April, declined steadily through August, then leveled off in September; the last 30 days rose 4.6%. Recent discussion spans Ami’s GTM agent launch, Gong’s custom revenue workflows, and an early human-versus-agent outbound test, showing renewed activity across product launches and practical execution.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Nooks | 48 |
| 4 | Clay | 90 |
| 5 |  Sumble | 32 |
| 6 |  Rox | 31 |
| 7 | HubSpot | 88 |
| 8 | Attention | 30 |
| 9 | Clarify | 30 |
| 10 |  Clearskies | 21 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search Strategy climbed sharply into June, then gave back share across July, August, and September; the L30 move is down 22.3%. The decline sits alongside a broader challenge to old search assumptions: zero-click behavior weakens owned traffic, broad keywords miss revenue intent, and AI citation counts can reward spam that Google removes.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | HubSpot | 88 |
| 3 | Semrush | 48 |
| 4 | Similarweb | 33 |
| 5 |  SparkToro | 28 |
| 6 | AirOps | 38 |
| 7 | LangChain | 47 |
| 8 | 6sense | 41 |
| 9 |  Browser Use | 27 |
| 10 | Claude Code | 99 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product marketing dropped sharply after March, then held near 1.5% to 1.8% from May through August before another September decline. No single event explains the slide. The strongest spring conversation recast the work around marketing engineers, while later posts returned to practical launch discipline rather than a fresh category-wide catalyst.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Profound | 53 |
| 4 | Gong | 65 |
| 5 | Ahrefs | 50 |
| 6 | Lovable | 59 |
| 7 | Optimizely | 31 |
| 8 | Salesforce | 93 |
| 9 | Apify | 52 |
| 10 | Codex | 84 |
How companies sell to other companies and how business buyers make decisions.
B2B sales conversation has oscillated rather than followed one clean arc, with a May rebound, softer summer levels, and a September decline. The last 30 days are nearly flat at down 2%; the tension is between AI systems that organize deals and research, and a renewed push for events, direct mail, and trusted human contact.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | 6sense | 41 |
| 5 | Claude Code | 99 |
| 6 |  DemandScience | 27 |
| 7 | Hermes Agent | 37 |
| 8 | OpenClaw | 51 |
| 9 | Ploy | 26 |
| 10 | Ahrefs | 50 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting hit a May high, then settled into a lower range and declined another 14.6% in the L30. No single event explains the slide. The posts show forecasting absorbed into wider systems for deal execution and AI-directed revenue work, from HockeyStack’s revenue agents to Apollo’s intelligence layer and workflow builder.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Gong | 65 |
| 5 | Claude Code | 99 |
| 6 | n8n | 59 |
| 7 |  Clari | 33 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Granola | 51 |
| 10 | Grok Bot | 70 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing stayed elevated but uneven through June, dropped in July, briefly recovered in August, then stepped down sharply in September; the L30 is down 34.7%. The posts point to a shift away from content volume toward operating systems, original customer knowledge, and credible third-party voices, which narrows the old production-led conversation.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 | Ahrefs | 50 |
| 5 | Customer.io | 39 |
| 6 | Grok Bot | 70 |
| 7 | Semrush | 48 |
| 8 | HeyReach | 52 |
| 9 | Instantly | 63 |
| 10 | Nooks | 48 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement has trended down since March, despite a brief July lift, with August and September extending the decline and the L30 down another 12.2%. No single event explains the curve: the conversation spans a persistent coaching gap, Vanta’s measured Hyperbound results, and Mindtickle’s push toward AI and agentic enablement.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Gong | 65 |
| 3 | Customer.io | 39 |
| 4 | Claude Code | 99 |
| 5 | Clay | 90 |
| 6 | Cursor (Anysphere) | 77 |
| 7 |  Highspot | 29 |
| 8 | Instantly | 63 |
| 9 | Nooks | 48 |
| 10 | Salesforce | 93 |
Starting and running a business, including the economics and experience of the founder path.
Entrepreneurship held in a fairly narrow band through June, dipped in July, bounced in August, then eased again in September. No single event explains the shape: the conversation came from varied operator stories, including YouSpot for one-person businesses, Tenex’s bootstrapped hiring, and Tally reaching $6 million ARR; L30 is down 31.1%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Substack | 53 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 93 |
| 5 | 6sense | 41 |
| 6 |  Amp | 18 |
| 7 | Claude Code | 99 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Exa.ai | 46 |
| 10 |  Harmonic | 21 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing climbed from March through August, then held nearly flat in September. Devin Fusion’s hybrid harness, OpenRouter’s move to Stripe, and Harvey’s reported margin collapse gave the rise concrete product and economic anchors. The 31.9% L30 decline shows the sustained summer build has cooled recently.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Grok Bot | 70 |
| 5 | Codex | 84 |
| 6 | LangChain | 47 |
| 7 | OpenRouter | 52 |
| 8 | Baseten | 47 |
| 9 | Cline | 28 |
| 10 | HubSpot | 88 |
How marketing teams use AI, where it helps and how it changes the job.
After falling from March to May, conversation settled into an uneven plateau through September. September posts focus on practical constraints, working AI use cases, and whether agents build automation or become the automation; the L30 move is nearly flat, down 1.2%.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Profound | 53 |
| 4 | Lovable | 59 |
| 5 | ElevenLabs | 55 |
| 6 | Midjourney | 36 |
| 7 | Salesforce | 93 |
| 8 |  Adobe Marketo | 25 |
| 9 | AirOps | 38 |
| 10 |  Aurasell | 19 |
B2B brands paying creators and independent voices to reach trusted audiences.
After falling in April, share climbed to a June peak, dipped in July, rebounded in August, then fell in September; L30 is down 6.7%. Demandbase’s May hiring and AirOps’ June creator panel track the climb, while Limelight’s September results show established brand-deal activity even as conversation cooled.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | ElevenLabs | 55 |
| 3 | HubSpot | 88 |
| 4 | Gamma | 44 |
| 5 | HeyReach | 52 |
| 6 | Lovable | 59 |
| 7 | Replit | 57 |
| 8 | Claude Code | 99 |
| 9 | FullEnrich | 44 |
| 10 | Granola | 51 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth Marketing fell hard from March to April, then drifted lower through August before a modest September rebound. The L30 measure is down 11.9%, so that bounce has not held. The pattern reflects a broader reframing from channel optimization toward AI-assisted product work, GTM engineering, and higher experiment volume.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Ahrefs | 50 |
| 3 | Webflow | 48 |
| 4 | Optimizely | 31 |
| 5 | Profound | 53 |
| 6 | beehiiv | 50 |
| 7 | AirOps | 38 |
| 8 | Claude Code | 99 |
| 9 | Clay | 90 |
| 10 | Nooks | 48 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Headless software spiked sharply in April, fell through July, then rebuilt share across August and September. No supplied post explains the April jump, but the recent 11.9% L30 rise has a clear pattern: Salesforce opened capabilities through APIs and MCP, while Lovable and internal GTM teams put those interfaces to work across existing systems.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Apify | 52 |
| 6 | Firecrawl | 40 |
| 7 | ZoomInfo | 50 |
| 8 | Exa.ai | 46 |
| 9 | Lightfield | 26 |
| 10 | Clarify | 30 |
The software stack marketers use to plan, run, measure and improve their work.
Martech was nearly flat from March through May, stepped down in June and July, bounced in August, then softened again; the L30 is down 25.7%. No launch explains the curve. The sustained pattern is stack compression: concern about agent sprawl is pushing the conversation from adding tools toward architecture, governance, and fewer software layers.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 |  GrowthLoop | 29 |
| 3 | Salesforce | 93 |
| 4 | Cursor (Anysphere) | 77 |
| 5 |  Hootsuite | 21 |
| 6 | Salesloft | 41 |
| 7 | Twilio | 43 |
| 8 |  Zeta | 21 |
| 9 |  allGood | 19 |
| 10 |  ActiveCampaign | 32 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing automation declined from March through June, then found a floor and rose across the third quarter. The last 30 days are up 38.8%, supported by a broader reset: HubSpot launched agentic workflows, while operators questioned legacy stacks, mounting tool inertia, and platforms built around forms, scoring, and MQLs.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | ActiveCampaign | 32 |
| 4 | Grok Bot | 70 |
| 5 | GrowthLoop | 29 |
| 6 | Twilio | 43 |
| 7 | Adobe Marketo | 25 |
| 8 | Apollo.io | 52 |
| 9 | Attio | 52 |
| 10 | Claude Code | 99 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent Skills peaked in May, then declined across the following full months, with the L30 measure down 22.7%. Neither Vercel’s open agent plugin standard nor practical Claude skills for advertising and OKR reviews reversed that slide. The pattern suggests strong utility inside specific workflows, but less broad conversation after the May burst.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 93 |
| 4 | Codex | 84 |
| 5 | Clay | 90 |
| 6 | Nooks | 48 |
| 7 | Optimizely | 31 |
| 8 | Customer.io | 39 |
| 9 |  Fathom | 32 |
| 10 | FullEnrich | 44 |
Scoring leads and accounts to decide who deserves attention first.
Lead scoring fell sharply from May through September, and remains down 45% over 90 days. The last 30 days are up 8%, but the evidence points to a changing method, not a clean comeback: teams are testing richer persona pipelines and real-time buyer interaction while questioning simple behavioral scores.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 90 |
| 3 | Salesforce | 93 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 63 |
| 6 | Codex | 84 |
| 7 | Docket | 31 |
| 8 | Gong | 65 |
| 9 | Grok Bot | 70 |
| 10 | Hootsuite | 21 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Exec-led and employee-led social held remarkably steady from April through August, then lost ground in September. The L30 is still down 6%, so early October’s higher bar is context, not a reversal. The posts point to a durable playbook, with personal authority, funnel roles, and idea ownership replacing broad calls for consistency.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 90 |
| 3 | HubSpot | 88 |
| 4 | Grok Bot | 70 |
| 5 | HeyReach | 52 |
| 6 | Instantly | 63 |
| 7 | Lovable | 59 |
| 8 | RB2B | 47 |
| 9 | Apify | 52 |
| 10 | Nooks | 48 |
The point where a product solves a real need for a market that will buy it.
Product-market fit discussion peaked in April, declined into July, then held nearly flat across August and September. The last 30 days are up 20%, but no single launch explains the move; the conversation spans better measures of product love, new deep-tech funding assumptions, and ClickUp’s claim that AI shortens PMF refresh cycles.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | Granola | 51 |
| 4 | HeyReach | 52 |
| 5 | HubSpot | 88 |
| 6 | Lovable | 59 |
| 7 | Ahrefs | 50 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Customer.io | 39 |
| 10 |  Fireflies | 36 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting rose steadily from March to a June high, then declined each month through September. June’s offer-design release matched the high by arguing that weak offers, not headlines, often cause conversion problems; later posts widened that critique to positioning, audience definition, and AI briefing. The L30 is still down 10.8%, so early October context does not establish a reversal.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Instantly | 63 |
| 4 | Clay | 90 |
| 5 | HeyReach | 52 |
| 6 | Midjourney | 36 |
| 7 | AI Ark | 46 |
| 8 | BetterContact | 42 |
| 9 | Codex | 84 |
| 10 | Findymail | 41 |
Systems where several agents divide a job, coordinate their work and combine the result.
Multi-agent systems rose into May, then lost share almost every month through September; no single post explains that long slide. Workato’s Airo expansion and Mercor’s five-hour, 100-plus-subagent diligence run gave the category concrete enterprise proof, and the L30 move has turned up 26.1% even though the 90-day trend remains down.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Grok Bot | 70 |
| 5 | Salesforce | 93 |
| 6 | LangChain | 47 |
| 7 | Zapier | 53 |
| 8 | OpenClaw | 51 |
| 9 | Vercel | 60 |
| 10 | n8n | 59 |
Teams building internal software with AI instead of buying another SaaS product.
The topic fell sharply from April through June, then settled into a narrower July-to-September range. The L30 is up 22.9%, with early October showing Replit’s sales-led internal tooling example, but the broader evidence is a live buy-versus-build argument: cheaper creation meets maintenance, security, support, and opportunity-cost concerns.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Monaco | 25 |
| 6 | ZoomInfo | 50 |
| 7 | Lovable | 59 |
| 8 | Momentum | 25 |
| 9 | Qualified | 25 |
| 10 |  Base44 | 21 |
AI agents that create, launch, buy and optimize advertising.
AI-driven advertising rose steadily from May through August and stayed near that level in September, which points to category formation rather than a single spike. The last 30 days are up 38.4% as ChatGPT Ads scaled past a $1 billion annualized run rate and new formats emerged for both conversational discovery and AI crawlers.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Granola | 51 |
| 3 | Lovable | 59 |
| 4 | Salesforce | 93 |
| 5 | Clay | 90 |
| 6 | Grok Bot | 70 |
| 7 | Similarweb | 33 |
| 8 | Codex | 84 |
| 9 |  Criteo | 21 |
| 10 | Cursor (Anysphere) | 77 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
CLIs for GTM climbed unevenly into a July high after Clay launched its API, CLI, and agent plugin, then settled into a lower August-September plateau. That plateau still sat well above March, showing the interface shift had legs beyond launch week. The L30 is now down 23.6%, and October’s partial bar is only early context.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Salesforce | 93 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | HubSpot | 88 |
| 7 | Grok Bot | 70 |
| 8 | AI Ark | 46 |
| 9 | Apify | 52 |
| 10 | Attio | 52 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing operations has followed a long contraction, from 2.075% in March to 0.617% in September, with L30 down 31.0%. The posts point to a fragmented debate rather than one catalyst: agent sprawl, Conversion’s campaign agents, and the gap between fast-moving martech and slower organizational change.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Salesloft | 41 |
| 4 | allGood | 19 |
| 5 | Docket | 31 |
| 6 | Grok Bot | 70 |
| 7 | MoEngage | 22 |
| 8 | Adobe Marketo | 25 |
| 9 | Claude Code | 99 |
| 10 | Clay | 90 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
Conversation peaked in May, then lost ground through July and stayed near that lower level into September; the L30 move remains down 3.8%. The earlier lift came from concrete pricing shifts across Salesforce, ServiceNow, Clay, HubSpot, Anthropic, SAP, and monday.com, while Moltsets now supplies a sharp unlimited-price counterpoint.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Lovable | 59 |
| 4 | Replit | 57 |
| 5 | Nooks | 48 |
| 6 | Supabase | 48 |
| 7 | Vercel | 60 |
| 8 | Clay | 90 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Exa.ai | 46 |
AI agents that discover, compare and buy products on a person's behalf.
After falling from March through May, agents as buyers briefly recovered in June, softened through August, then rose in September. The 42.2% L30 increase has a clear commercial pattern behind it: Meta’s Muse added Klaviyo, while Shopify partnered with Muse to bring Shop Pay checkout across Shopify stores.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 |  Browserbase | 33 |
| 2 | Vercel | 60 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Exa.ai | 46 |
| 5 | Salesforce | 93 |
| 6 | HubSpot | 88 |
| 7 | Lovable | 59 |
| 8 |  Artlist | 15 |
| 9 |  Bolt.new (StackBlitz) | 23 |
| 10 | Clarify | 30 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
The conversation peaked in April around moving from individual tools to AI-centered operating processes, then shifted toward pressure for leaner, automation-heavy teams. Share fell through July, briefly rebounded in August, and resumed declining in September; the 31% L30 drop comes as recent discussion turns to hiring and developing people while the technology changes weekly.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 | ElevenLabs | 55 |
| 5 | Granola | 51 |
| 6 | HubSpot | 88 |
| 7 | Lovable | 59 |
| 8 | Salesforce | 93 |
| 9 | Vercel | 60 |
| 10 | beehiiv | 50 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Partner Marketing & Ecosystem stepped up in August and held nearly flat in September, after Snowflake highlighted 200%+ growth with Dataiku and operators pushed always-on partner demand generation. Lovable’s September partner program gave the plateau a concrete launch, but momentum has softened 21.1% over the last 30 days; October’s lower bar covers only seven days.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 93 |
| 4 | Lovable | 59 |
| 5 | Replit | 57 |
| 6 | Instantly | 63 |
| 7 | AI Ark | 46 |
| 8 | Apollo.io | 52 |
| 9 | Aurasell | 19 |
| 10 | Canva | 49 |
A go-to-market operating model where agents execute work across the revenue motion.
Agentic GTM has swung rather than climbed steadily: April spiked, May reset, and August rebuilt share before September softened. Clay’s $115 million round and growth-agent thesis gave the model a concrete center, while BCG’s adoption gap and agent-sprawl concerns kept the operating questions alive; the 90-day gain remains positive, but the last 30 days are down 16.5%.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 90 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Codex | 84 |
| 5 | 6sense | 41 |
| 6 | Attio | 52 |
| 7 | HubSpot | 88 |
| 8 | Salesforce | 93 |
| 9 | ZoomInfo | 50 |
| 10 | 1mind | 37 |
Multi-step work planned and executed by agents instead of fixed automation rules.
Conversation share fell from May through August, then rebounded in September; October is still partial and should not be read as a completed month. The L30 measure is up 58.3%, alongside fresh discussion of Clay’s planning agent, Aurasell’s 67-agent sales model, and Macroscope’s customer-lifecycle workflows, while L90 remains down 12.1%.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Grok Bot | 70 |
| 3 | Salesforce | 93 |
| 4 | Clay | 90 |
| 5 | Codex | 84 |
| 6 | Gong | 65 |
| 7 | 6sense | 41 |
| 8 | Apollo.io | 52 |
| 9 | Claude Code | 99 |
| 10 |  Demandbase | 30 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales Ops climbed from March to a May high, then lost ground through summer and dropped sharply in September. The L30 measure is down 31.7%, while the first eight October days offer only early context. The conversation moved from Rox’s revenue automation launch toward sharper debates about rep and SDR compensation design.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 90 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 93 |
| 5 | Vercel | 60 |
| 6 | n8n | 59 |
| 7 | Airtable | 48 |
| 8 | Clari | 33 |
| 9 | Codex | 84 |
| 10 | Conductor | 26 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Conversation share fell 69% from March through September as SDR hiring contracted and the traditional SDR-to-AE handoff came under pressure. The last 30 days edged up 0.8%, alongside fresh signs that SDR demand is returning, though the same promotion and retention problems remain.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 65 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 | Nooks | 48 |
| 5 | Outreach | 46 |
| 6 | Salesforce | 93 |
| 7 | FullEnrich | 44 |
| 8 | HubSpot | 88 |
| 9 |  Unify | 33 |
| 10 | Apollo.io | 52 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
Event conversation has stayed volatile: a March high gave way to an April trough, followed by rebounds in May and July before another September dip. The L30 is up 5% and the L90 up 35%. Community meetups and hackathons supplied momentum, while October’s early discussion centers on proving event-influenced revenue.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Lovable | 59 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Substack | 53 |
| 5 | Apify | 52 |
| 6 | Customer.io | 39 |
| 7 | Gong | 65 |
| 8 | Profound | 53 |
| 9 | 6sense | 41 |
| 10 | AI Ark | 46 |
Tracing and monitoring what a model or agent did during a production run.
Observability stayed choppy but gained ground in August and September, with the L30 up 40%. The rise reflects a move from standalone monitoring toward integrated control planes: Cloudflare combined AI Gateway and Workers AI, while CrewAI’s enterprise experience exposed resistance to buying separate products for orchestration, memory, and observability.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Clay | 90 |
| 5 |  Kiro | 23 |
| 6 | Salesforce | 93 |
| 7 | Vercel | 60 |
| 8 | Attention | 30 |
| 9 | Browserbase | 33 |
| 10 | Clarify | 30 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Conversation peaked in May, then declined through September, with the latest 30 days down another 33.6%. Recent posts narrow the discussion to product feedback, skepticism about loosely defined FDE work, and the customer-facing judgment companies now seek when hiring.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Braze | 26 |
| 3 | Nooks | 48 |
| 4 | Claude Code | 99 |
| 5 | Clay | 90 |
| 6 | Codex | 84 |
| 7 | Gong | 65 |
| 8 | Lovable | 59 |
| 9 | Attio | 52 |
| 10 | Cursor (Anysphere) | 77 |
The work of earning awareness, trust and preference for a company over time.
Brand Building held near 1% from March through June, slipped in July, recovered in August, then fell hard in September. The L30 measure is down another 46.4%; the first eight October days do not establish a recovery. The posts point to a persistent budget problem: brand creates value that click-based attribution often misses.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | HubSpot | 88 |
| 3 | Nooks | 48 |
| 4 | Optimizely | 31 |
| 5 | Salesforce | 93 |
| 6 | Semrush | 48 |
| 7 | 6sense | 41 |
| 8 | Braze | 26 |
| 9 |  Buffer | 24 |
| 10 | Claude Code | 99 |
Approval and review steps that keep a person involved in an agent's work.
Human-in-the-loop discussion has swung between bursts rather than built a steady climb, with lifts in May and August followed by pullbacks. The L30 is down 27.7%. The durable thread is greater specificity about oversight: how much autonomy agents receive, which approvals remain, and how expertise and review time shape each human checkpoint.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Instantly | 63 |
| 3 | Attio | 52 |
| 4 | Clay | 90 |
| 5 | HubSpot | 88 |
| 6 | Outreach | 46 |
| 7 | Salesforce | 93 |
| 8 | AI Ark | 46 |
| 9 | Apollo.io | 52 |
| 10 | Codex | 84 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Content production at scale rose to a May high, then declined across June through September. The last 30 days are down another 5%, close to a plateau; the discussion has moved from sheer output toward control, with teams focused on optimization systems, video coherence, and the search penalties attached to AI spam.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Apify | 52 |
| 2 | Ahrefs | 50 |
| 3 | Claude Code | 99 |
| 4 | Lovable | 59 |
| 5 | AirOps | 38 |
| 6 | Exa.ai | 46 |
| 7 | Fireflies | 36 |
| 8 | Grok Bot | 70 |
| 9 | HubSpot | 88 |
| 10 | Ploy | 26 |
A shared revenue knowledge layer that people and agents can query and update.
GTM Brain jumped in June and has held a much higher band since, with L90 share up 39.3% and L30 nearly flat at plus 1.3%. The plateau matters because the idea has moved from concept to operating architecture: Swan AI connects 120-plus agents to one brain, while teams describe unified systems readable by agents.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Apify | 52 |
| 4 | Grok Bot | 70 |
| 5 | HubSpot | 88 |
| 6 | Instantly | 63 |
| 7 |  Octave | 31 |
| 8 | ZoomInfo | 50 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Gong | 65 |
Websites and docs structured so AI crawlers and agents can read and use them.
The topic reached its high in April, then faded into a stable July-September band; L30 share is down another 10.3%. The shape reflects an unresolved debate rather than one launch: Google advised standard SEO over AI-specific files, while Scott Brinker described parallel agent-ready experiences and CHEQ added crawler visibility.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | Peec AI | 28 |
| 3 | Semrush | 48 |
| 4 | Claude Code | 99 |
| 5 | Codex | 84 |
| 6 | Gamma | 44 |
| 7 | HubSpot | 88 |
| 8 | Profound | 53 |
| 9 | Webflow | 48 |
| 10 | AirOps | 38 |
Deciding what to build, why it matters and which product bets come first.
Product strategy has moved in waves, with highs in March and May followed by a lower, unusually steady band from July through September. The L30 is up 8.2%, but no single event explains the curve. The evidence spans roadmap pressure from AI, the upstream role of product marketing, and Automation Anywhere’s agreement to acquire Boost.ai.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Claude Code | 99 |
| 5 | Intercom | 44 |
| 6 | OpenRouter | 52 |
| 7 | Substack | 53 |
| 8 | Supabase | 48 |
| 9 | Vercel | 60 |
| 10 | AirOps | 38 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-Serve fell hard from March through May, stabilized at a lower level through August, and weakened again in September; the L30 move is down 11.3%. The posts show a split market: Airtable is framed as a warning about abandoning PLG, while Metronome reports a surge after opening self-serve and 1up describes AI-led buyer control.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 93 |
| 3 | Replit | 57 |
| 4 | Clay | 90 |
| 5 | Lovable | 59 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Vercel | 60 |
| 8 | Ahrefs | 50 |
| 9 | Apollo.io | 52 |
| 10 | Base44 | 21 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
Conversation moved unevenly through spring, then softened after July, with the L30 down 20.6%. Viktor’s $20 million run rate and Microsoft Teams expansion, Vista’s digital-worker thesis, and an open-source company brain show steady product activity, but no single event created durable momentum.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Viktor | 32 |
| 2 | Clay | 90 |
| 3 | HubSpot | 88 |
| 4 | Attio | 52 |
| 5 | Granola | 51 |
| 6 | Grok Bot | 70 |
| 7 | Salesforce | 93 |
| 8 | Ahrefs | 50 |
| 9 | Firecrawl | 40 |
| 10 | Gong | 65 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound systems rose sharply into May, then declined across every completed month through September; the L30 is down 45.6%. Earlier attention centered on complete automated engines, including GTMskills and Rox’s account of xbow. The newest evidence pushes the other way: a deliberately manual café-sales process rejects complex tables, signals, and automated sequences.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Attio | 52 |
| 3 | HubSpot | 88 |
| 4 | TitanX | 32 |
| 5 | 6sense | 41 |
| 6 | AI Ark | 46 |
| 7 | AirOps | 38 |
| 8 |  Amplemarket | 20 |
| 9 | Apify | 52 |
| 10 |  Calendly | 39 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales Tech share rebounded in June, then fell through September; the current L30 is down 31.8%. The posts show a broad outbound tool market in June, a September push to consolidate bloated stacks, and an earlier warning that incomplete CRM data undermines sales AI, without claiming any one theme caused the curve.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 65 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Nooks | 48 |
| 5 | Outreach | 46 |
| 6 | Clarify | 30 |
| 7 | Claude Code | 99 |
| 8 | HubSpot | 88 |
| 9 | Sumble | 32 |
| 10 | Attention | 30 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI security held a narrow plateau from March through August, then dropped sharply in September. No single event explains the decline: research kept surfacing concrete risks, from Wiz’s GhostApproval flaw to Cohere’s data-leakage findings and Forrester’s focus on agent intent, but the 17.5% L30 decline shows the conversation is still thinning.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Midjourney | 36 |
| 3 | Claude Code | 99 |
| 4 | Codex | 84 |
| 5 | Grok Bot | 70 |
| 6 | Salesforce | 93 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | ElevenLabs | 55 |
| 9 | Clarify | 30 |
| 10 |  E2B | 23 |
The runtime around an agent that provides tools, state, controls and stopping rules.
Agent harnesses moved in waves, with stronger months in April, June, and August rather than one sustained climb. That cadence matches a series of concrete proofs: Anthropic’s multi-agent engineering work, DeepSeek’s open-source developer preview, and a September explainer that defined the runtime category. The 26.2% L30 increase shows current momentum despite limited early-October data.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Salesforce | 93 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | AI Ark | 46 |
| 6 |  AiSDR | 19 |
| 7 | BuiltWith | 33 |
| 8 | Clay | 90 |
| 9 | Cline | 28 |
| 10 | Common Room | 39 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium conversation fell from a May peak to a July low, then rebounded through August and September; L30 is up 26.5%. Recent posts cover ad revenue helping expand free access, valuable free plans that serve most users, and generous usage allowances that attract sign-ups.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Lovable | 59 |
| 2 | Replit | 57 |
| 3 | Salesforce | 93 |
| 4 | Canva | 49 |
| 5 | Clay | 90 |
| 6 | HubSpot | 88 |
| 7 | Attio | 52 |
| 8 | Codex | 84 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Exa.ai | 46 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
Conversation share peaked in May, then fell sharply through August before a small September rebound; the latest 30 days are down 2.8%. September posts documented point tools being dropped and Outreach deployments being replaced, while Apollo’s October launch shows broader platforms still pushing consolidation despite the softer curve.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Attio | 52 |
| 5 | Clarify | 30 |
| 6 | Claude Code | 99 |
| 7 | Common Room | 39 |
| 8 | Codex | 84 |
| 9 | Gong | 65 |
| 10 | Nooks | 48 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
Conversation climbed into a May peak as teams moved from mapping AI-first stacks to showing practical workflow-led GTM models. It dropped sharply in June, rebounded in July, then eased through August and September; the latest 30 days are down 13.9%, even as Zendesk’s dedicated GTM AI role shows active organizational commitment.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Clay | 90 |
| 3 | FullEnrich | 44 |
| 4 | Grok Bot | 70 |
| 5 | Profound | 53 |
| 6 | Substack | 53 |
| 7 | Vector | 37 |
| 8 | 1mind | 37 |
| 9 | 6sense | 41 |
| 10 |  Aligned | 26 |
Writing and structuring the instructions a model follows.
Prompt engineering declined from March through May, bounced in June, then lost more than half its share by September; the L30 measure is down another 26.0%. The evidence points to a vocabulary and architecture shift: teams want agents that tolerate weak prompts, while context, tools, and progressively loaded skills carry more of the work.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 93 |
| 3 | Clay | 90 |
| 4 | Codex | 84 |
| 5 | HubSpot | 88 |
| 6 | Attio | 52 |
| 7 | Zapier | 53 |
| 8 | Breeze | 24 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Granola | 51 |
Using AI to tailor outreach and marketing to each person at scale.
AI personalization peaked around April and May, then declined through September; the L30 is down 38.9%. The high point paired strong scale claims with restraint: Clay produced 1,800 emails in seven minutes, while LaunchDarkly narrowed roughly 1,000 accounts to 50. Iterable’s later customer result shows focused personalization still works, but not enough to reverse the broader fade.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 77 |
| 6 |  Klaviyo | 40 |
| 7 | Outreach | 46 |
| 8 | AI Ark | 46 |
| 9 | Braze | 26 |
| 10 | Findymail | 41 |
Founders running early sales themselves before handing the motion to a sales team.
An April founder story contrasted closing every early deal with $7 million ARR today. Conversation collapsed in May, recovered in June, and peaked in July alongside a free Founding Sales book offer, then eased through September; the latest 30 days are down 16.7%, while September discussion says AI can extend the founder-led phase.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | HubSpot | 88 |
| 3 | 6sense | 41 |
| 4 | Attio | 52 |
| 5 | Clarify | 30 |
| 6 | Common Room | 39 |
| 7 | Gong | 65 |
| 8 | Granola | 51 |
| 9 |  HockeyStack | 29 |
| 10 | Instantly | 63 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
Lifecycle marketing rose into a May peak, fell through August, then stabilized in September; the L30 move is up 70.8%. The renewed conversation is practical: repeated onboarding optimization, AI-assisted loyalty and customer journeys, and frustration with one-size-fits-all nurture programs.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | beehiiv | 50 |
| 4 | Apollo.io | 52 |
| 5 | Customer.io | 39 |
| 6 |  Explorium | 31 |
| 7 | Gong | 65 |
| 8 | Grok Bot | 70 |
| 9 | GrowthLoop | 29 |
| 10 | Instantly | 63 |
Time-limited access that lets a buyer test a product before paying.
Free-trial conversation fell sharply after March, recovered gradually from May through July, then dipped again in August. The L30 is up 22.2%, but the evidence is a mix of operating friction, abuse, and poor upselling rather than one launch: incentives delayed follow-up, Stripe flagged rising abuse, and premature pitches hurt trust.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Ahrefs | 50 |
| 4 | Clay | 90 |
| 5 | Gong | 65 |
| 6 | Lovable | 59 |
| 7 | AthenaHQ | 19 |
| 8 | Attio | 52 |
| 9 | Calendly | 39 |
| 10 | Clari | 33 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
The topic spiked in April, then declined steadily through September as the broad sameness critique lost momentum. The L30 move is now up 45.4%, supported by sharper evidence: major consultancies use similar AI playbooks, and a 445-homepage study found 57% average messaging overlap.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Customer.io | 39 |
| 5 |  Grammarly | 29 |
| 6 | Optimizely | 31 |
| 7 | Substack | 53 |
| 8 | Vector | 37 |
| 9 | Webflow | 48 |
How AI changes headcount, entry-level work and the jobs people still need to do.
AI-and-jobs discussion was highest in March, bounced in May, then faded through September; the L30 remains nearly flat to slightly down at -1.7%. No single event explains the curve. The durable pattern is tension between lean-team claims and contrary hiring evidence, including Microsoft marketing openings and an OpenAI SDR role that preserves human relationship work.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 70 |
| 2 | Clay | 90 |
| 3 | Lovable | 59 |
| 4 | Attention | 30 |
| 5 | Clarify | 30 |
| 6 | Claude Code | 99 |
| 7 | Clearskies | 21 |
| 8 | Nooks | 48 |
| 9 | Rox | 31 |
| 10 | Sumble | 32 |
How sales teams use AI and how it changes the work of selling.
AI in Sales rebounded in May, held roughly level in June and July, then fell sharply through August and September. The L30 measure is down 35.9%, and the evidence points to a narrative reset: launches continue, but the conversation now stresses weak fundamentals, prior AI SDR underperformance, and stronger technical skills for sellers.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Clarify | 30 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 | Gong | 65 |
| 5 | Salesforce | 93 |
| 6 | Attention | 30 |
| 7 |  CallRail | 22 |
| 8 | Clearskies | 21 |
| 9 | Cursor (Anysphere) | 77 |
| 10 |  GitHub Copilot | 36 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise marketing rose from May through an August plateau, then fell in September; the last 30 days are down 21.9%. No single launch drove the rise. The posts show a broader operating shift toward AI-specific roles, decentralized building with centralized governance, and messaging focused on production readiness, security and compliance.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Clay | 90 |
| 3 | HubSpot | 88 |
| 4 | Aurasell | 19 |
| 5 | Braze | 26 |
| 6 | Claude Code | 99 |
| 7 | Codex | 84 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Grok Bot | 70 |
| 10 | Klaviyo | 40 |
Rule-based software that moves business work through predefined steps and systems.
Workflow automation peaked in April and mostly declined afterward, with a 49.2% L30 drop confirming weaker current attention. No single event explains the slide; the posts show the framing broadening from Zapier-connected workflows and Salesforce no-code tools toward a larger agent stack that handles research, prioritization, follow-ups, and coaching.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 90 |
| 2 | Zapier | 53 |
| 3 | AI Ark | 46 |
| 4 | Ahrefs | 50 |
| 5 | AirOps | 38 |
| 6 | Airtable | 48 |
| 7 | Apollo.io | 52 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | ElevenLabs | 55 |
| 10 | Exa.ai | 46 |
Advantages that grow stronger as more people, data or participants join a product.
Network effects declined every month from March through September, and the L30 measure is down 58.6%. No single launch explains the slide. Recent posts recast the compounding advantage in more specific terms: Salesforce points to governed customer data, Clay to UGC distribution loops, and Sierra to accumulated customer conversations.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 70 |
| 4 | Salesforce | 93 |
| 5 | Clay | 90 |
| 6 | Devin | 38 |
| 7 | Granola | 51 |
| 8 | Vercel | 60 |
| 9 | beehiiv | 50 |
| 10 | Ahrefs | 50 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory peaked in April, dropped sharply into July, and has stayed near that lower floor; the L30 move is only up 1.8%, not a clear recovery. April’s concentration came from a specific debate over long-term fractional CMOs, while September’s fractional CRO case reinforced the model without restoring the earlier conversation level.
Posts to understand this · as of Oct 6
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
Open-source AI spiked in July, alongside reports that companies were adopting open models beside closed ones, then lost ground through September. Bolt Forge added a concrete usage and training program, while debate around Nvidia, OpenAI, and Anthropic kept the category contentious, but the L30 is still down 19%.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Cursor (Anysphere) | 77 |
| 3 |  Groq | 25 |
| 4 | Substack | 53 |
| 5 | Baseten | 47 |
| 6 |  Crunchbase | 33 |
| 7 | ElevenLabs | 55 |
| 8 | Grok Bot | 70 |
| 9 | Harmonic | 21 |
| 10 | Hermes Agent | 37 |
The strategy of naming, defining and leading a new market.
Category creation stayed nearly flat from April through June, softened in July, briefly recovered in August, then dropped sharply in September. The L30 is down another 51%, despite a slightly higher early October bar. The evidence forms a critique cycle: focus on the job, compete inside known categories, and question whether AI weakened category gatekeepers.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | HubSpot | 88 |
| 3 | Clay | 90 |
| 4 | Granola | 51 |
| 5 | Nooks | 48 |
| 6 | Adobe Marketo | 25 |
| 7 | Ahrefs | 50 |
| 8 | Attio | 52 |
| 9 | Braze | 26 |
| 10 | Cursor (Anysphere) | 77 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
The August spike came directly from new transparency rules and implementation announcements tied to the EU AI Act and California’s AI Transparency Act. Anthropic’s watermarking FAQ and Synthesia’s automatic C2PA credentials concentrated attention in that month; September then dropped sharply, and the L30 measure is down 84.7%, despite a higher early October bar.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 70 |
| 4 | HeyGen | 32 |
| 5 | Granola | 51 |
| 6 | Runway | 36 |
| 7 | Vercel | 60 |
| 8 | Docket | 31 |
| 9 |  Ghost | 18 |
| 10 | Higgsfield | 38 |
AI-generated creators, avatars and user-style content used in marketing.
Conversation spiked in April, cooled through summer, then recovered in September; the 38% L30 rise shows that momentum is continuing without treating partial October as complete. Recent discussion centers on filming barriers, marketers testing their own avatars, and narration tools that remove repeated shoots when demo copy changes.
Posts to understand this
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
Conversation share climbed from March to a May peak as HubSpot put per-result agent pricing into market. It then fell through August despite Salesforce investing in flexible billing infrastructure, before improving in September; the latest 30 days are up 40%, with October discussion challenging seat pricing as a measure of delivered value.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Clay | 90 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | HubSpot | 88 |
| 5 | Intercom | 44 |
| 6 | Lovable | 59 |
| 7 |  Metronome | 27 |
| 8 | Vercel | 60 |
| 9 | 1mind | 37 |
| 10 | 6sense | 41 |
AI-native firms that sell finished work instead of software, delivered by agents and a small human team.
Services-as-Software fell sharply after its spring concentration, from 0.345% in June to 0.155% in August, before a small September lift. The L30 is up 18.8%, but the L90 remains down 43.1%. Spring had concrete fuel from Emergence’s category blueprint and Daydream’s $15M round; September’s Sequoia thesis brought the model back into view.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Crunchbase | 33 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
Share rose unevenly from March, reaching a June-August plateau, then dropped sharply in September. The L30 move is down 71.4%, even as September launches showed both sides of the connector market: Zapier supplied broad app access, while OpusClip and Tally added focused video and form workflows.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Cursor (Anysphere) | 77 |
| 3 | HeyGen | 32 |
| 4 |  Lambda | 25 |
| 5 | Lovable | 59 |
| 6 | Salesforce | 93 |
| 7 | Zapier | 53 |
Pushback against AI from customers, workers and the public, and brands repositioning as pro-human.
The curve is choppy, with a May spike around direct attacks on the backlash and an August rebound as critics highlighted an AI sales company’s return to human labor. September remained active as anti-AI graffiti surfaced in San Francisco, but the conversation has fallen 37.6% over the last 30 days.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Grok Bot | 70 |
| 3 |  Bland | 19 |
| 4 | Browserbase | 33 |
| 5 | ElevenLabs | 55 |
| 6 | Granola | 51 |
| 7 |  Gumloop | 25 |
| 8 | HubSpot | 88 |
| 9 | Lovable | 59 |
| 10 | Replit | 57 |
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent Loops surged in June, stayed near that high in July, then declined through September; L30 is down 37.4%. Joe Rhew’s June prediction helped define the concept, while Palantir’s Agent Engine and SDK gave July a concrete launch; Atlassian’s September focus on governed loops shows the idea persisting in a narrower form.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Attio | 52 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 |  Deepline | 31 |
| 5 | HubSpot | 88 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | LangChain | 47 |
| 9 | OpenClaw | 51 |
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
Autonomous Business discussion declined from March to an August low, rebounded in September, and is down 14.8% over the last 30 days. The September lift came with concrete efficiency claims from RB2B and Swan AI, but it did not restore earlier attention. The recurring hook is revenue per employee, anchored by Polsia’s one-employee operation.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 70 |
| 3 | Lovable | 59 |
| 4 | Vercel | 60 |
| 5 | Codex | 84 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | ElevenLabs | 55 |
| 8 | Gamma | 44 |
| 9 |  Lusha | 28 |
| 10 |  Netlify | 27 |
Interfaces that let agents understand and operate software built for human users.
Agent interfaces remain small and volatile: a May spike collapsed in June, rebounded in July, then eased through September. The last 30 days are up 13%, supported by a pattern rather than one event as Hightouch, Salesforce, and major GTM platforms build connectors, experience layers, CLIs, and MCP access for agents.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Browserbase | 33 |
| 3 | Claude Code | 99 |
| 4 | Clay | 90 |
| 5 | Exa.ai | 46 |
| 6 | HubSpot | 88 |
| 7 | Peec AI | 28 |
| 8 | Twilio | 43 |
| 9 | Vercel | 60 |
The online channel mix used to reach, convert and retain customers.
Conversation climbed into June, then fell through September. Around that turn, marketers argued that brand mattered more than adopting each new tool, then said zero-click behavior was weakening legacy digital work; by September, the focus had shifted to AI-agent recommendations, while the L30 measure shows attention remains down 27.7%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | AI Ark | 46 |
| 2 | Apollo.io | 52 |
| 3 |  Chili Piper | 35 |
| 4 | Clay | 90 |
| 5 |  Default | 28 |
| 6 |  Freckle.io | 34 |
| 7 | HeyReach | 52 |
| 8 | HubSpot | 88 |
| 9 | Instantly | 63 |
| 10 |  Mutiny | 32 |
The argument over requiring a form before someone can access useful content.
The gated-content debate has contracted sharply since March, despite a May rebound around a more nuanced rule: ungate the argument, gate the utility. Share then declined through September as later posts pushed the harder position that forms create false leads and buyer friction. The L30 move is slightly positive, suggesting stabilization rather than a clear comeback.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | AI Ark | 46 |
| 3 | ActiveCampaign | 32 |
| 4 | Ahrefs | 50 |
| 5 | Apify | 52 |
| 6 | Attio | 52 |
| 7 | BuiltWith | 33 |
| 8 | Chili Piper | 35 |
| 9 | Clay | 90 |
| 10 |  Crossbeam | 26 |
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing climbed through July, then lost ground in August and September; the L30 move remains down 51.6% despite a higher partial October bar. The decline reflects a clear language shift, not one isolated event: HubSpot, Databricks, and Sierra all redirected the conversation from token volume toward value, efficiency, and outcomes.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 93 |
| 2 | Claude Code | 99 |
| 3 | Clay | 90 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | HubSpot | 88 |
| 7 | Midjourney | 36 |
| 8 | Profound | 53 |
| 9 |  Retool | 27 |
| 10 |  Writer | 28 |
Brands use human authorship and craft as a reason to trust or value their work.
The curve has swung month to month, with no single event behind it. Dave Gerhardt framed human-made work as a premium in May, while GTM Skills and Alex Fine turned that claim into concrete offers around human-crafted expertise and writing. August strengthened and September eased; the L30 is down 18.3%, though the L90 remains up 46.9%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Attention | 30 |
| 2 | Clarify | 30 |
| 3 | Clay | 90 |
| 4 | Clearskies | 21 |
| 5 | Nooks | 48 |
| 6 | Rox | 31 |
| 7 | Sumble | 32 |
| 8 | Claude Code | 99 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Grok Bot | 70 |
Software designed for agents to operate as the primary user.
Conversation emerged in June, rose through August, dipped in September, then accelerated 94% over the last 30 days. No single event drove it: Ploy opened sites to agents, Lorikeet launched agent-traffic detection, and Amazon and Cloudflare restrictions made the new tension concrete as agent traffic grew.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Vercel | 60 |
| 2 | Ahrefs | 50 |
| 3 | Breeze | 24 |
| 4 | Clay | 90 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Gamma | 44 |
| 7 | Grok Bot | 70 |
| 8 | HubSpot | 88 |
| 9 | Intercom | 44 |
| 10 | Lovable | 59 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
Trust-Based Marketing remains small and volatile: it recovered through July, dropped sharply in August, then partly returned in September. G2’s public Trust & Safety Index gave that rebound a concrete proof point, while the broader posts favor coherence and repeated credibility over content volume. The L30 move is positive, though the 90-day direction remains down.
Posts to understand this
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
AI detection broke out in July and held near that level in August, then dropped sharply in September; the L30 is down 75.7%. The spike came from arguments over AI-heavy LinkedIn content and detector-based studies of search performance. The retreat suggests an event-led debate rather than sustained category momentum, even with L90 share still elevated.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 70 |
| 4 | Replit | 57 |
| 5 | Substack | 53 |
Using product activity to identify, time and support sales opportunities.
Product-Led Sales remains a tiny, intermittent conversation, with zero-share months punctuated by small bursts in March, June, August, and September. Its 180% L30 rise comes from that very low base, not a broad breakout; the first eight October days add only early context. Posts frame the topic through HubSpot infrastructure and consolidation after Pocus joined Apollo.
Posts to understand this · as of Oct 8
How model costs, services and agent work put pressure on software gross margins.
This is a sparse conversation, with a brief April high of 0.031% and zero-share months in May and July. The current L30 move is down 60%, and the evidence remains split between lower AI gross margins and a services model where smaller engagements can unlock a larger market.
Posts to understand this · as of Oct 9
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Share fell steadily from 11.5% in March to 4.3% in September, with the L30 down another 16.3%. The selected posts span an April model integration, July terminal frustration, and an October outbound workflow, showing that practical use continues even as the conversation contracts.
Posts to understand this · as of Oct 10
Cursor is an AI code editor with agents that write, edit and review code.
Cursor declined from March through July, then spiked in August when its SpaceX acquisition closed and the product joined the SpaceXAI portfolio. That deal-driven attention faded sharply in September, and the 44.9% L30 decline shows the slide continuing. A reported Nvidia usage signal did not sustain the acquisition bump; October remains incomplete.
Posts to understand this · as of Oct 10
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay climbed to a May high, then lost share through the summer and remained lower in September; the last 30 days are down 11.2%. May’s $770,000 pipeline case supplied a sharp proof point, but later conversation split between ecosystem training and Ocean.io’s claims of replacing Clay in enterprise deals, a pattern consistent with a maturing, contested category.
Posts to understand this · as of Oct 8
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n’s spring lift maps to two concrete distribution moves: Gamma’s native integration in April and the multi-year SAP partnership announced in May, which put n8n inside Joule Studio. Share topped out in June, then declined through September; the 37.2% L30 drop says the event-led attention has continued to cool.
Posts to understand this
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable’s March peak coincided with its free global SheBuilds day, while a parent’s account showed the event turning a first-time builder into an app creator. Share then fell through July and stabilized around 1% in August and September, when Slack included Lovable among its agent partners, but the latest L30 measure is down 23.2%.
Posts to understand this
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit’s share peaked in May, fell sharply in June, then partly recovered in August as OpenAI announced GPT-5.6 Luna in Free Mode. It slipped again in September while a production-database incident circulated in AI-safety discussion, even as Apollo launched inside Replit’s Growth Kit; the L30 measure now points up 3.9%.
Posts to understand this · as of Oct 4
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
OpenClaw declined steadily from March through September, and the L30 move remains negative despite a higher partial October bar. No single event explains the fade: early saga-level attention gave way to comparisons with easier alternatives such as Grok bot and broader discussion of agent harnesses as a category.
Posts to understand this · as of Oct 4
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
Codex rose into the 3% range by May, then held a remarkably steady plateau through September. The L30 is up 4.5%, supported by a widening product surface: Exa added access to 100 billion-plus sources, while Clay brought prospecting and enrichment workflows into Codex terminals.
Posts to understand this · as of Oct 5
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Hermes Agent appeared sharply in April and remained elevated in May as image-generation access expanded across agent workflows. Attention then declined month by month through September; free Perplexity search added a useful capability, but it has not changed the current direction, with the L30 down 11.6%.
Posts to understand this · as of Oct 10
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce conversation rose in April, cooled through July, then rebuilt in August and jumped in September. The visible posts span acquisition news, Informatica’s Dreamforce debut, and product frustration; October is partial, while the L30 move is up 6.7%, so current direction is higher.
Posts to understand this · as of Oct 10
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
HubSpot peaked in May, then lost share through August before a modest September recovery; L90 remains down 31.1%, while L30 is up 8.8%. Agent pricing and the Warmly acquisition supplied earlier bursts, and Trigify’s September move gave the recent improvement a concrete catalyst. The first four October days are only early context.
Posts to understand this · as of Oct 4
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Share peaked in April, fell through August, then edged up in September; the selected evidence does not establish what drove the April high. September conversation paired Gong’s call benchmark with direct competitor positioning, while fresh competitor comparisons align with the 7.7% L30 rise.
Posts to understand this · as of Oct 10
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
Vercel’s share moved unevenly, with an August spike alongside its inclusion in Slack Code’s agent launch and hands-on interest in Vercel Workflows. September gave that gain back, and the 20.2% L30 decline points to continued softness; October’s partial bar is only early context.
Posts to understand this · as of Oct 10
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Claude Cowork’s share fell steadily from March through September, leaving the 90-day view down 57%. The last 30 days are up 11%, supported by Anthropic’s small-business relaunch with 43 workflows and 27 integrations, including Docusign IAM; the partial October bar is only early context, not a completed reversal.
Posts to understand this · as of Oct 10
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly rose from March to a June high, then settled into a lower but stable band from July through September; the L30 is down 15.1%. That plateau still reflects operational use, not passing mentions: teams run hundreds of mailboxes, centralize replies in Slack and Attio, and recruit specialists for warming, testing, and deliverability.
Posts to understand this
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter rose from a small March base, then spiked in August when Stripe agreed to acquire it. September cooled sharply, and the L30 is down 44%, though share remains well above spring levels over the last 90 days. Model availability and a rare OpenAI-over-Anthropic spending shift kept the platform in the conversation.
Posts to understand this
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
Substack’s share bounced through spring and summer, then declined from July through September; the latest 30 days fell another 27.7%. The conversation is mixed: creators are testing more customizable alternatives, while Substack is still adding prominent writers and Notes is gaining publishing support.
Posts to understand this · as of Oct 10
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Semrush climbed into a June peak after its Lovable partnership and a burst of discussion about AI visibility, then fell sharply through August. September stabilized, and the L30 is up 10.9%, helped by practical relevance around Google’s new redirect system and Semrush’s claim that its tracking remained unaffected.
Posts to understand this · as of Oct 10
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva’s conversation share peaked in April, then fell through September, with a brief pause in August. The selected posts capture May connector exposure, August scrutiny of a lower growth forecast and AI serving costs, and September’s upgrade announcement, but none explains the longer decline. The L30 reading is up 22.9%, showing a recent rebound.
Posts to understand this · as of Oct 10
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Ahrefs jumped in May and stayed high in June as its AI visibility research fed a broader argument for treating LLM discovery as a distinct channel. Attention then dropped and settled into a narrower August-to-September range. The L30 is essentially flat at down 0.4%, even as Google redirects created fresh product scrutiny.
Posts to understand this · as of Oct 10
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier rebounded in May, then settled lower through summer before another September drop; the L30 is down 46.5%. The posts show a consistent pressure pattern: Claude hooks remove Zapier from workflows, agents propose handling integrations themselves, and adjacent GTM products keep absorbing orchestration.
Posts to understand this · as of Oct 10
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
ZoomInfo fell from March’s high, briefly recovered in June, then lost share through September; the L30 is down another 32%. No single event explains the slide: Ava 2.0 positioned itself as a ZoomInfo replacement, while Exa Connect and ZoomInfo’s Slack MCP increasingly cast its data as infrastructure inside other products.
Posts to understand this · as of Oct 10
Profound measures and improves how brands appear in AI answers.
Profound has been volatile but directionally stronger, from 0.2% in March to 0.7% in September, with the L30 up 51%. The latest lift aligns with its $180M Series D and unicorn valuation, while sustained criticism of content quality and sampling reliability keeps the conversation from becoming purely celebratory.
Posts to understand this · as of Oct 7
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
ElevenLabs built gradually through May, fell across the summer, and recovered in September. The 49.7% L30 rise is supported by evidence of a maturing enterprise machine: more than $600 million in ARR, an MCP for managing agents inside Claude, and 59 open enterprise roles representing 42% of its GTM hiring.
Posts to understand this · as of Oct 10
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio rose steadily into May, supported by Intercom’s Fin sales workflow and the GTM Atlas launch, then declined each month through September. A September Snitcher integration showed continued ecosystem activity, but it did not create a new wave; the L30 is nearly flat at down 2.8%.
Posts to understand this · as of Oct 10
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo.io rose sharply into May, then drifted lower through September; L30 is down 29.3% and L90 is down 11.7%. The earlier climb matched a concrete workflow shift, with Claude using Apollo as the data layer, while September posts centered on Apollo Next and community access rather than a major product announcement. The elevated early October bar does not establish a reversal.
Posts to understand this · as of Oct 4
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify’s share surged from 0.142% in March to 0.913% in May, but the selected conversation only becomes visible in June, when creators framed it as the data layer for Claude-based social analysis and content systems. Share held near 0.9% through July, then fell through September; a September GTM workflow mention shows continued utility, while the L30 move is down 28.9%.
Posts to understand this · as of Oct 7
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Granola peaked in May, declined through July, then recovered some attention in August and held near that level in September. Apple Watch access and a Grok sales integration broadened its footprint, while Muesli’s free, local alternative sharpened the competitive contrast; the L30 is now up 10.6%.
Posts to understand this · as of Oct 10
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
HeyReach climbed steadily from March through June, held flat in August, then moved lower in September; the L30 is down 41.2%. No single event owns the curve. Ban chatter, criticism of automated outreach as spam, and later proof of $17 million ARR show a product with real scale facing persistent channel-quality concerns.
Posts to understand this · as of Oct 10
RB2B identifies the people and companies visiting a website so sales can follow up.
RB2B’s share climbed from March to a June high, then fell sharply through August before a modest September rebound. The conversation spans a late-May $9.1M ARR milestone and two September outbound playbooks that use website visits as a sales signal, while the latest 30 days are down 5.3%.
Posts to understand this
Intercom is a customer messaging platform built around Fin, its AI support agent.
Intercom fell from March through May, bounced in June, then collapsed to a much lower level in July before a modest September lift. No one post explains that volatility: discussion spans Fin observability, a reported Salesforce exit, and RB2B’s use of Fin for support. The L30 is up 26.0%, but the 90-day picture remains down 58.8%.
Posts to understand this · as of Oct 9
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
LangChain dropped sharply in April, recovered by June, then held a meaningful plateau through September instead of fading after the rebound. L30 is up 47.4% and L90 up 21%, with the conversation broadening across production agent evaluation, internal GTM agents, and teams comparing LangChain with Dust, Gumloop, and Vercel Workflows.
Posts to understand this · as of Oct 10
Baseten deploys and runs custom AI models in production.
Baseten built from July into August as Kimi K3 day-zero API support and the free Inference Engineering release gave the rise two concrete anchors. September stayed near that higher band as Harvey disclosed an M&A diligence partnership, but L30 has since fallen 33.2%; October’s first eight days are early context, not a completed drop.
Posts to understand this · as of Oct 8
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Conversation share climbed from March through July, dropped sharply in August, then recovered in September. The selected posts show Nooks appearing in an AI-native sales stack by May, a September critique of parallel dialing, and an October message about reliable revenue agents; October remains partial, while the last 30 days are up 13.7%.
Posts to understand this · as of Oct 10
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Common Room climbed steadily from March to a July high, when Zoom announced its acquisition, then attention dropped hard in August and September. The L30 is down 23.5%, so October’s partial bar is early context, not a reversal. Later discussion placed the deal inside a wider intent-data consolidation wave alongside Pocus and Warmly.
Posts to understand this · as of Oct 8
Exa.ai is a web search API designed for models and AI agents.
Conversation climbed through May, dipped in June, rebounded in July, then fell back in August. Applied GTM research, a technical explanation of agent search, and a September Sprites connector show the narrative broadening from use case to architecture to distribution, while the latest 30 days are up 25.3%.
Posts to understand this · as of Oct 6
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly’s share climbed from 0.263% in March to 0.540% in July, with a June product launch followed by HubSpot acquisition commentary in early July. It fell to 0.120% in September, when the acquisition resurfaced in a broader GTM consolidation discussion; the L30 move is nearly flat at 1.3%.
Posts to understand this · as of Oct 9
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode’s share climbed gradually from March through June, then accelerated in July and August as Supabase included it in agent evals and Grok 4.6 became available through it. Share pulled back in September, and the L30 measure is down 29.9%, even as Databricks added OpenCode to its centrally managed agent workflow.
Posts to understand this · as of Oct 6
Gamma turns prompts into presentations, documents, websites and images.
Gamma’s March high coincided with a Claude connector workflow, but the larger pattern is uneven decline rather than one decisive event. Atlassian integrations produced major moments in April and September without sustaining a climb; after a July low and August bounce, the last 30 days are nearly flat at +1.8%, while the 90-day trend is down 30.7%.
Posts to understand this · as of Oct 7
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps has moved in bursts rather than a sustained climb. Attention jumped in May around AirOps Next and the Quill release, then fell through July and settled into a narrow August-September plateau. That steadiness matters after the drop: category research still supports conversation, and the L30 is up 7.8% despite a 55.1% L90 decline.
Posts to understand this · as of Oct 10
1mind provides AI sales agents for websites, demos, live calls and customer success.
Conversation opened high in March alongside 1mind’s Clari and Salesloft announcement, dipped in April, then recovered through June. A July LeanData integration and August webinar pipeline post did not reverse the slide: share fell in July, held roughly flat in August, dropped again in September, and is down 42.8% over the last 30 days.
Posts to understand this · as of Oct 5
Firecrawl turns websites into clean, structured data for models and agents.
Firecrawl’s share climbed from March through May, fell in June, hit a higher peak in July, then settled lower through August and September. May’s Claude Code lead-gen walkthrough and July’s onboarding praise tracked the two bursts, while a late-September data-provider listing aligns with the current L30 rebound.
Posts to understand this
Higgsfield generates video and images for ads and social content.
Higgsfield climbed from April through June, held flat in July, then lost ground in August before a modest September recovery. The L30 gain of 27.9% aligns with fresh product heat around AI Influencer, while Together AI’s infrastructure support explains how Higgsfield can sustain high-volume video workloads.
Posts to understand this · as of Oct 6
Grok Bot is an always-on agent that learns routines and completes work across existing software.
Grok Bot appeared from zero in August and gained further share in September after its early-beta launch. The conversation had multiple reinforcing proofs: real work across existing tools, autonomous subscription cancellation, and a Stripe-linked card for online purchases. L30 is up just 0.9%, so current momentum is closer to a plateau than another breakout.
Posts to understand this · as of Oct 10
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce appeared in August with the Salesforce and Anthropic launch, then gained further share in September as Dreamforce extended the discussion into shared context and organizational workflows. The 36.8% L30 decline shows launch attention is now cooling, while Bloomreach’s response kept the debate focused on who should own the AI harness.
Posts to understand this
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
Conversation jumped from 0.31% share in August to 5.07% in September, alongside an early-September benchmark, broad token access, and a later customer account of day-to-day use. The last 30 days are down 5.1%, so attention has eased from that September peak as discussion widened from model performance to availability and production use.
Posts to understand this · as of Oct 10
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Claude Fable appeared from almost zero in June and reached its high in July after the Fable 5 launch. Attention fell in August, rebounded with Fable 5.1’s September arrival in Cursor, then dropped 55.9% over the last 30 days; October’s first eight days only provide early context for that cooling.
Posts to understand this · as of Oct 8
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
After an April spike, GPT-5 fell sharply in May and stayed low through September. No single launch in the posts explains the recent movement: benchmark comparisons, inclusion in Replit’s model picker, and September cost criticism form a thin but recurring drumbeat. The L30 measure is up 107.7%, though L90 remains down 28.6%.
Posts to understand this · as of Oct 7
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Claude Opus moves in launch-driven bursts: an April jump held through May after Opus 4.7 reached Perplexity and Harvey, followed by sharp resets in June and August. September rose again, and the 259.4% L30 gain points to fresh momentum from Opus 5.5 entering Cursor with stronger benchmark results and lower task costs.
Posts to understand this · as of Oct 10
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Grok 4 surged in July as Grok 4.5 topped AutomationBench-AA, then held most of that attention through August before easing in September. Perplexity’s Grok 4.6 rollout and Grok 4.7’s coding result kept the product visible, but neither reversed the current L30 decline of 17.7%.
Posts to understand this · as of Oct 10
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Conversation spiked in June, fell through August, then turned up in September. The rebound followed late-September Sonnet 5.5 rollouts across Snowflake, Netlify, and Hyperbrowser, while the 348.9% L30 increase shows attention is still rising in October rather than treating the partial month as complete.
Posts to understand this · as of Oct 10
Muse Spark is Meta's AI model for running coding and other agents.
Muse Spark rose from a small July base through September as benchmark credibility gave way to product distribution. Muse Spark 1.1 placed near the top of Mercor’s agent leaderboard, then version 1.3 reached Genspark and powered Meta’s Muse personal agent. The last 30 days are down 10.7%, so that launch sequence has not sustained its earlier pace.
Posts to understand this · as of Oct 8
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Conversation surged with the May release, then rebounded in July as independent tests highlighted strong browser-agent price and performance. September’s security partnership showed continued adoption, but momentum has since cooled, with share down 66.4% over the last 30 days.
Posts to understand this · as of Oct 10
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
Kimi’s sharp July spike came with K3 benchmark results that framed it as a lower-cost Claude alternative, including software engineering performance at roughly 35% of the price. Conversation cooled through August and September and is down 10.8% over the last 30 days, despite Cline offering Kimi K3 free for a limited time.
Posts to understand this · as of Oct 8
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen climbed in July and reached an August high as n8n added a Qwen Cloud node for multimodal and agent workflows. September fell sharply despite a local deployment example and the Qwen-Image-2.1 release; the 45.9% L30 decline shows those updates did not sustain the integration-led lift.
Posts to understand this
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM broke from near-zero share in June when GLM 5.2 drew attention as a local, open coding model, then held a much higher band through summer. September brought Notion distribution and strong Bolt adoption for GLM 5.3 Flash, but the L30 measure is down 32.3%, so recent reach has not sustained the earlier pace.
Posts to understand this · as of Oct 9
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos jumped from 0.11% in March to 1.65% in April around the restricted cybersecurity preview, fell in May, spiked again in June, then held below 0.3% from July through September; the L30 is down 49.1%. September conversation paired the Mythos 5.1 introduction with its pricing match to GPT-6 Astra.
Posts to understand this · as of Oct 10
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney’s share jumped from 0.358% in May to 0.637% in June, when Gamma showed the product inside its brand system and discussion highlighted its community-funded model. Share then fell through September, with a further 26.0% L30 decline; the latest evidence casts Midjourney as one component inside a Claude-built film workflow, not the main launch.
Posts to understand this · as of Oct 10
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Conversation jumped in April around Windsurf’s Devin cloud delegation, then fell through June before rebounding in July and August as Daytona added controlled sandboxes and Amplitude placed Devin among parallel agent fleets. That rebound has cooled, with share down 39.8% over the last 30 days.
Posts to understand this · as of Oct 4
Runway is an AI platform for generating and editing video and images.
Runway’s share softened through July and August, then jumped sharply in September; the August competitor pricing comparison is the closest visible lead-in, but it does not establish the spike’s cause. October is partial, and the L30 measure is down 7%, even as fresh future-of-work coverage keeps Runway in view.
Posts to understand this · as of Oct 9
Jev is TypeSafe AI's decision model, which returns typed answers such as choices, probabilities and scores instead of text.
September’s jump was driven first by Vercel reporting record-fast AI Gateway adoption, then by concrete use cases later in the month. MotherDuck documented faster, cheaper classification, while HeyGen used Jev to decide which leads should receive videos, supporting its new presence over the last 30 days.
Posts to understand this · as of Oct 4
Muse is Meta's personal AI agent, which connects to a person's email, calendar and payments to shop, book and schedule for them.
Muse was absent through July, appeared in August, then jumped sharply in September; the 401.2% L30 gain says attention is still expanding. The rise came from concrete demonstrations and debate: restaurant reservation prompts, Bland-powered phone calls, and questions about accountability when consumer and service agents interact.
Posts to understand this
Instinct is a personal AI agent with its own email address that creates accounts, contacts businesses and handles support requests for its user.
Instinct emerged in August, broke out in September, and is up 385.1% over the last 30 days. The curve reflects a cluster, not one announcement: rapid valuation chatter and repeated word of mouth established the brand, while October’s early Personal Agent Protocol announcement connected Instinct to Meta, Sierra, Shopify, Stripe, and Walmart.
Posts to understand this · as of Oct 8
Join 19,392+ GTM leaders and practitioners. Free, unsub anytime.
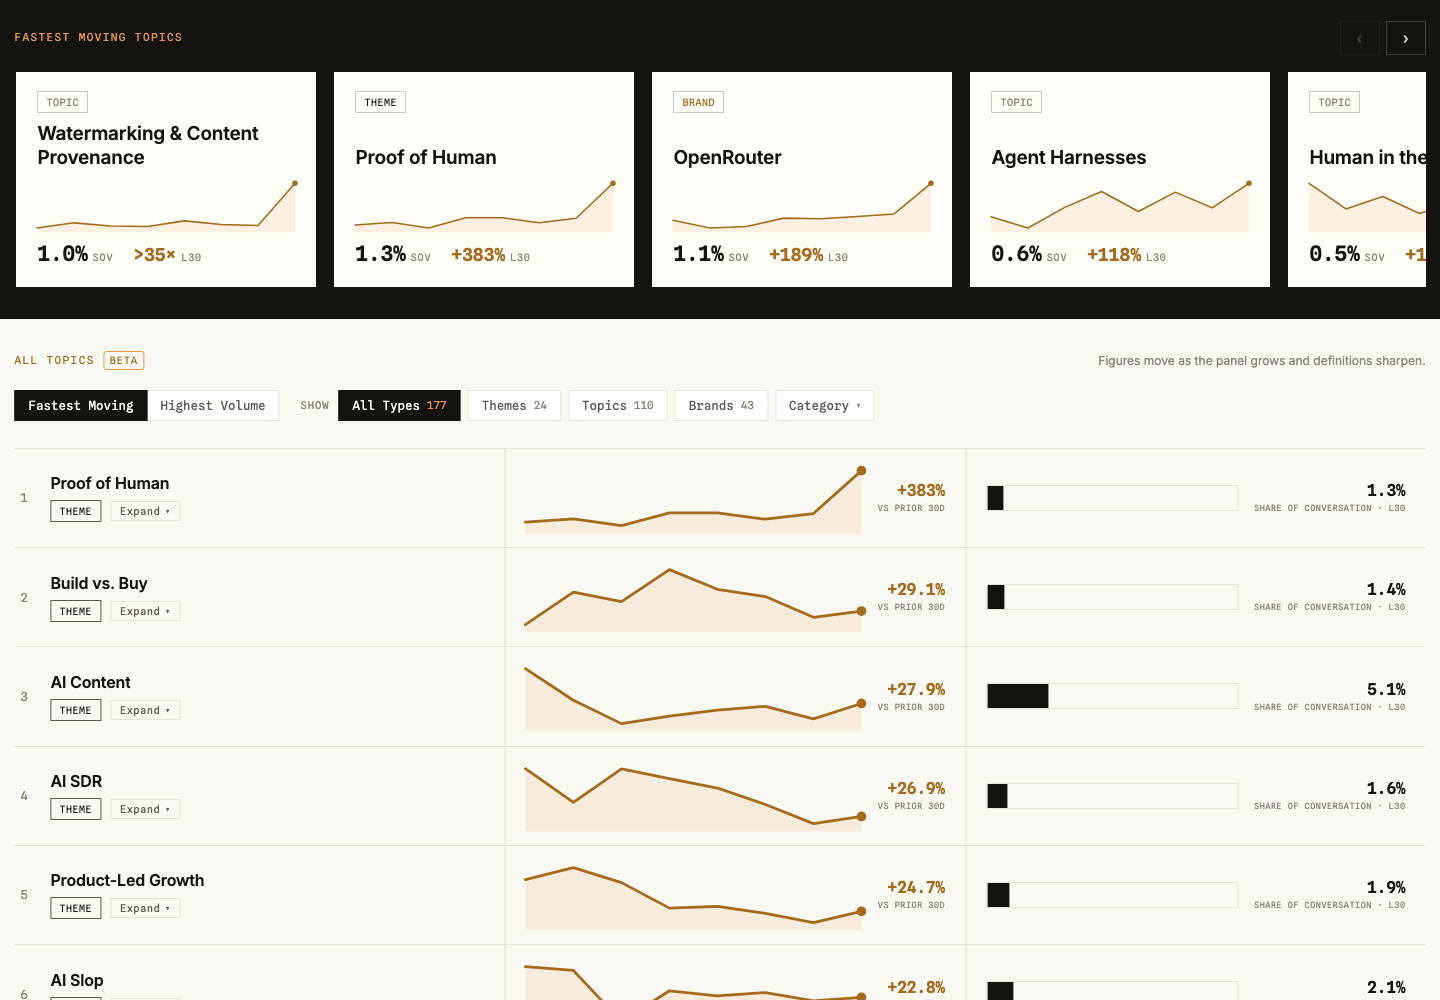
Loading people…
join 19,392+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-10-11.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,392+ gtm leaders, unsub anytime.