What’s moving now
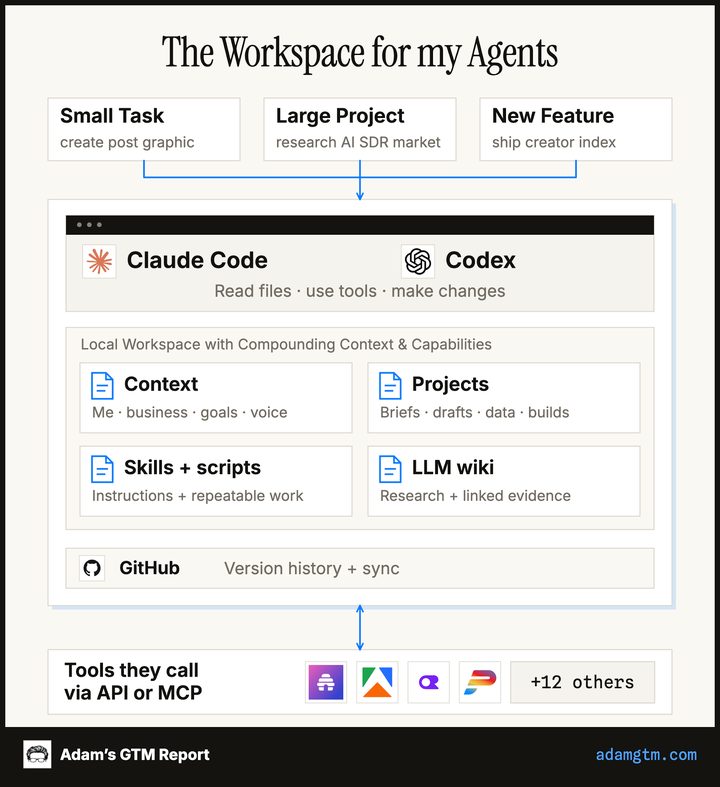 How I'm buildingOct 8 · the agents, workflows, and tools behind my one-person busi
 13.8× the usual response · 248 engagements
 D12.9× the usual response · 1,391 engagements
 10.0× the usual response · 1,236 engagements10.0× the usual response · 1,236 engagements
 6.2× the usual response · 275 engagements
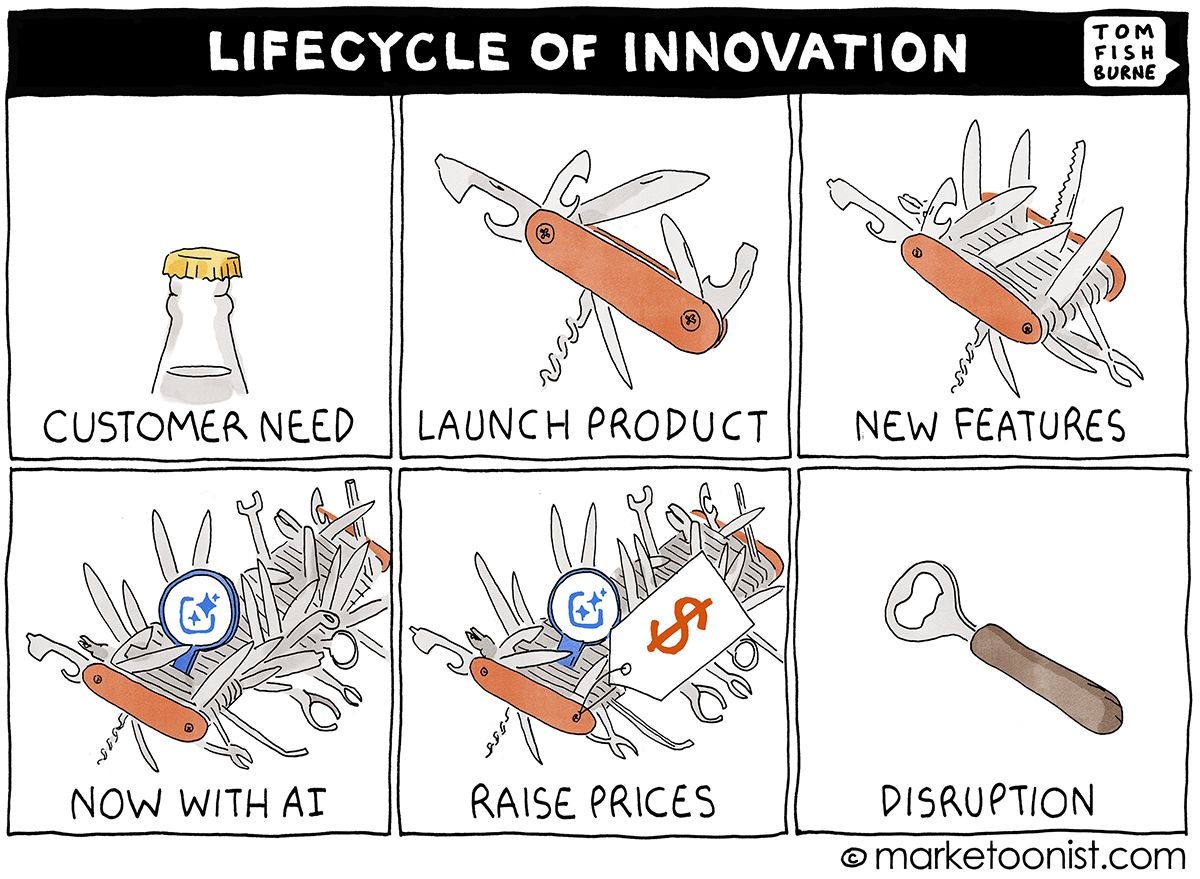
 Tom FishburneUses Zoom, Mailchimp and Beehiiv to argue that feature expansion and upmarket moves can exceed customer needs, creating opportunities for simpler competitors.
 2,251 interactions · 1d agoTrending Creator
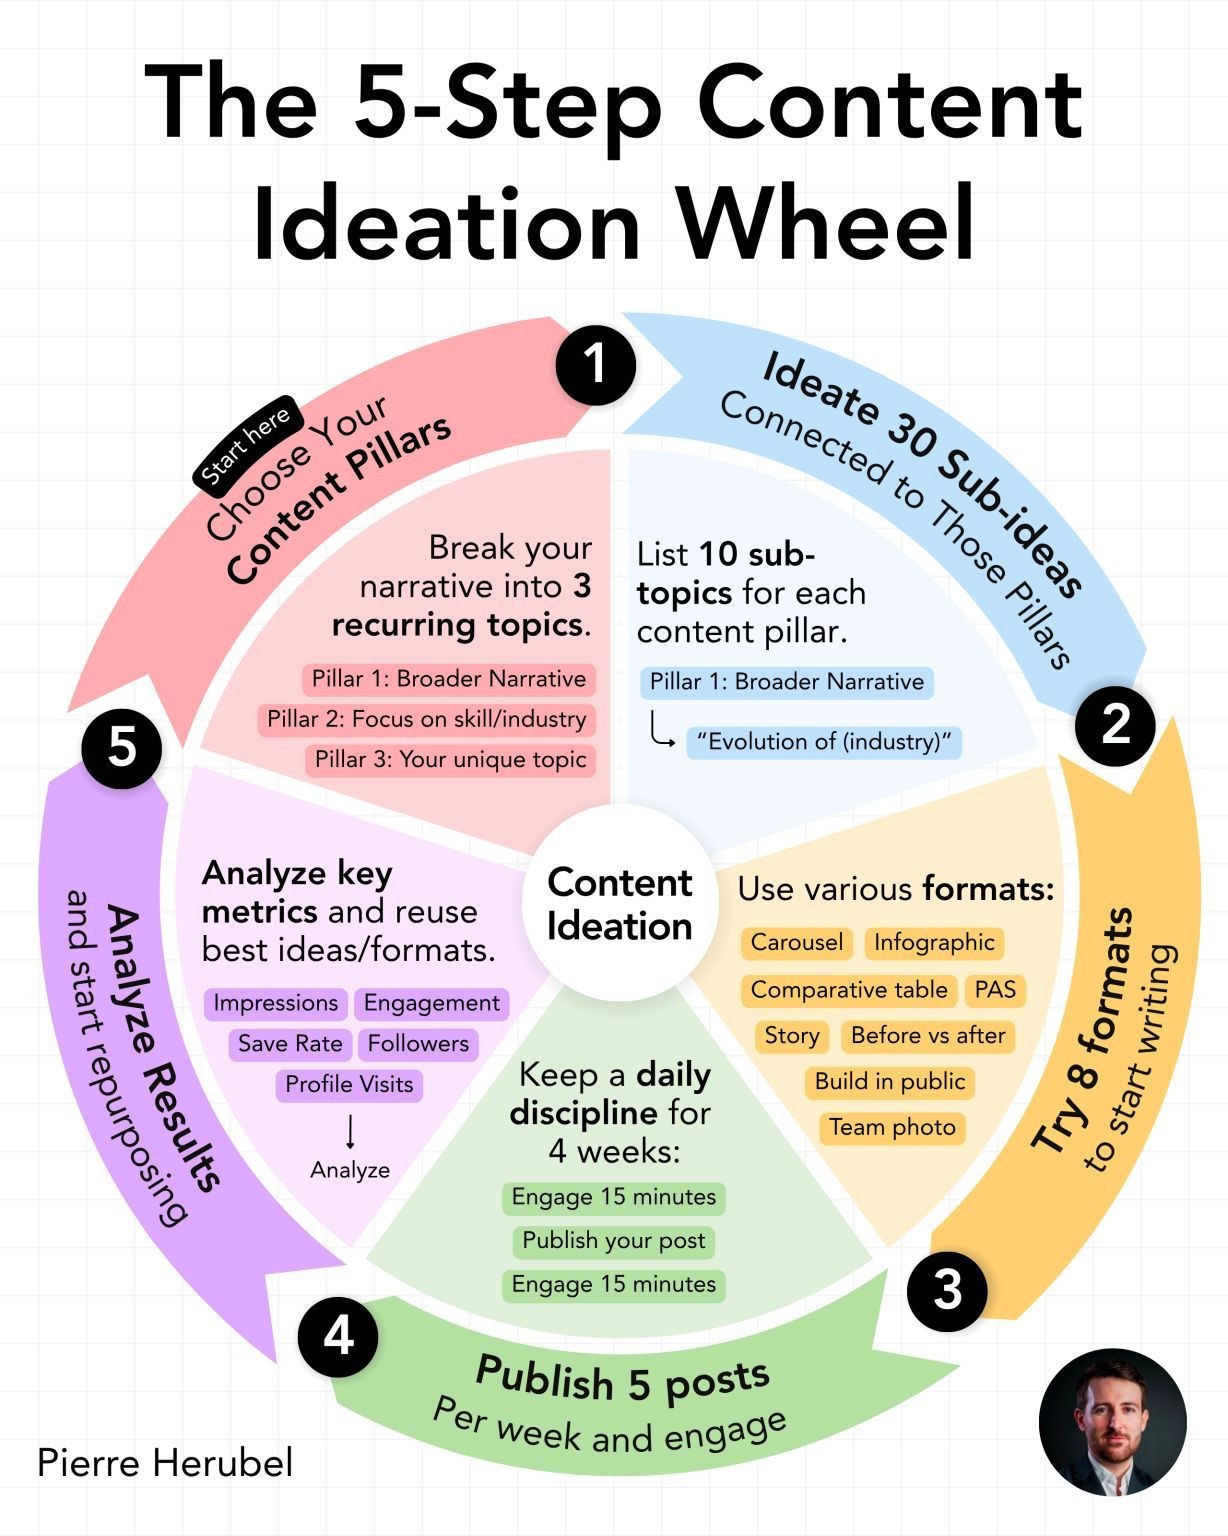
 Pierre HerubelRecommends a five-step content process covering three pillars, 30 subtopics, eight formats, consistent publishing, and performance analysis to guide reuse.
 498 interactions · 1d agoTrending Creator
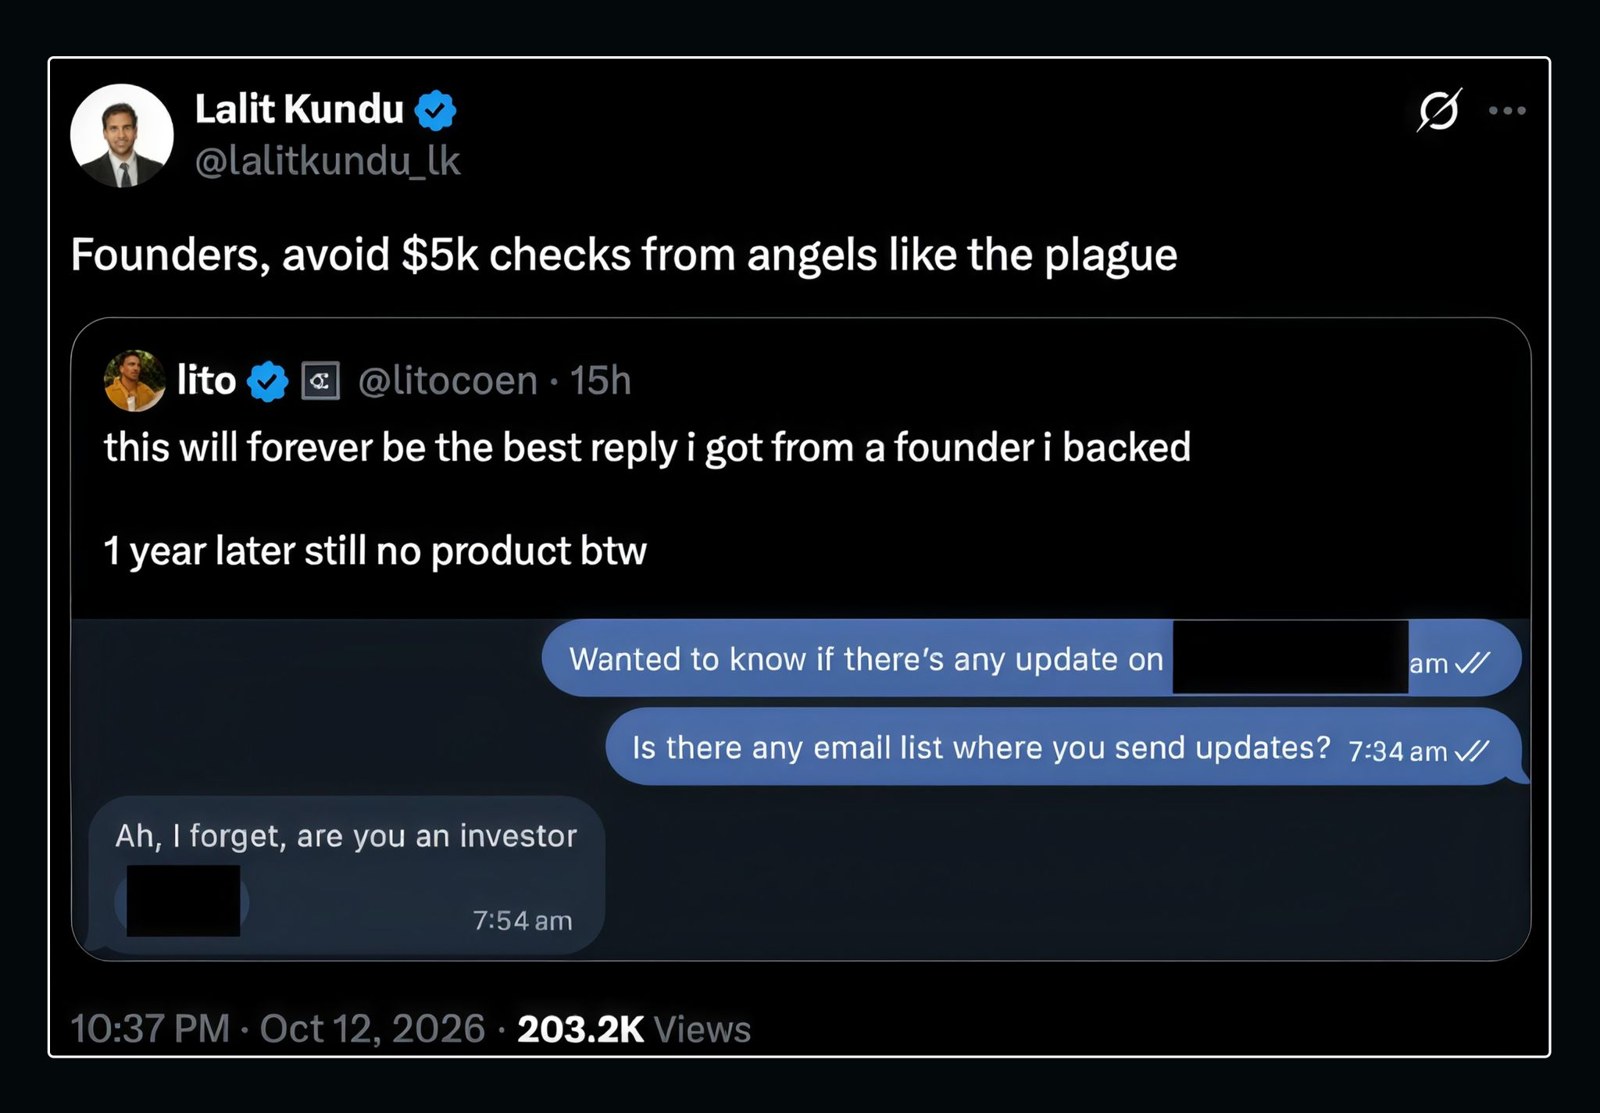
 Peter WalkerArgues founders should welcome small angel investments for their potential contributions and fundraising momentum, while investors should accept standard terms to minimize overhead.
 441 interactions · 12h agoTrending Creator
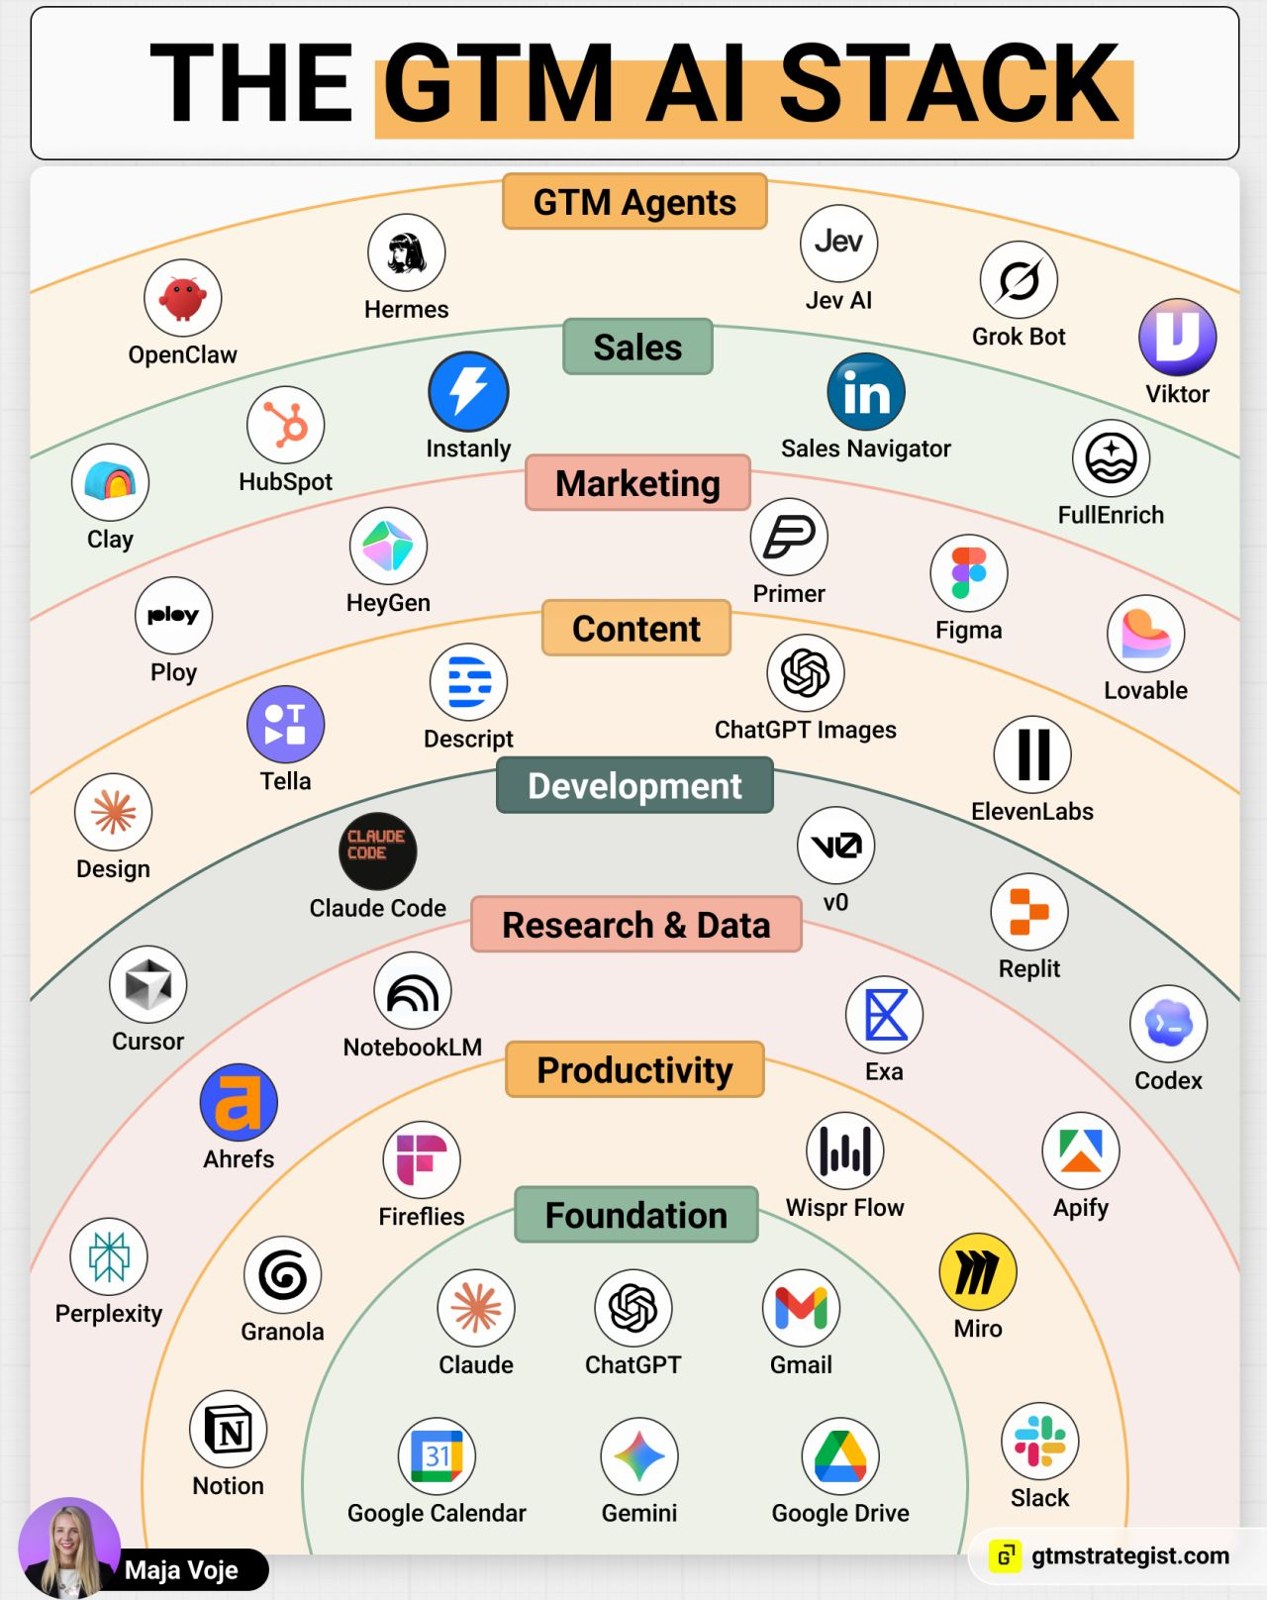
 Maja VojeOrganizes 42 tools into eight functional layers, prioritizing integration and returns while arguing that all-in-one platforms create vendor lock-in.
 402 interactions · 1d agoTrending Creator
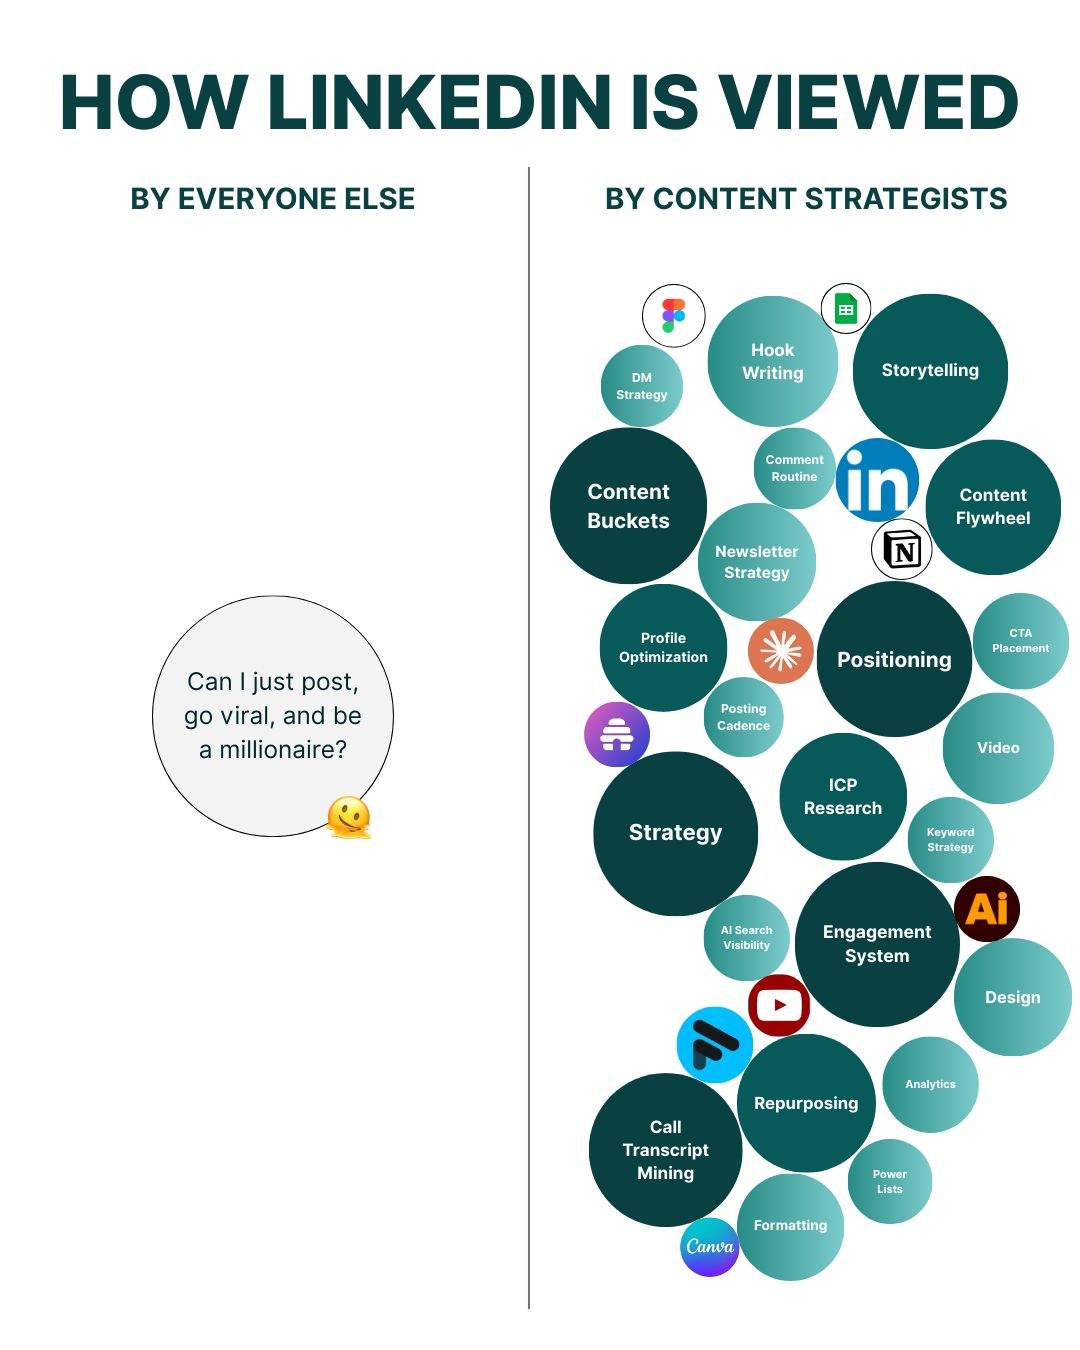
 Diandra EscobarArgues that consistent LinkedIn inbound requires a coordinated system of audience research, positioning, content, outreach and analytics, built in sequence.
 365 interactions · 1d agoTrending Creator
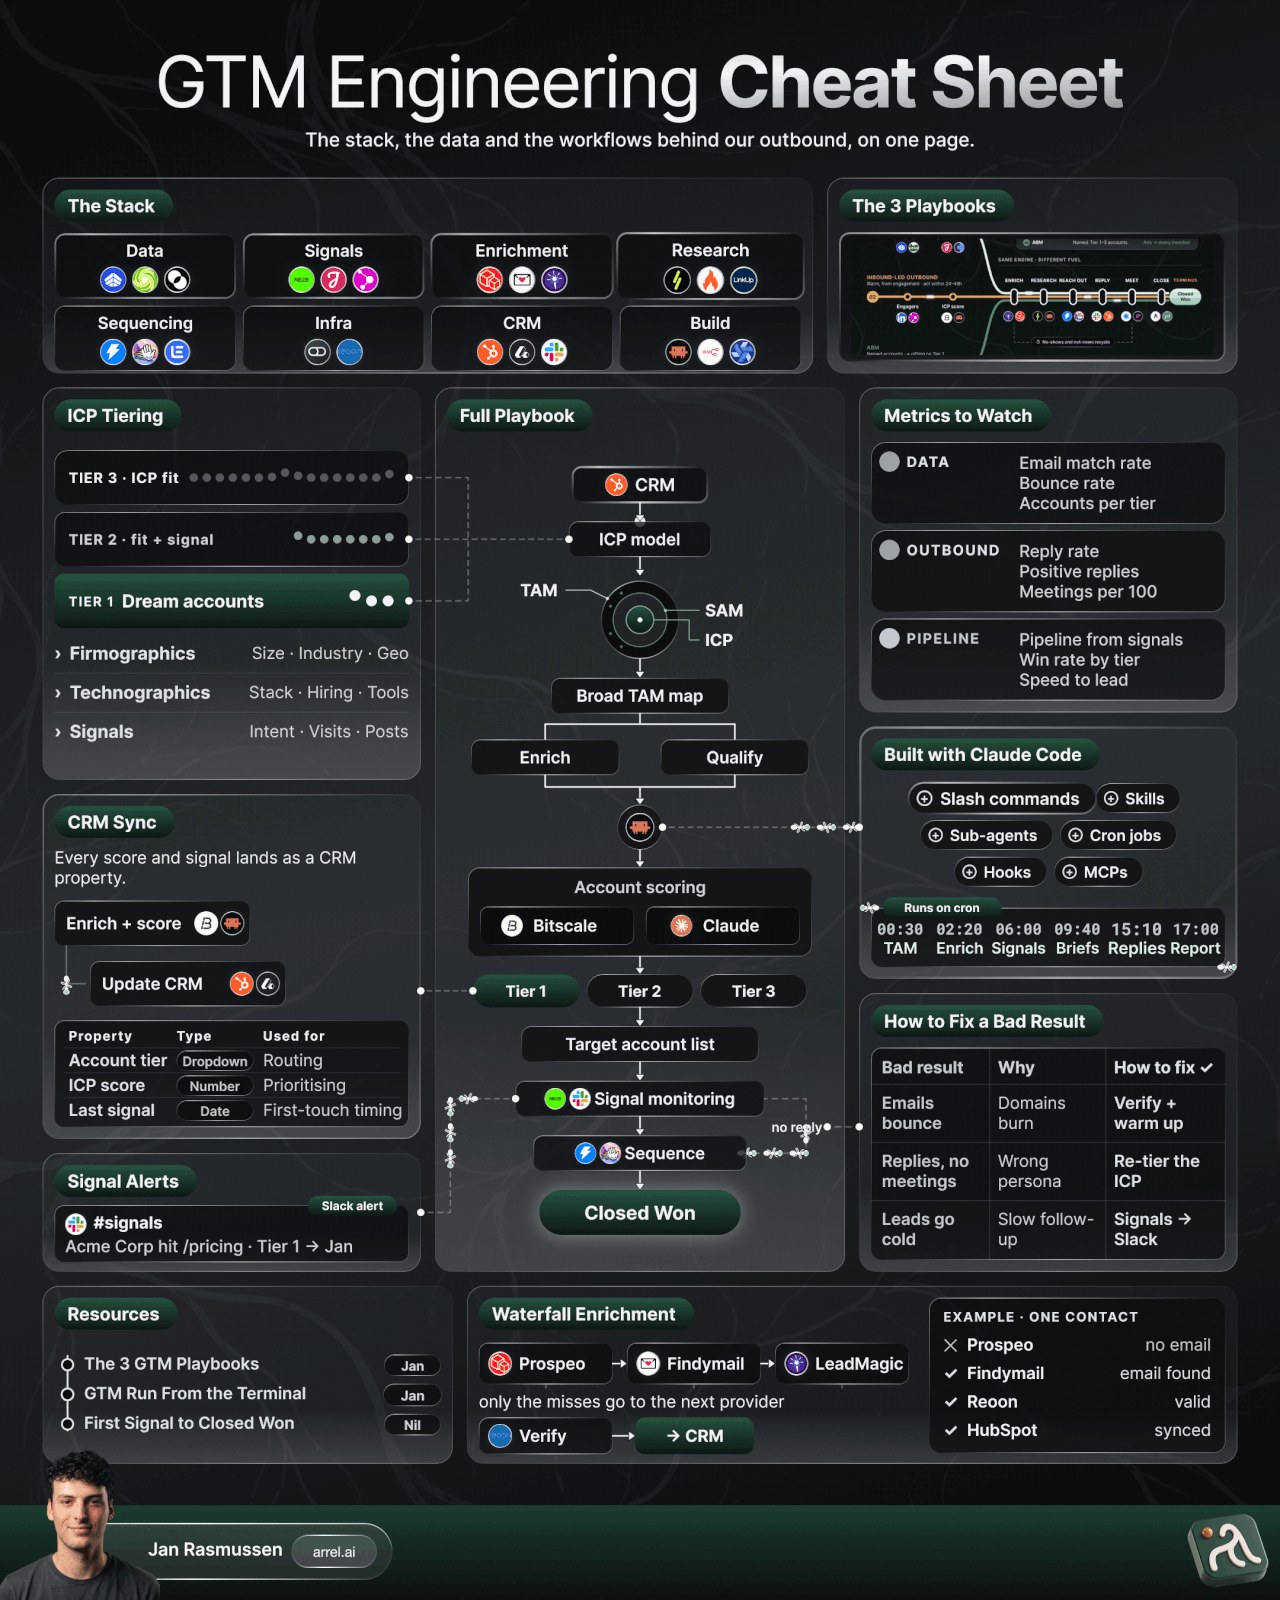
 Jan RasmussenProposes a B2B GTM engineering workflow connecting customer profiling, account tiers, enrichment, buying signals, outreach and CRM synchronization, with scheduled automation and performance metrics.
 359 interactions · 13h agoTrending Creator
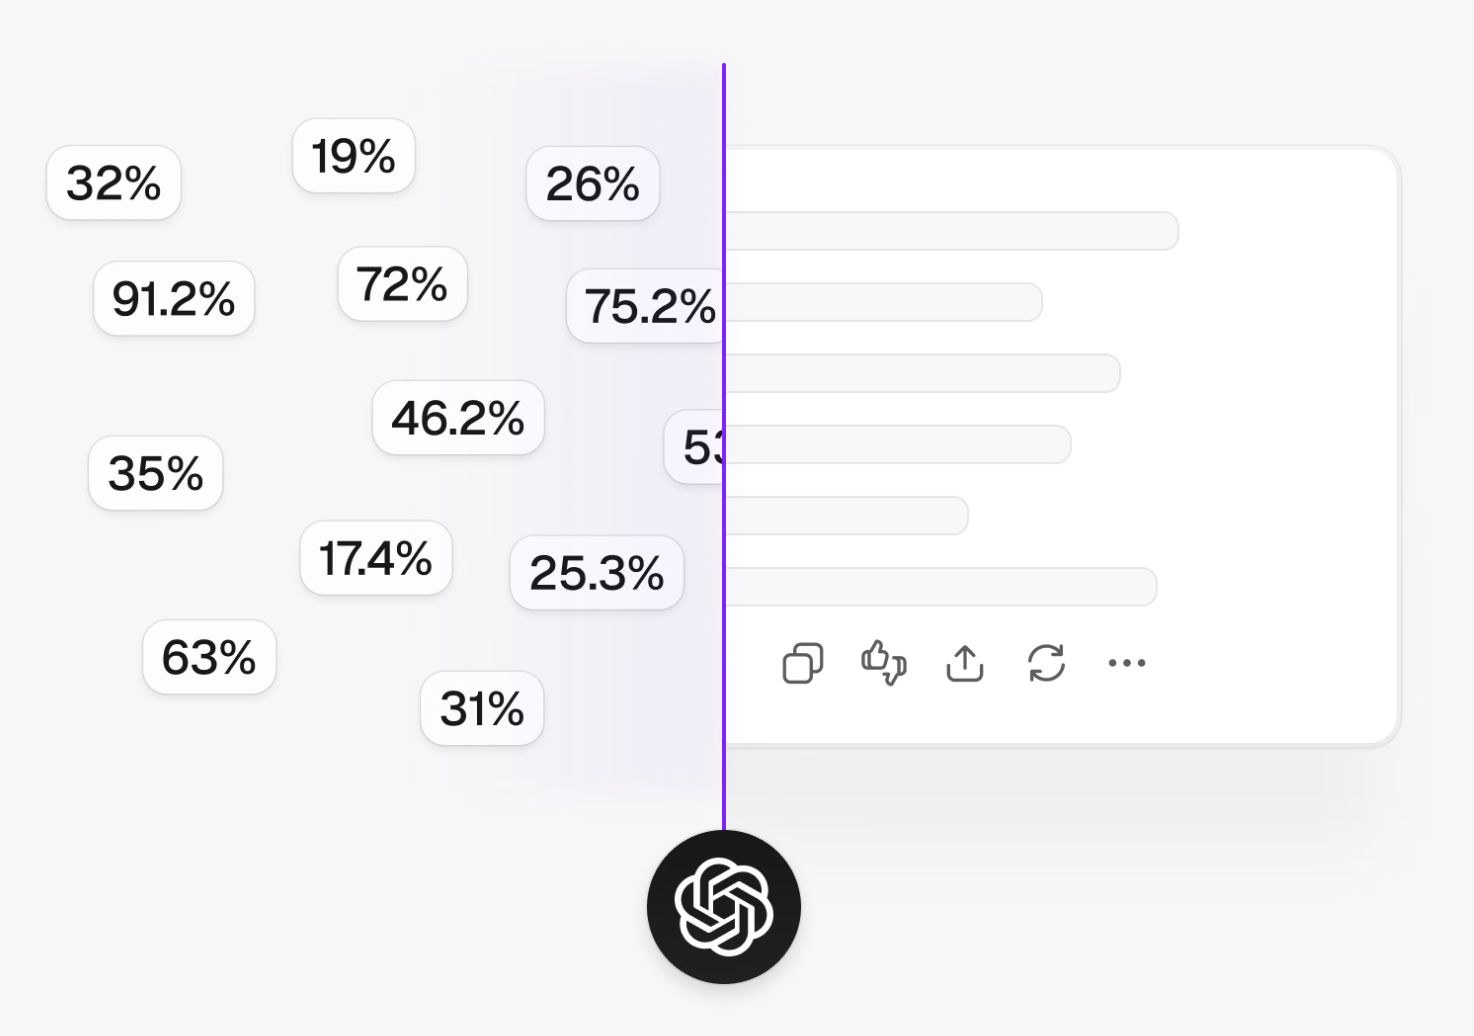
 Steve TothReports that ChatGPT cited Metehan Yeşilyurt’s fabricated statistics pages over 10,000 times despite Google deindexing them, warning about fabricated data spreading through AI citations.
 353 interactions · 2d agoTrending Creator
 Melissa RosenthalReports LinkedIn is testing a feed limited to connections and followed accounts, arguing it could reduce company page reach while page inclusion remains unclear.
 343 interactions · 2d agoTrending Creator
 Nick PalaszArgues AI outbound amplifies bad contact data, promotes BetterContact for validated mobile numbers, and says SDRs remain essential for turning replies into conversations.
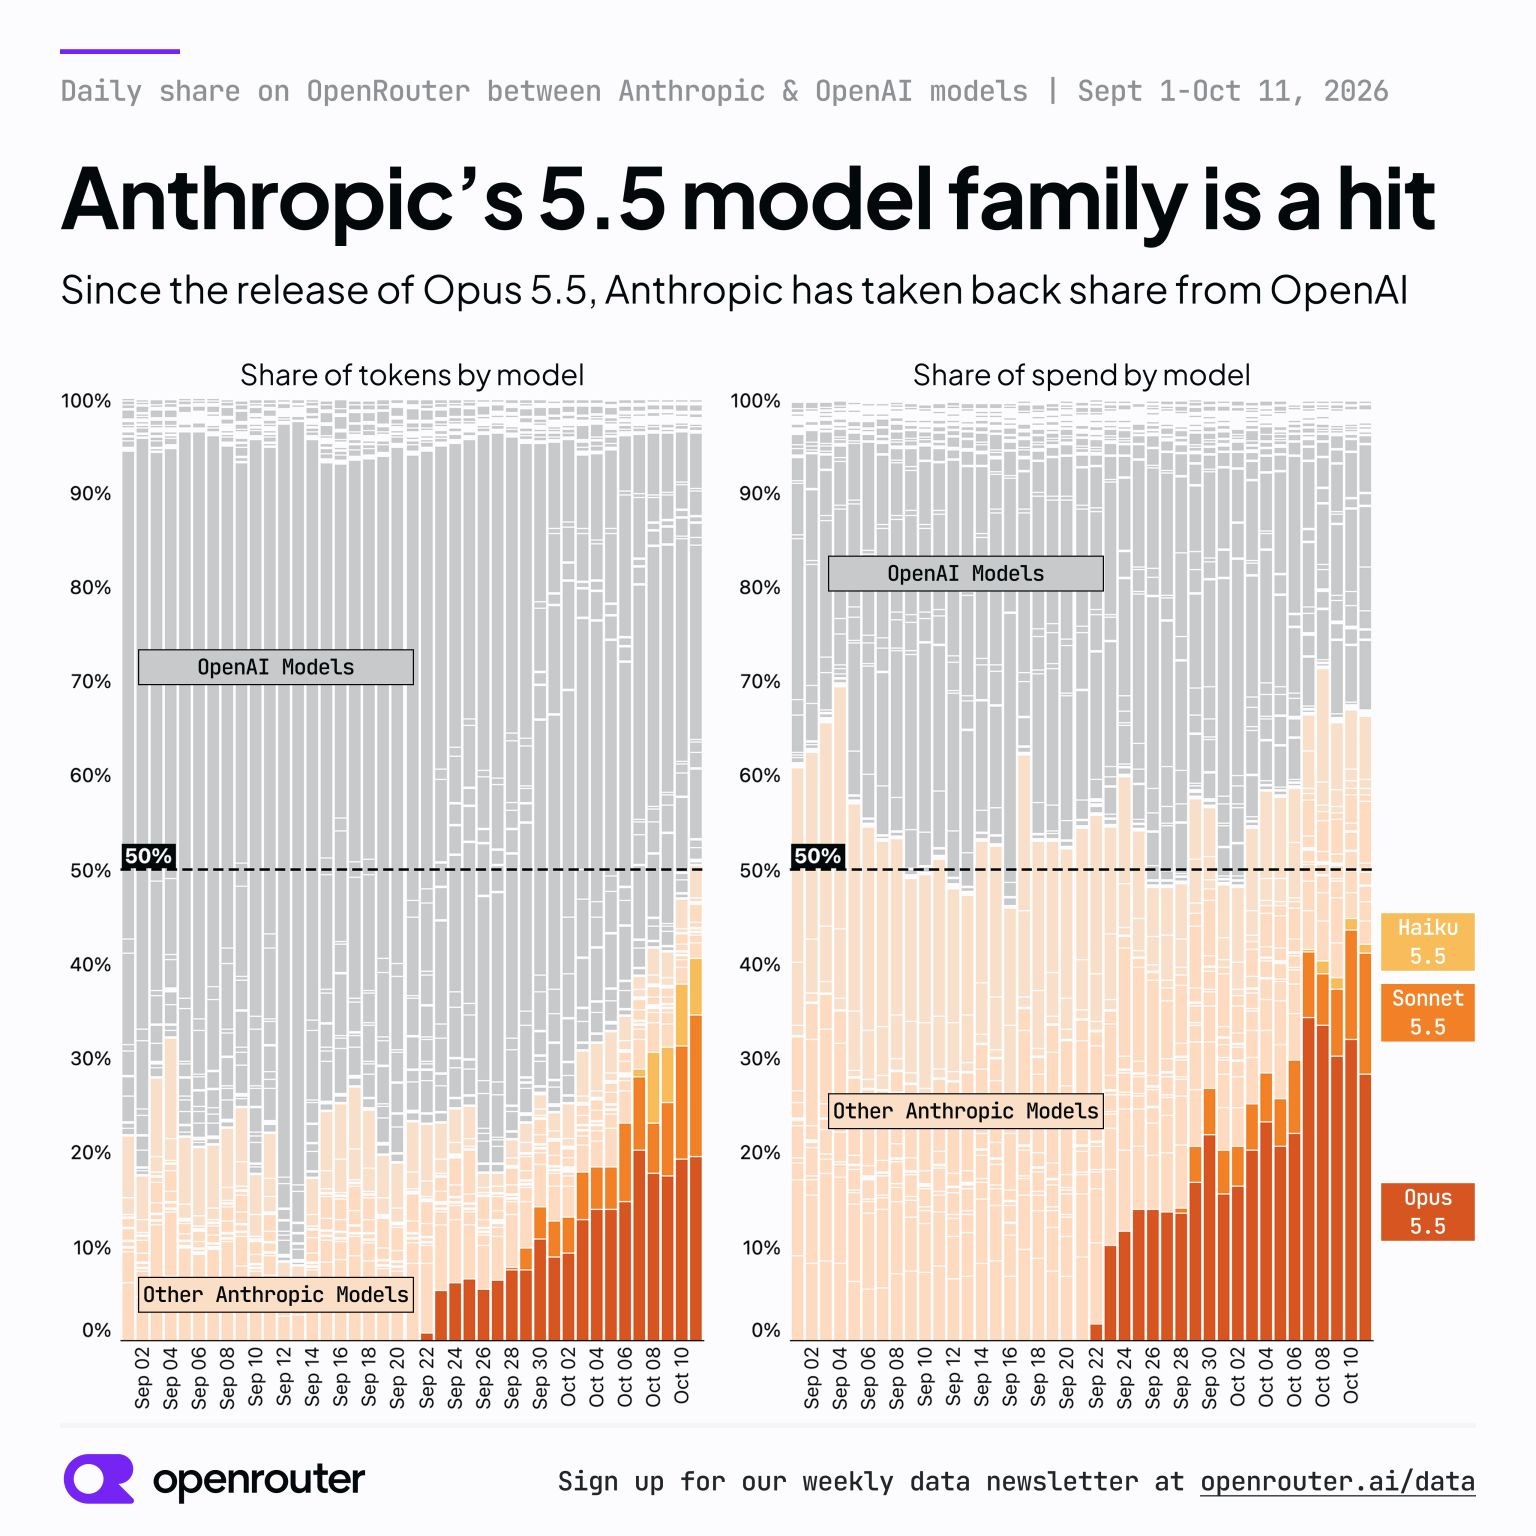
 336 interactions · 1d agoTrending CreatorPeter WalkerReports that Opus 5.5 boosted Anthropic’s OpenRouter token share and restored its spending lead over OpenAI, with Haiku and Sonnet also gaining share.
 285 interactions · 1d agoTrending Creator
 Lenny RachitskyShares takeaways from Josh Woodward emphasizing emerging technical possibilities, problem focus, emotional signals of product-market fit, unlearning, and autonomy for labs teams.
 236 interactions · 1d agoTrending CreatorMaja VojeRecommends 20 newsletters from 207 subscriptions, covering GTM strategy, GTM engineering, AI workflows, marketing and demand, and revenue intelligence.
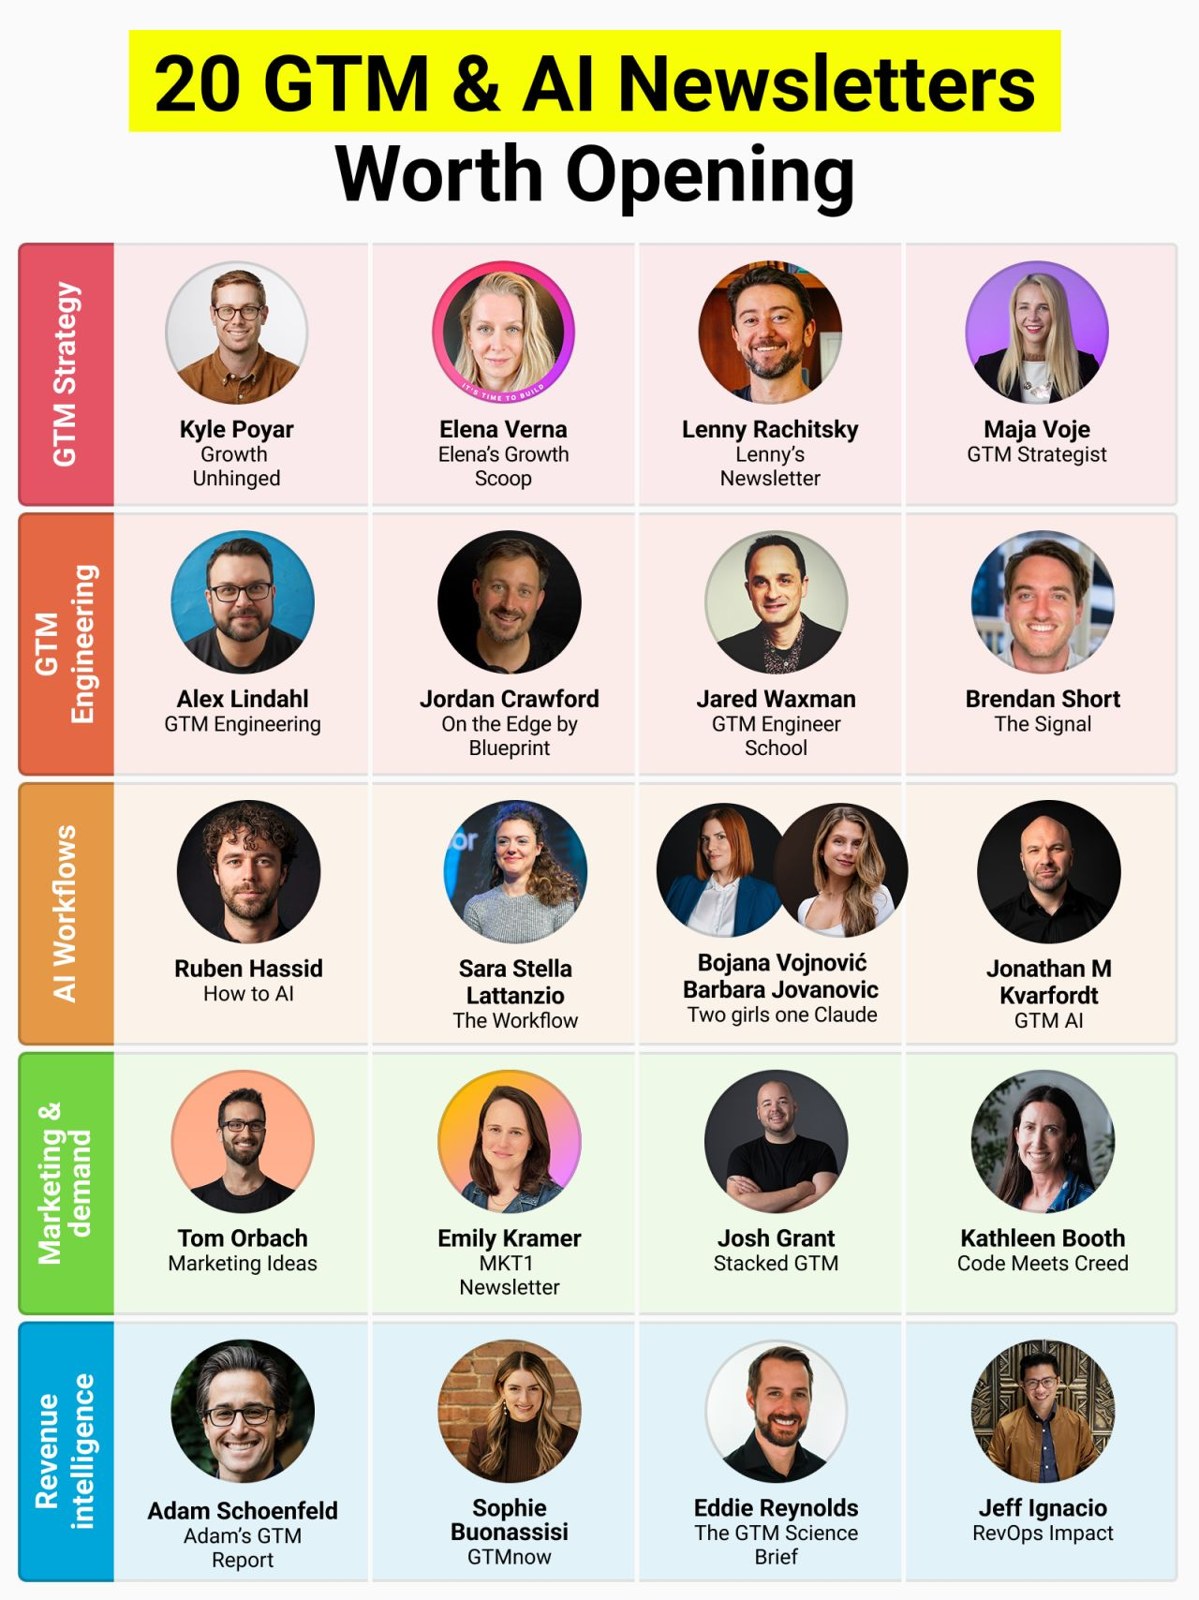 236 interactions · 2d agoTrending Creator
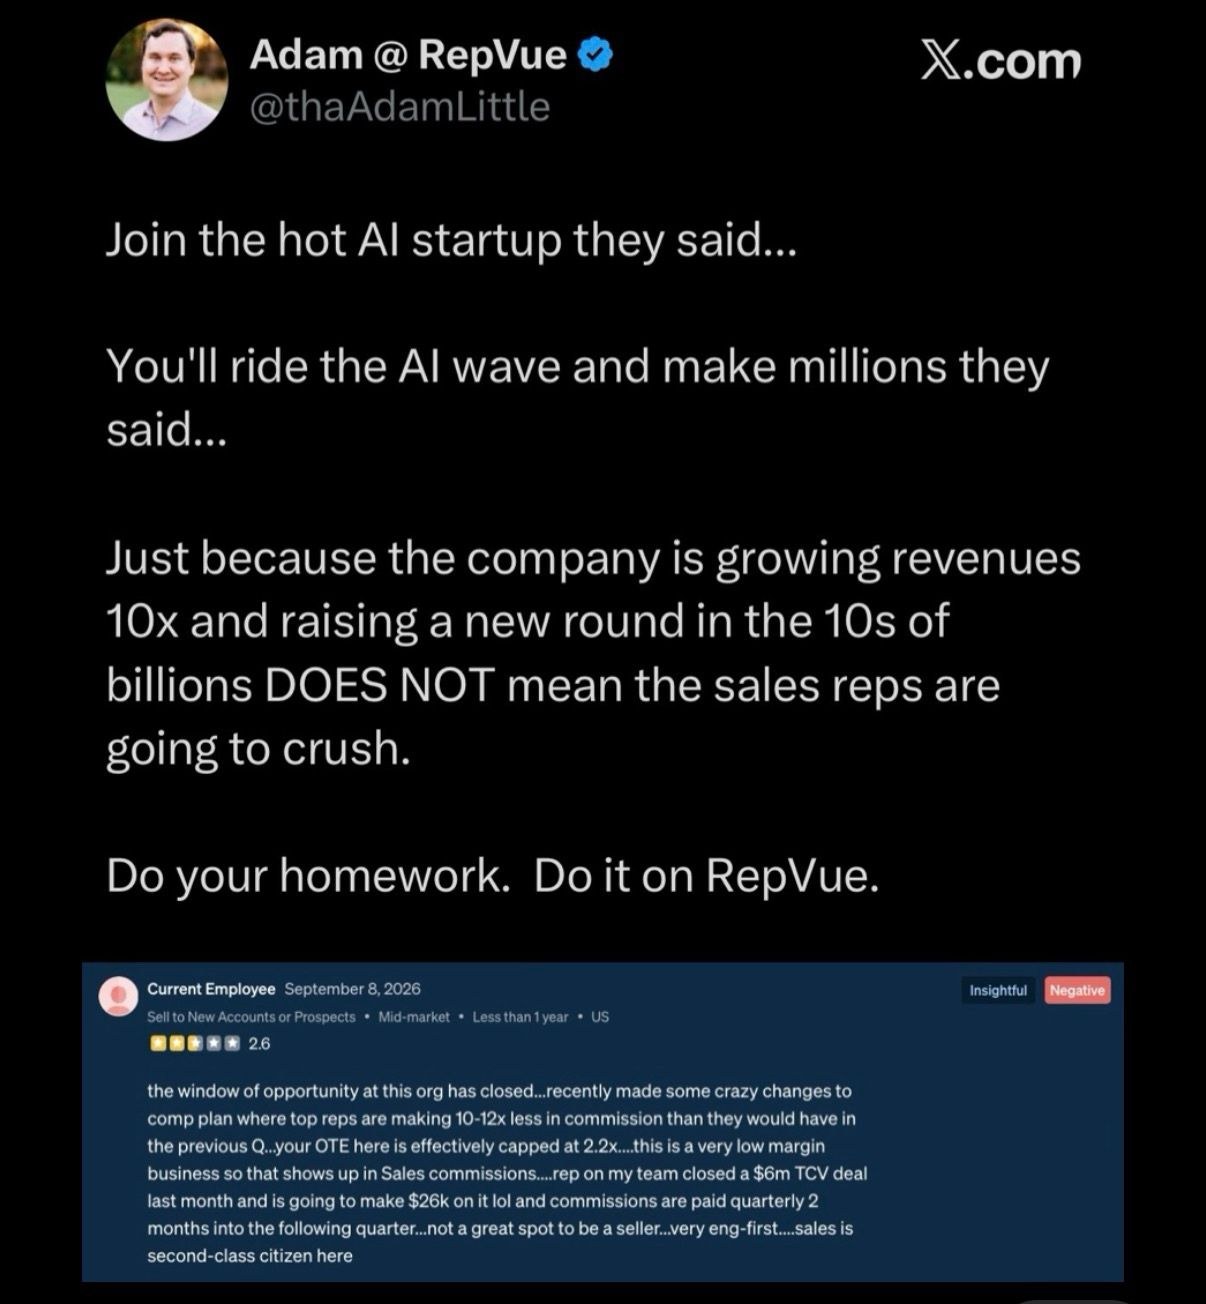
 Kyle AsayUrges account executives to evaluate commission limits, company sustainability, earning potential, territories, targets, and mission conviction alongside growth and valuation when considering jobs.
 230 interactions · 1d agoTrending topicAI Safety+81.2% vs prior 30d · 2.0% of the conversationTrending topicAI-Driven Advertising+72.8% vs prior 30d · 0.7% of the conversationTrending topicBuying Groups+36.0% vs prior 30d · 1.8% of the conversationTrending topicObservability+34.1% vs prior 30d · 0.5% of the conversationTrending topicInfluencer Marketing & Creator Partnerships+33.3% vs prior 30d · 0.9% of the conversation
 Docket↑28 places in AI-Native GTM Challengers
 Cline↑6 places in Coding Agents & Harnesses for GTM
 Sequel↑40 places in Traditional SaaS Going Headless
 Ploy↑11 places in AI-Native GTM Challengers
 Twilio↑11 places in GTM Developer Tools
Trending Topics
Market Moves
 78 engagements · 1.2× usualPost ↗
 1,822 engagements · 5.3× usualPost ↗
 153 engagements · 4.6× usualPost ↗
 220 engagements · 0.9× usualPost ↗
 M225 engagements · 3.0× usualPost ↗D1,391 engagements · 12.9× usualPost ↗
GTM Tech Index
Latest Posts
Oct 8How I'm buildingthe agents, workflows, and tools behind my one-person business.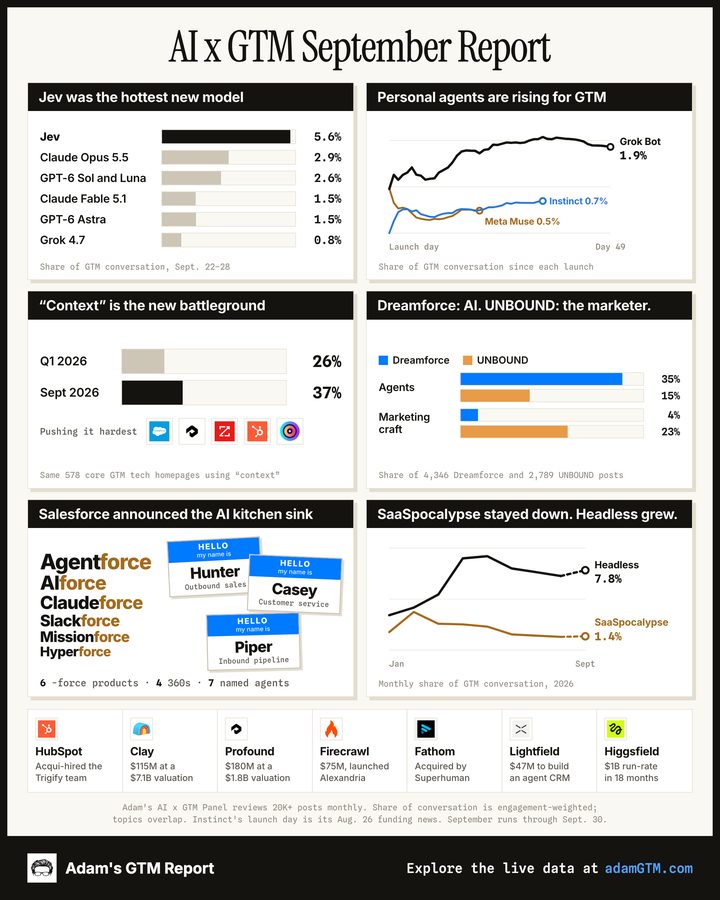 Oct 1Everything I measured in AI x GTM -- September reportfull EOM readout: 73 market moves, personal agents vs models, GTM's big rounds, the battle for GTM context, and Dreamforce vs Unbound.
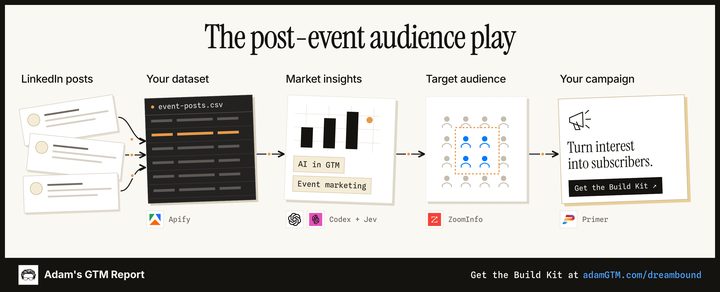 Sep 24My post-conference playbookHow to collect the conversation, find an angle, and build a unique audience. Lessons from Dreamforce and UNBOUND.
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
All topics
BetaFigures move as the panel grows and definitions sharpen.
+8.1%vs prior 30d-16.6%vs prior 30d-5.1%vs prior 30d+20.5%vs prior 30d-3.2%vs prior 30d -22.5%vs prior 30d-13.2%vs prior 30d-40.9%vs prior 30d+4.7%vs prior 30d-15.2%vs prior 30d
 +226%vs prior 30d-60.3%vs prior 30d-15.1%vs prior 30d+58.9%vs prior 30d-16.0%vs prior 30d-9.6%vs prior 30d-29.6%vs prior 30d
 +43.5%vs prior 30d+30.9%vs prior 30d+16.5%vs prior 30d+18.9%vs prior 30d
 +13.2%vs prior 30d-1.6%vs prior 30d+20.8%vs prior 30d-9.3%vs prior 30d-22.6%vs prior 30d-40.9%vs prior 30d+70.5%vs prior 30d-26.6%vs prior 30d-30.9%vs prior 30d-1.3%vs prior 30d+14.1%vs prior 30d
 -27.5%vs prior 30d-46.3%vs prior 30d+32.4%vs prior 30d
 -40.6%vs prior 30d-41.2%vs prior 30d+391%vs prior 30d+1.0%vs prior 30d-41.5%vs prior 30d
 -6.1%vs prior 30d
 -17.9%vs prior 30d-24.7%vs prior 30d
 +12.7%vs prior 30d
 -59.4%vs prior 30d
 -34.3%vs prior 30d
 +41.7%vs prior 30d
 +7.1%vs prior 30d
 -26.8%vs prior 30d
 -52.9%vs prior 30d
 -2.9%vs prior 30d-42.9%vs prior 30d
 +15.3%vs prior 30d
 +19.5%vs prior 30d
 -19.1%vs prior 30d
 -5.3%vs prior 30d-45.0%vs prior 30d
 -23.2%vs prior 30d
 -59.1%vs prior 30d-26.7%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
Conversation share held near 26–28% from March through May, then declined through September, with the L30 down another 13.1%. Recent posts still reach for broad agent systems, but the concrete examples are narrower: deal-story visualization and user-triggered app actions, while autonomous workflows remain the next frontier.
Posts to understand this · as of Oct 12
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 71 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 91 |
| 6 | HubSpot | 88 |
| 7 | Salesforce | 94 |
| 8 | Lovable | 60 |
| 9 | Replit | 57 |
| 10 | OpenClaw | 51 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO climbed into June, then lost share for three straight completed months; the L30 is nearly flat at minus 3.1%. The plateau reflects an unresolved split, not one catalyst: HubSpot sells measurable AI-search gains, while practitioners argue over SEO fundamentals versus tactics built specifically for AI answers.
Posts to understand this
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | Profound | 53 |
| 3 | HubSpot | 88 |
| 4 | Semrush | 48 |
| 5 | Clay | 91 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 39 |
| 8 | Salesforce | 94 |
| 9 |  Customer.io | 39 |
| 10 | Instantly | 63 |
How software exposes its data and actions so agents can use it directly.
Headless and agent interfaces jumped from March into April and May, then settled into a durable 7% to 8% band through September. The L30 is essentially flat, which makes the plateau meaningful. Cloudflare monetization, Notion’s developer surface, and Templafy’s MCP show agents gaining direct access to software, payments, and finished work.
Posts to understand this · as of Oct 11
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 88 |
| 5 | Clay | 91 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Grok Bot | 71 |
| 8 | Instantly | 63 |
| 9 | Lovable | 60 |
| 10 | Exa.ai | 46 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click discussion peaked locally in May, then declined through September; the L30 has edged up 4.4%. Early October adds a fresh critique of gated content, but not a completed recovery. The broader pattern favors accumulated brand authority and useful in-feed resources over forms, hacks, or forced clicks.
Posts to understand this
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | Profound | 53 |
| 3 | HubSpot | 88 |
| 4 | Semrush | 48 |
| 5 | Clay | 91 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 39 |
| 8 | Customer.io | 39 |
| 9 | Instantly | 63 |
| 10 |  Optimizely | 31 |
The people, tools and operating model behind custom go-to-market systems.
GTM Engineering rose through May, then declined across the next four completed months; the L30 is down 17.5%. Clay supplied major catalysts, including a CLI, agent plugin, internal stack details, and a $115 million Series D, but those launches did not restore the category’s spring momentum.
Posts to understand this
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Codex | 84 |
| 5 | Instantly | 63 |
| 6 | Salesforce | 94 |
| 7 | Prospeo | 52 |
| 8 |  FullEnrich | 44 |
| 9 | AI Ark | 46 |
| 10 | Cursor (Anysphere) | 78 |
How companies prove AI delivers enough value to move beyond a pilot.
After rising in April, conversation held near 7–8% through July, then fell in August and September. The last 30 days are down another 6.9%, while current posts focus on defining valuable use cases, adding governance and operating rigor, and clarifying what teams actually do with AI-created capacity.
Posts to understand this · as of Oct 12
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 88 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Grok Bot | 71 |
| 7 | OpenRouter | 53 |
| 8 | Clay | 91 |
| 9 | ElevenLabs | 55 |
| 10 | Nooks | 48 |
How teams use buyer signals to decide who to target, when and why.
Signal-based sales and ABM declined from March through August, then recovered some ground in September. The L30 is up 8%, but the L90 remains down 23%, so this is a modest current lift within a longer contraction. Recent evidence favors operational proof: Orb connected scattered intent data, while Zoom tied signals to revenue action.
Posts to understand this · as of Oct 11
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | HubSpot | 88 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 63 |
| 6 | Codex | 84 |
| 7 | Attio | 52 |
| 8 | Nooks | 48 |
| 9 |  6sense | 41 |
| 10 | AI Ark | 46 |
How large companies move AI from small pilots into secure, useful production work.
Conversation share peaked in April as Vanta described AI running continuous security work, then eased through summer. It fell more sharply in August and September and remains down 5.3% over the last 30 days, while recent discussion centers on undocumented workflows, governance, model routing, and process management.
Posts to understand this · as of Oct 6
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 71 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Midjourney | 36 |
| 7 | Codex | 84 |
| 8 | Nooks | 48 |
| 9 | Clay | 91 |
| 10 | OpenRouter | 53 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Open versus closed models surged from June to a July peak, then declined through August and September. Nvidia’s open-model letter and Kimi K3’s claimed price-performance advantage helped fuel the peak; Mistral’s €3 billion round reinforced the sovereignty case later, but the L30 move is still down 20.4% while the 90-day level remains elevated.
Posts to understand this · as of Oct 6
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | OpenRouter | 53 |
| 4 | Salesforce | 94 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Grok Bot | 71 |
| 7 |  Together AI | 34 |
| 8 | Baseten | 46 |
| 9 | Vercel | 61 |
| 10 | HubSpot | 88 |
How companies keep agents secure, accountable and under control as they take on real work.
Share climbed steadily from March through July, then fell in August and September; the last 30 days are down 5%, while October remains partial. The conversation now spans centralized routing and observability, task-level evals in safe environments, and stepwise autonomy that keeps security risks visible and bounded.
Posts to understand this · as of Oct 11
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 94 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Grok Bot | 71 |
| 7 | OpenRouter | 53 |
| 8 | Vercel | 61 |
| 9 | LangChain | 47 |
| 10 | Clay | 91 |
How teams create, distribute and judge marketing content made with AI.
Conversation rose into May, softened in early summer, then jumped in August as new tools connected generation to delivery workflows. September gave back that spike, and L30 is down 13.9% as discussion shifts toward creating inside existing tools and checking AI content against company-specific performance data.
Posts to understand this · as of Oct 9
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Claude Code | 99 |
| 3 | Runway | 36 |
| 4 | HubSpot | 88 |
| 5 | Grok Bot | 71 |
| 6 | Salesforce | 94 |
| 7 | Codex | 84 |
| 8 | HeyGen | 33 |
| 9 | Lovable | 60 |
| 10 | Clay | 91 |
How AI changes what software companies build, charge for and deliver.
The conversation peaked in May, then lost share steadily through September; the L30 is down another 12.8%. No single event caused the slide. The discussion moved from headline price cuts at ElevenLabs toward operating proof points: Salesforce defended SaaS economics, while Noble described the harder work behind service-as-software.
Posts to understand this · as of Oct 12
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Lovable | 60 |
| 6 | ZoomInfo | 50 |
| 7 | Replit | 57 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Nooks | 48 |
| 10 | Gong | 64 |
How companies build trust and stand out when AI makes content cheap and abundant.
Brand and authenticity held a broad three-to-four-percent range through August, then dropped sharply in September and is down another 22.2% over the last 30 days. August’s debate centered on AI slop, human credibility, and Clay’s writing manifesto; September’s narrower critique of scaled AI content did not sustain that intensity.
Posts to understand this
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Clay | 91 |
| 5 | Lovable | 60 |
| 6 | Nooks | 48 |
| 7 | Ahrefs | 51 |
| 8 | Codex | 84 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Substack | 53 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal agents broke out in September, and the last 30 days accelerated 188.4%; October’s first 13 days offer early context, not a finished monthly move. The rise spans personal execution and commerce: Halligan’s Hal handles email and meetings, while Sierra, Meta, Stripe, Shopify, and Walmart are defining how agents transact with businesses.
Posts to understand this
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 71 |
| 2 | Codex | 84 |
| 3 | Claude Code | 99 |
| 4 | OpenClaw | 51 |
| 5 | HubSpot | 88 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Salesforce | 94 |
| 8 | Midjourney | 36 |
| 9 | Vercel | 61 |
| 10 | ElevenLabs | 55 |
How AI changes software pricing, usage costs and gross margins.
Discussion rose from March through June, then fell each full month through September and is down 19.2% over the last 30 days. The debate has narrowed from exploding token demand to cost control: open models pushed prices down, enterprises set spending limits, and Factory reported production inference savings as routed volume grew.
Posts to understand this · as of Oct 7
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Codex | 84 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Vercel | 61 |
| 6 | Clay | 91 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Lovable | 60 |
| 9 | OpenRouter | 53 |
| 10 | Replit | 57 |
How people and agents share work, hand off tasks and make decisions together.
Multi-Player AI spiked in May around Dust’s case for shared human-agent systems, then settled into a lower, unusually steady band from July through September. Grok Bot and Notion’s sub-agent handoffs kept the operating model concrete, but they did not restart the climb. The L30 move is now slightly negative.
Posts to understand this · as of Oct 11
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | HubSpot | 88 |
| 4 | Salesforce | 94 |
| 5 | Clay | 91 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Attio | 52 |
| 8 | Grok Bot | 71 |
| 9 | Granola | 52 |
| 10 |  Viktor | 33 |
How teams track and control the cost of models, tokens and agent work.
Token-cost conversation rose steadily from March to July, then fell in August and September; L30 is down another 28.8%. No single event explains the curve. The pattern moved from broad concern about exploding usage toward concrete controls and margin choices, including Rippling’s spend console and Harvey’s reported shift toward open-weight models.
Posts to understand this · as of Oct 12
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 71 |
| 5 | Salesforce | 94 |
| 6 | OpenRouter | 53 |
| 7 | LangChain | 47 |
| 8 | Baseten | 46 |
| 9 | Clay | 91 |
| 10 | Cline | 28 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
Conversation fell from March’s high, briefly rebounded in May, then softened into September; the L30 is down 35.8%. April’s marketer whiplash, June’s case for authentic product marketing, and September’s personal-brand results show the thread moving from broad frustration to concrete examples of trust earned through real voices.
Posts to understand this · as of Oct 6
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | HubSpot | 88 |
| 5 | Nooks | 48 |
| 6 | Lovable | 60 |
| 7 | Ahrefs | 51 |
| 8 | Customer.io | 39 |
| 9 | Grok Bot | 71 |
| 10 | Substack | 53 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context Engineering in GTM rose steadily from March to a June high, then declined through September; L30 is essentially flat at plus 0.6%. The lower plateau still has concrete product support: Clay combines CRM, usage, calls, email, and web signals, while the broader discussion has shifted from prompt craft toward persistent context and agent harnesses.
Posts to understand this · as of Oct 6
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Codex | 84 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Salesforce | 94 |
| 6 | Grok Bot | 71 |
| 7 | Clay | 91 |
| 8 | Profound | 53 |
| 9 | ZoomInfo | 50 |
| 10 | Apify | 52 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR conversation declined steadily from March through July, saw a modest August lift, then weakened again, with the last 30 days down 6.7%. The pattern moved from broad replacement claims and Ava 2.0’s autonomous BDR launch toward narrower operating proof, such as ElevenLabs using its own voice-based AI SDR for inbound.
Posts to understand this · as of Oct 8
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 88 |
| 5 | Instantly | 63 |
| 6 | Lovable | 60 |
| 7 | ElevenLabs | 55 |
| 8 | Grok Bot | 71 |
| 9 | Nooks | 48 |
| 10 |  Outreach | 46 |
Growth driven by people using the product before they talk to sales.
Product-Led Growth fell steadily from March through July, then stabilized in August and September; L30 is now up 14.9%. The recent lift has no single launch behind it: PostHog’s generous free tier supports renewed free-plan interest, while the broader discussion frames PLG and enterprise sales as motions companies eventually combine.
Posts to understand this · as of Oct 6
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Lovable | 60 |
| 4 | Clay | 91 |
| 5 | Replit | 57 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Nooks | 48 |
| 8 | Vercel | 61 |
| 9 | Ahrefs | 51 |
| 10 | Canva | 49 |
Low-quality AI content and the fight to make automated work worth reading.
AI Slop climbed sharply in April and held near its high through June, then cooled unevenly, with an August bounce followed by a steeper September drop. The conversation shifted from broad frustration toward operating fixes: stronger context, governance, and repeatable Claude workflows. That practical turn has not stopped the decline, with L30 down 5.7%.
Posts to understand this · as of Oct 11
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Codex | 84 |
| 4 | Clay | 91 |
| 5 | Salesforce | 94 |
| 6 | Webflow | 48 |
| 7 | Customer.io | 39 |
| 8 | Grok Bot | 71 |
| 9 | Midjourney | 36 |
| 10 | Optimizely | 31 |
The argument that agents and custom software will break the classic SaaS model.
SaaSpocalypse talk fell sharply after May, leveled briefly around August and September, and is essentially flat in the L30 at 0.4%. The plateau reflects a more grounded debate: Salesforce cited durable seats and low attrition, Beehiiv still buys core SaaS, and Default rebuilt around agent-ready data and infrastructure.
Posts to understand this · as of Oct 12
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 50 |
| 6 |  Monaco | 25 |
| 7 | Attio | 52 |
| 8 |  Clarify | 30 |
| 9 | Gong | 64 |
| 10 | Apify | 52 |
The choice between building software internally and buying another product.
Build-vs-buy discussion fell steadily from March through July, then held near 1% share in August and September; the L30 move is essentially flat. Recent posts frame the current debate around marketers and salespeople building their own tools, while Replit shows non-engineers using those tools in daily sales work.
Posts to understand this · as of Oct 7
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | ZoomInfo | 50 |
| 5 | Claude Code | 99 |
| 6 | Monaco | 25 |
| 7 | Apify | 52 |
| 8 |  Lightfield | 26 |
| 9 |  Momentum | 25 |
| 10 | Profound | 53 |
Ways to verify whether digital content or online activity came from a person or AI.
Conversation stayed small until an August spike around Anthropic’s EU AI Act watermarking plans and the immediate SEO debate. September gave most of that spike back, and the L30 measure is down 60.3%; Sitecore’s later C2PA workflow shows the issue narrowing from broad reaction to practical disclosure controls.
Posts to understand this · as of Oct 11
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Grok Bot | 71 |
| 3 | Claude Code | 99 |
| 4 | HeyGen | 33 |
| 5 | Granola | 52 |
| 6 | HubSpot | 88 |
| 7 | Replit | 57 |
| 8 | Runway | 36 |
| 9 | Substack | 53 |
| 10 | Vercel | 61 |
AI tools that write, edit, test and operate software alongside a human builder.
Conversation share slid steadily from 21.7% in March to 12.6% in September, with the L30 down another 18.7%. No single event explains the decline: practical launches from ColdIQ, Notion, and Databricks kept the category active, but none reversed the broader loss of attention.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 71 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 91 |
| 6 | Lovable | 60 |
| 7 | HubSpot | 88 |
| 8 | Replit | 57 |
| 9 | OpenClaw | 51 |
| 10 | Salesforce | 94 |
The frontier models and labs that provide the base layer for AI products.
Foundation-model share has moved in waves, with surges in June, July, and September rather than one sustained climb. September reached 10.6% as OpenAI hit 31% of OpenRouter spend and release cycles tightened; the L90 remains up 22.7%, though the L30 has eased 14.8%.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 71 |
| 4 | HubSpot | 88 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Salesforce | 94 |
| 7 | OpenRouter | 53 |
| 8 | Midjourney | 36 |
| 9 | OpenClaw | 51 |
| 10 | Vercel | 61 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO reached 7.958% in May, held near that level in June, then declined to 5.342% by September. The current L30 move is down 8.1%, despite concrete commercial proof such as Daydream’s $15 million round and a reported 25% revenue contribution from AI search, which suggests adoption persists while broad conversation cools.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | Profound | 53 |
| 3 | Semrush | 48 |
| 4 | HubSpot | 88 |
| 5 | Clay | 91 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 39 |
| 8 | Customer.io | 39 |
| 9 | Instantly | 63 |
| 10 | Optimizely | 31 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP spiked in April and May, then cooled through the summer and recovered slightly in September. Early experimentation, Anthropic’s Stainless acquisition, and later operational connectors show adoption broadening from simple generation into governed business actions. Still, the 2.5% L30 decline leaves the conversation slightly softer, with October only partial context.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 88 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Clay | 91 |
| 7 | Grok Bot | 71 |
| 8 | Instantly | 63 |
| 9 | FullEnrich | 44 |
| 10 | Lovable | 60 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
Enterprise AI reached its high point in April, then declined across most completed months through September. The L30 is nearly flat at plus 1.2%, which suggests stabilization rather than a rebound. Evidence shifted from infrastructure launches and acquisitions toward the harder adoption gap: companies may capture only 5% to 10% of available value.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | HubSpot | 88 |
| 5 | Nooks | 48 |
| 6 | 6sense | 41 |
| 7 | ElevenLabs | 55 |
| 8 | Grok Bot | 71 |
| 9 | OpenRouter | 53 |
| 10 |  Braze | 26 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce moved from negligible discussion to an August buildup and a sharp September spike around Salesforce’s flagship event. Informatica’s debut inside the Salesforce family and Crossbeam’s AgentExchange launch partnership supplied concrete news. The L30 remains up 48.5%; the lower early-October bar is partial context, not a completed reversal.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Apify | 52 |
| 4 | Codex | 84 |
| 5 | ZoomInfo | 50 |
| 6 | Outreach | 46 |
| 7 | Clay | 91 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Grok Bot | 71 |
| 10 | Lightfield | 26 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps declined steadily from March through August, then held roughly flat in September. The latest conversation has more edge: teams are debating whether to replace SaaS internally while Dreamforce discussions define a broader RevOps remit across signals, automation, and expansion. That pattern supports the 8.7% L30 lift, not yet a longer-term recovery.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 91 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Gong | 64 |
| 6 | n8n | 59 |
| 7 | Instantly | 63 |
| 8 | Attio | 52 |
| 9 | HeyReach | 53 |
| 10 | Lovable | 60 |
Measuring whether AI answers mention, cite and recommend a brand.
AI visibility jumped in June, then lost ground through September; the last 30 days are down another 11.1%, despite an elevated early October bar. No single launch explains the curve. The conversation now splits between practical AEO tactics and sharper doubts about whether prompt volume, answer variance, and brand tracking can be measured reliably.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Semrush | 48 |
| 3 | Ahrefs | 51 |
| 4 | AirOps | 39 |
| 5 | Claude Code | 99 |
| 6 | HubSpot | 88 |
| 7 | Grok Bot | 71 |
| 8 | Peec AI | 29 |
| 9 |  Similarweb | 33 |
| 10 |  Vector | 37 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid Media has moved in waves rather than one clean trend: it recovered from April, jumped in August, then gave back share in September. No single post explains the swings. The L30 and L90 moves are positive, with early October attention spanning Anthropic’s performance-marketing hire and low-cost automation for ad analysis and fatigue checks.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 91 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 63 |
| 5 | Salesforce | 94 |
| 6 | Gong | 64 |
| 7 | Granola | 52 |
| 8 | Lovable | 60 |
| 9 | Ahrefs | 51 |
| 10 | Codex | 84 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer success has declined from March through September, apart from a brief August lift, and the L30 is down 25.9%. The conversation moved from Rox automating renewals and expansion toward organizational consolidation at Vanta and a sharp Salesforce support failure, a pattern that puts efficiency promises beside unresolved service basics.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Lovable | 60 |
| 5 | Gong | 64 |
| 6 | Replit | 57 |
| 7 | ZoomInfo | 50 |
| 8 | Grok Bot | 71 |
| 9 |  Qualified | 25 |
| 10 | Attio | 52 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Conversation rose steadily from March through July, then dropped in August and held almost flat in September. No single event owns the curve: posts moved from Composio’s model-to-model agent tests to Vercel’s production feedback loop and Morgan’s cross-model benchmark work; the 26.2% L30 gain shows renewed momentum after that plateau.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 94 |
| 5 | OpenRouter | 53 |
| 6 | Grok Bot | 71 |
| 7 | LangChain | 47 |
| 8 | HubSpot | 88 |
| 9 | Cline | 28 |
| 10 | Vercel | 61 |
Email sent to people with no prior relationship to start a sales conversation.
Cold Email reached a May high, fell sharply through July, and continued a slower decline afterward; L30 is down 7.7%. The May spike aligns with Jason Bay’s 15x reply-rate claim for direct inbox sends, while later posts narrowed the discussion to relevance, personalization, and value-first tactics rather than broad channel enthusiasm.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Instantly | 63 |
| 2 | Claude Code | 99 |
| 3 | Clay | 91 |
| 4 | HubSpot | 88 |
| 5 | Prospeo | 52 |
| 6 | Lemlist | 48 |
| 7 | Apollo.io | 52 |
| 8 | Codex | 84 |
| 9 | FullEnrich | 44 |
| 10 | Salesforce | 94 |
Voice and chat software that talks with buyers and customers.
Conversation share climbed from spring through August, eased slightly in September, then rose 15.6% over the last 30 days. The visible timing spans OpenAI’s September voice API release and October activity around multilingual government pilots and enterprise consolidation, showing momentum across both product access and large-scale deployment.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | ElevenLabs | 55 |
| 3 | Grok Bot | 71 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 63 |
| 6 | Salesforce | 94 |
| 7 | Vector | 37 |
| 8 | Codex | 84 |
| 9 | Docket | 31 |
| 10 | LangChain | 47 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold outbound has followed a broad downward slope, with brief rebounds in May and early October context after steady erosion from June through September. No single event drove the decline; the posts instead show the category consolidating around execution fundamentals, from Nooks’ unified agent workspace to Gong’s five-minute response and Kyle Norton’s method for breaking buyer pattern recognition. The L30 is nearly flat, down 0.6%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Instantly | 63 |
| 5 | Nooks | 48 |
| 6 | HeyReach | 53 |
| 7 | Salesforce | 94 |
| 8 | Gong | 64 |
| 9 | FullEnrich | 44 |
| 10 | Prospeo | 52 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Prospecting climbed into May, then declined across June through September; the last 30 days are down 23%. Big launches from Nooks and Salesforce with ZoomInfo helped define the earlier high, while Clay’s September API and CLI release shows attention shifting from standalone research toward agent-run prospecting workflows.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | HubSpot | 88 |
| 5 | AI Ark | 46 |
| 6 | Instantly | 63 |
| 7 | Apollo.io | 52 |
| 8 | Grok Bot | 71 |
| 9 | Codex | 84 |
| 10 | HeyReach | 53 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand generation has followed a broad downward slope since March, interrupted only by a small August lift; the L30 is down 14.2%. No single announcement drove the decline. The evidence points to a structural squeeze as AI reduces content-gated journeys, founders delay demand-gen hiring, and lead systems optimize form fills instead of buyers.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Docket | 31 |
| 6 | Gong | 64 |
| 7 | Instantly | 63 |
| 8 | Webflow | 48 |
| 9 | Codex | 84 |
| 10 | Lovable | 60 |
The debate over AI risk, alignment, regulation and responsible development.
AI safety stayed near a low baseline through August, then spiked in September; both the 30-day and 90-day views remain more than 100% higher. The rise came from several fronts at once: Mistral shipped an open moderation model, a widely shared workplace-risk post cited an agent database failure, and Microsoft elevated humanity as the constraint on superintelligence.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | beehiiv | 51 |
| 4 | Salesforce | 94 |
| 5 | Grok Bot | 71 |
| 6 | HubSpot | 88 |
| 7 | Runway | 36 |
| 8 | ElevenLabs | 55 |
| 9 | Midjourney | 36 |
| 10 | Substack | 53 |
Sales and marketing coordinating around a defined set of target accounts.
ABM conversation fell from its March high, held near 2% through June, bottomed in July, recovered in August, then slipped slightly in September. The last 30 days are up 16.6%, while recent posts focus on new ABM platforms, contact-level activity, and buying-group signals.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 91 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 63 |
| 6 | 6sense | 41 |
| 7 | Nooks | 48 |
| 8 | FullEnrich | 44 |
| 9 | Codex | 84 |
| 10 | HeyReach | 53 |
The work of connecting marketing activity to pipeline and revenue.
Attribution fell from March, bounced in May, then settled into a narrow July-to-September plateau. The 36.6% L30 move shows current interest rising as zero-click discovery makes last-touch reporting less credible, while the sustained debate centers on combining self-reported sources, buyer engagement, and later pipeline rather than claiming simple causation.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Webflow | 48 |
| 6 | Semrush | 48 |
| 7 | Twilio | 43 |
| 8 | Docket | 31 |
| 9 | Gamma | 44 |
| 10 | Gong | 64 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Data enrichment trended down from March through September, with the 90-day view still off 39%. The last 30 days are up 7%, and Gong Enrich supplies a concrete current catalyst by bringing ten named third-party providers into Gong; earlier Clay moves show enrichment becoming infrastructure inside broader workflows rather than the whole product.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Instantly | 63 |
| 5 | Salesforce | 94 |
| 6 | Prospeo | 52 |
| 7 | AI Ark | 46 |
| 8 | Codex | 84 |
| 9 |  Findymail | 42 |
| 10 | HeyReach | 53 |
Mapping and winning the committee of people involved in a business purchase.
Buying-groups discussion dropped hard after March, then settled into a narrow range through September. The 32.3% L30 move points to renewed attention around practical committee selling: executive multithreading, internal consensus, procurement, and explicit stakeholder maps. The pattern is operational rather than event-led, with Clay’s $60,000 deal providing the clearest proof point.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | AI Ark | 46 |
| 6 |  BuiltWith | 33 |
| 7 | HeyReach | 53 |
| 8 | Instantly | 63 |
| 9 | RB2B | 47 |
| 10 | Vector | 37 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
Conversation jumped in August and held near that level in September, but it is now easing, down 14% over the last 30 days. Late-August live generation and September small-business research focused attention on faster creation and publishing barriers, while October’s Syren launch shows new browser workflows are still arriving despite lower near-term volume.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Runway | 36 |
| 3 | HeyGen | 33 |
| 4 | Grok Bot | 71 |
| 5 | Claude Code | 99 |
| 6 | Replit | 57 |
| 7 | ElevenLabs | 55 |
| 8 | HubSpot | 88 |
| 9 | Salesforce | 94 |
| 10 | Codex | 84 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
GTM Data Infrastructure declined from March through May, rebounded in June, then fell each completed month through September. The L30 measure is down another 13.4%, while the first eight October days provide only early context. The posts show consolidation and interface change: Pocus joined Apollo, Salesforce connected CRM data to Claude, and RevOps stacks shifted toward agents and orchestration.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Gong | 64 |
| 6 | Attio | 52 |
| 7 | Nooks | 48 |
| 8 | n8n | 59 |
| 9 | Grok Bot | 71 |
| 10 |  GrowthLoop | 29 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise Sales has trended down from March, with only a brief August lift before another September decline. No single event explains the curve. The posts show attention concentrating around production readiness, moving consumer adoption upmarket, and the craft behind large deals; the L30 move is only slightly positive against a weaker 90-day trend.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Clay | 91 |
| 5 | 6sense | 41 |
| 6 | Gong | 64 |
| 7 | Lovable | 60 |
| 8 | 1mind | 37 |
| 9 | Clarify | 30 |
| 10 | Claude Code | 99 |
The training, fine-tuning and modeling work underneath AI products.
Machine learning rose steadily from July through September, supported by concrete model progress in robotics and world-action systems. Skild AI introduced one-shot task learning, Black Forest Labs paired stronger benchmark results with fewer parameters, and AMD’s World Labs deal tied model development more closely to hardware; L30 remains up 5.9%.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | LangChain | 47 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Grok Bot | 71 |
| 6 | Baseten | 46 |
| 7 | OpenRouter | 53 |
| 8 | Vercel | 61 |
| 9 | Cline | 28 |
| 10 | Supabase | 48 |
Programmable tools used to build custom go-to-market systems, agents and automations.
Share accelerated into a May high as Claude Code became a programmable layer for cold email and connected GTM stacks. It then declined through August and stabilized slightly in September; the 27.7% L30 drop shows that October’s early stack discussion has not yet rebuilt the spring momentum.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Prospeo | 52 |
| 2 | FullEnrich | 44 |
| 3 | Instantly | 63 |
| 4 | Clay | 91 |
| 5 | HubSpot | 88 |
| 6 | Claude Code | 99 |
| 7 | AI Ark | 46 |
| 8 | Findymail | 42 |
| 9 |  BetterContact | 42 |
| 10 | HeyReach | 53 |
The choice of go-to-market motion and the plan for making it work.
GTM strategy was volatile through May, then declined across the summer and into September; the L30 is down 20.2%. No single announcement explains the curve. Attention fragmented across distinct operating models, from Swan AI’s agent-run motion to Notion’s workflow-first commercial roles and executive-brand account outreach.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | Nooks | 48 |
| 4 | Salesforce | 94 |
| 5 | HubSpot | 88 |
| 6 | Gong | 64 |
| 7 | Ahrefs | 51 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Apollo.io | 52 |
| 10 | Attio | 52 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability climbed steadily to a May high, then settled into a lower, uneven band, with only a brief August rebound. The last 30 days fell 30.8%, so October’s partial bar does not mark a recovery. Conversation has shifted from broad operator pain toward specific infrastructure moves and practical fixes, including Infobip’s SocketLabs acquisition and Customer.io’s sender-reputation guidance.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Instantly | 63 |
| 3 | HubSpot | 88 |
| 4 | Claude Code | 99 |
| 5 | Prospeo | 52 |
| 6 | Lemlist | 48 |
| 7 | AI Ark | 46 |
| 8 | Apollo.io | 52 |
| 9 | Salesforce | 94 |
| 10 | n8n | 59 |
People asking AI assistants for answers instead of using a traditional search engine.
AI Search discussion built from April to a June high, then declined for three straight months. AutoRFP’s reported ChatGPT traffic gains helped make the channel tangible early, while later evidence split Google ranking from AI citations. Even strong September claims about AI Overviews cutting clicks did not arrest the cooling, and L30 is down 22.7%.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | Semrush | 48 |
| 3 | Profound | 53 |
| 4 | HubSpot | 88 |
| 5 | Clay | 91 |
| 6 | Gamma | 44 |
| 7 | Gong | 64 |
| 8 | Salesforce | 94 |
| 9 | 6sense | 41 |
| 10 |  AthenaHQ | 20 |
How companies create demand, build trust and reach buyers at other businesses.
B2B marketing fell hard from March to April, stabilized through June, then moved to a lower band from July through September. No single launch explains the decline. The posts show a fragmented playbook across paid, AI search, founder social, creators, and human credibility, while the L30’s 2.6% gain suggests stabilization rather than a clear comeback.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | Clay | 91 |
| 5 | Customer.io | 39 |
| 6 | Optimizely | 31 |
| 7 | Webflow | 48 |
| 8 | Gong | 64 |
| 9 |  Primer | 28 |
| 10 | Ahrefs | 51 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence slid from 1.682% in March to 0.894% in June, rebounded to 1.494% in July, then eased through September. The L30 is nearly flat at -0.5%, while September’s conversation centered on two revenue orchestration leader placements and Momentum’s role in Salesforce Hunter’s data foundation.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 88 |
| 4 | Clay | 91 |
| 5 | Outreach | 46 |
| 6 |  Salesloft | 41 |
| 7 | Claude Code | 99 |
| 8 | Grok Bot | 71 |
| 9 | Instantly | 63 |
| 10 | Lovable | 60 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
HubSpot UNBOUND had two event-led bursts: the April rebrand announcement, then a much larger September surge around the Boston conference. The September peak was backed by 1,300 partners and roughly 13,000 attendees; L30 share is still up 105.1%, while the first eight October days are only early context.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 91 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Profound | 53 |
| 6 | Apify | 52 |
| 7 |  Breeze | 24 |
| 8 | Lightfield | 26 |
| 9 | Vector | 37 |
| 10 | ZoomInfo | 50 |
The durable knowledge and memory an agent can use across tasks and sessions.
Agent memory rose steadily into June, then dropped hard in August and stayed nearly flat in September. The evidence moved from personal second-brain systems toward shared, continuously refreshed company context, including ZoomInfo data inside Slack and current account relationships. L30 is up 16.1%, pointing to renewed attention after that lower plateau.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Claude Code | 99 |
| 5 | Clay | 91 |
| 6 | Profound | 53 |
| 7 | Attio | 52 |
| 8 | Grok Bot | 71 |
| 9 |  Octave | 31 |
| 10 | ZoomInfo | 50 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales Leadership held near 2.3% in April and May, then declined steadily; its L30 share is down 12.7%. The conversation has narrowed around what leaders do directly: Replit wants a hands-on VP of Sales, while other posts stress spotting talent early and retaining reps long enough to build expertise.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 88 |
| 4 | Clay | 91 |
| 5 |  MoEngage | 22 |
| 6 |  TitanX | 33 |
| 7 | 6sense | 41 |
| 8 | Airtable | 49 |
| 9 | Claude Code | 99 |
| 10 | Codex | 84 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Revenue agents fell steadily from the April high through August, then stabilized with a modest September recovery and a 7.8% L30 increase. Ami’s September launch supplied the clearest recent catalyst, while earlier attention came from Fin’s sales role and Gong’s growth claims; the category remains down 48.7% over 90 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 91 |
| 4 | Nooks | 48 |
| 5 |  Sumble | 32 |
| 6 | HubSpot | 88 |
| 7 |  Rox | 31 |
| 8 |  Clearskies | 22 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | ZoomInfo | 50 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search strategy rose sharply from April through June, then declined for three straight full months; the latest 30 days are down another 17.2%. No single event explains the curve. The posts show a broader reset from keyword-led inbound toward multi-channel demand, AI-native content operations, and harder scrutiny of AI citation metrics.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | HubSpot | 88 |
| 3 | Semrush | 48 |
| 4 | AirOps | 39 |
| 5 | Claude Code | 99 |
| 6 | Similarweb | 33 |
| 7 |  SparkToro | 28 |
| 8 | Codex | 84 |
| 9 | Customer.io | 39 |
| 10 | FullEnrich | 44 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product marketing dropped sharply after March, then held near 1.5% to 1.8% from May through August before another September decline. No single event explains the slide. The strongest spring conversation recast the work around marketing engineers, while later posts returned to practical launch discipline rather than a fresh category-wide catalyst.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Gong | 64 |
| 4 | Profound | 53 |
| 5 | Salesforce | 94 |
| 6 | Ahrefs | 51 |
| 7 | Lovable | 60 |
| 8 | Optimizely | 31 |
| 9 | Apify | 52 |
| 10 | Codex | 84 |
How companies sell to other companies and how business buyers make decisions.
B2B sales conversation has oscillated rather than followed one clean arc, with a May rebound, softer summer levels, and a September decline. The last 30 days are nearly flat at down 2%; the tension is between AI systems that organize deals and research, and a renewed push for events, direct mail, and trusted human contact.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 91 |
| 4 | 6sense | 41 |
| 5 | Claude Code | 99 |
| 6 |  DemandScience | 28 |
| 7 | Hermes Agent | 37 |
| 8 | OpenClaw | 51 |
| 9 | Ahrefs | 51 |
| 10 | Airtable | 49 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing stayed elevated but uneven through June, dropped in July, briefly recovered in August, then stepped down sharply in September; the L30 is down 34.7%. The posts point to a shift away from content volume toward operating systems, original customer knowledge, and credible third-party voices, which narrows the old production-led conversation.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Ahrefs | 51 |
| 4 | Clay | 91 |
| 5 | Grok Bot | 71 |
| 6 | Codex | 84 |
| 7 | Customer.io | 39 |
| 8 | Instantly | 63 |
| 9 | RB2B | 47 |
| 10 | Semrush | 48 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement declined from March, briefly recovered in July, then fell again through September. The L30 is now up 8.9%, an early improvement against a 22.1% L90 decline. Current evidence favors concrete coaching systems: repeated practice, role-aware deal support, and measured ramp improvements rather than one-off training sessions.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Gong | 64 |
| 3 | Customer.io | 39 |
| 4 | Claude Code | 99 |
| 5 | Clay | 91 |
| 6 | Cursor (Anysphere) | 78 |
| 7 |  Highspot | 29 |
| 8 | Instantly | 63 |
| 9 | Nooks | 48 |
| 10 | Salesforce | 94 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting discussion peaked in May, bounced modestly in July, then declined through September; the last 30 days are down 28.6%. The strongest posts track the conversation from forecast-risk automation in June and deal validation in July to recent demand for quicker pipeline updates after forecast calls.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Gong | 64 |
| 6 | n8n | 59 |
| 7 |  Clari | 33 |
| 8 | Nooks | 48 |
| 9 | Zapier | 53 |
| 10 | AI Ark | 46 |
B2B brands paying creators and independent voices to reach trusted audiences.
After falling in April, share climbed to a June peak, dipped in July, rebounded in August, then fell in September; L30 is down 6.7%. Demandbase’s May hiring and AirOps’ June creator panel track the climb, while Limelight’s September results show established brand-deal activity even as conversation cooled.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | ElevenLabs | 55 |
| 3 | HubSpot | 88 |
| 4 | Gamma | 44 |
| 5 | HeyReach | 53 |
| 6 | Lovable | 60 |
| 7 | Replit | 57 |
| 8 | Claude Code | 99 |
| 9 | FullEnrich | 44 |
| 10 | Granola | 52 |
How marketing teams use AI, where it helps and how it changes the job.
AI in marketing fell from March into May, then settled into a narrow June-to-September band rather than producing another breakout. The 16.5% L30 move points upward now, with Inflection positioned as infrastructure for marketing agents; earlier discussion focused on marketing engineers and deep generalists who can validate AI output.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Profound | 53 |
| 4 | Lovable | 60 |
| 5 | ElevenLabs | 55 |
| 6 | Midjourney | 36 |
| 7 | Salesforce | 94 |
| 8 |  Adobe Marketo | 25 |
| 9 | AirOps | 39 |
| 10 |  Aurasell | 20 |
Starting and running a business, including the economics and experience of the founder path.
Entrepreneurship discussion has moved unevenly downward since March, with a brief August lift that did not hold into September. No single event explains the 34.2% L30 decline; the pattern is scattered founder stories, from YouSpot’s solo-business CRM to Tally’s bootstrapped $6 million ARR milestone and Tenex’s rapid hiring.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Substack | 53 |
| 5 | 6sense | 41 |
| 6 |  Amp | 19 |
| 7 | Claude Code | 99 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Exa.ai | 46 |
| 10 |  Harmonic | 20 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing climbed from March through August, then held nearly flat in September. Devin Fusion’s hybrid harness, OpenRouter’s move to Stripe, and Harvey’s reported margin collapse gave the rise concrete product and economic anchors. The 31.9% L30 decline shows the sustained summer build has cooled recently.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 71 |
| 5 | Codex | 84 |
| 6 | LangChain | 47 |
| 7 | Baseten | 46 |
| 8 | Cline | 28 |
| 9 | HubSpot | 88 |
| 10 | Midjourney | 36 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth Marketing fell hard from March to April, then drifted lower through August before a modest September rebound. The L30 measure is down 11.9%, so that bounce has not held. The pattern reflects a broader reframing from channel optimization toward AI-assisted product work, GTM engineering, and higher experiment volume.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Ahrefs | 51 |
| 3 | Webflow | 48 |
| 4 | Claude Code | 99 |
| 5 | Optimizely | 31 |
| 6 | Profound | 53 |
| 7 | beehiiv | 51 |
| 8 | AirOps | 39 |
| 9 | Clay | 91 |
| 10 | Codex | 84 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing automation bottomed after a March-to-June decline, then rose gradually through September; the last 30 days added 33%, while October’s first 13 days are only early context. The recovery has a clear product arc: HubSpot launched Agent Hub and Agent Builder in July, tool-stack pressure stayed visible in September, and Jev brought concrete automated ad and search workflows into October.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 |  ActiveCampaign | 32 |
| 4 | Attio | 52 |
| 5 | Grok Bot | 71 |
| 6 | GrowthLoop | 29 |
| 7 | Twilio | 43 |
| 8 | Adobe Marketo | 25 |
| 9 | Apollo.io | 52 |
| 10 | Claude Code | 99 |
The software stack marketers use to plan, run, measure and improve their work.
Martech was nearly flat from March through May, stepped down in June and July, bounced in August, then softened again; the L30 is down 25.7%. No launch explains the curve. The sustained pattern is stack compression: concern about agent sprawl is pushing the conversation from adding tools toward architecture, governance, and fewer software layers.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | GrowthLoop | 29 |
| 2 | HubSpot | 88 |
| 3 | Cursor (Anysphere) | 78 |
| 4 |  Hootsuite | 22 |
| 5 | Salesforce | 94 |
| 6 | Salesloft | 41 |
| 7 | Twilio | 43 |
| 8 |  Zeta | 21 |
| 9 |  allGood | 19 |
| 10 | ActiveCampaign | 32 |
The point where a product solves a real need for a market that will buy it.
Product-market fit discussion peaked in April, declined into July, then held nearly flat across August and September. The last 30 days are up 20%, but no single launch explains the move; the conversation spans better measures of product love, new deep-tech funding assumptions, and ClickUp’s claim that AI shortens PMF refresh cycles.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | Granola | 52 |
| 4 | HeyReach | 53 |
| 5 | HubSpot | 88 |
| 6 | Lovable | 60 |
| 7 | Ahrefs | 51 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Customer.io | 39 |
| 10 |  Fireflies | 37 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Exec-led and employee-led social held remarkably steady from April through August, then lost ground in September. The L30 is still down 6%, so early October’s higher bar is context, not a reversal. The posts point to a durable playbook, with personal authority, funnel roles, and idea ownership replacing broad calls for consistency.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 91 |
| 3 | HubSpot | 88 |
| 4 | Grok Bot | 71 |
| 5 | HeyReach | 53 |
| 6 | Instantly | 63 |
| 7 | Lovable | 60 |
| 8 | RB2B | 47 |
| 9 | Apify | 52 |
| 10 | Customer.io | 39 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Headless software spiked in April around Salesforce’s Headless 360 launch, declined through July, then recovered across August and September. The L30 is flat, which makes the current plateau meaningful after a volatile year, though the L90 remains down 34.3%. Salesforce’s cross-platform architecture and internal GTM engines keep the API-first model concrete.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Apify | 52 |
| 6 | Firecrawl | 40 |
| 7 | ZoomInfo | 50 |
| 8 | Exa.ai | 46 |
| 9 | Lightfield | 26 |
| 10 | Clarify | 30 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent Skills peaked in May, then declined across the following full months, with the L30 measure down 22.7%. Neither Vercel’s open agent plugin standard nor practical Claude skills for advertising and OKR reviews reversed that slide. The pattern suggests strong utility inside specific workflows, but less broad conversation after the May burst.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Codex | 84 |
| 5 | Clay | 91 |
| 6 | Nooks | 48 |
| 7 | Optimizely | 31 |
| 8 | Customer.io | 39 |
| 9 |  Fathom | 32 |
| 10 | FullEnrich | 44 |
Scoring leads and accounts to decide who deserves attention first.
Lead scoring fell sharply from May through September, and remains down 45% over 90 days. The last 30 days are up 8%, but the evidence points to a changing method, not a clean comeback: teams are testing richer persona pipelines and real-time buyer interaction while questioning simple behavioral scores.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Clay | 91 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 63 |
| 6 | Prospeo | 52 |
| 7 | RB2B | 47 |
| 8 | Webflow | 48 |
| 9 | n8n | 59 |
| 10 | AI Ark | 46 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting rose steadily from March to a June high, then declined each month through September. June’s offer-design release matched the high by arguing that weak offers, not headlines, often cause conversion problems; later posts widened that critique to positioning, audience definition, and AI briefing. The L30 is still down 10.8%, so early October context does not establish a reversal.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 88 |
| 3 | Instantly | 63 |
| 4 | Clay | 91 |
| 5 | HeyReach | 53 |
| 6 | Midjourney | 36 |
| 7 | AI Ark | 46 |
| 8 | BetterContact | 42 |
| 9 | Codex | 84 |
| 10 | Findymail | 42 |
Systems where several agents divide a job, coordinate their work and combine the result.
Multi-agent systems rose into May, then lost share almost every month through September; no single post explains that long slide. Workato’s Airo expansion and Mercor’s five-hour, 100-plus-subagent diligence run gave the category concrete enterprise proof, and the L30 move has turned up 26.1% even though the 90-day trend remains down.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 71 |
| 5 | Salesforce | 94 |
| 6 | n8n | 59 |
| 7 | LangChain | 47 |
| 8 | Zapier | 53 |
| 9 | AI Ark | 46 |
| 10 | Clay | 91 |
Teams building internal software with AI instead of buying another SaaS product.
Discussion faded from its March and April levels, then held near 0.6% through August and September. The 34.9% L30 lift comes from a sharper argument, not one launch: RevOps teams are testing AI-built replacements, critics stress maintenance costs, and Replit shows non-engineers building tools directly. October’s bar remains early context.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Monaco | 25 |
| 6 | ZoomInfo | 50 |
| 7 |  Klaviyo | 40 |
| 8 | Lovable | 60 |
| 9 | Momentum | 25 |
| 10 | Qualified | 25 |
AI agents that discover, compare and buy products on a person's behalf.
Conversation eased from March through August, then strengthened in September as agentic commerce moved from premise to product distribution. The 50.5% L30 increase aligns with Shopify bringing Shop Pay checkout to Meta’s Muse, Klaviyo joining Muse, and Vercel putting agent-led product discovery and purchasing onstage.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 |  Browserbase | 34 |
| 2 | Salesforce | 94 |
| 3 | Vercel | 61 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Exa.ai | 46 |
| 6 | Claude Code | 99 |
| 7 | HubSpot | 88 |
| 8 | Lovable | 60 |
| 9 | Ahrefs | 51 |
| 10 | AirOps | 39 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
CLIs for GTM climbed unevenly into a July high after Clay launched its API, CLI, and agent plugin, then settled into a lower August-September plateau. That plateau still sat well above March, showing the interface shift had legs beyond launch week. The L30 is now down 23.6%, and October’s partial bar is only early context.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Salesforce | 94 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | HubSpot | 88 |
| 7 | ZoomInfo | 50 |
| 8 | AI Ark | 46 |
| 9 | Apify | 52 |
| 10 | Attio | 52 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing Operations has steadily lost share from March through September, and the L30 is down another 20.2%. Product launches did not reverse the slide: Conversion promised agent-built campaigns in May, while April and September posts framed the harder problem as agent sprawl and outdated marketing automation.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Salesloft | 41 |
| 4 | allGood | 19 |
| 5 | Clay | 91 |
| 6 | Docket | 31 |
| 7 | Grok Bot | 71 |
| 8 | MoEngage | 22 |
| 9 | n8n | 59 |
| 10 | 6sense | 41 |
A go-to-market operating model where agents execute work across the revenue motion.
Conversation was uneven through spring and summer, then rose in August and held near that level in September as builders framed agents as GTM infrastructure, expanded SDR coverage, and focused on data readiness. The 90-day view is up 31.4%, but the latest 30 days are down 3%, so partial October does not yet confirm another step up.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 91 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 94 |
| 5 | Codex | 84 |
| 6 | 6sense | 41 |
| 7 | Attio | 52 |
| 8 | HubSpot | 88 |
| 9 | ZoomInfo | 50 |
| 10 | 1mind | 37 |
AI agents that create, launch, buy and optimize advertising.
AI-driven advertising rose steadily from May through August and stayed near that level in September, which points to category formation rather than a single spike. The last 30 days are up 38.4% as ChatGPT Ads scaled past a $1 billion annualized run rate and new formats emerged for both conversational discovery and AI crawlers.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Granola | 52 |
| 3 | Lovable | 60 |
| 4 | Salesforce | 94 |
| 5 | Clay | 91 |
| 6 | Grok Bot | 71 |
| 7 | Similarweb | 33 |
| 8 | Codex | 84 |
| 9 |  Criteo | 21 |
| 10 | Cursor (Anysphere) | 78 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
Conversation peaked in May, then lost ground through July and stayed near that lower level into September; the L30 move remains down 3.8%. The earlier lift came from concrete pricing shifts across Salesforce, ServiceNow, Clay, HubSpot, Anthropic, SAP, and monday.com, while Moltsets now supplies a sharp unlimited-price counterpoint.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Replit | 57 |
| 4 | Lovable | 60 |
| 5 | Clay | 91 |
| 6 |  Metronome | 27 |
| 7 | Nooks | 48 |
| 8 | Supabase | 48 |
| 9 | Vercel | 61 |
| 10 | Cursor (Anysphere) | 78 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
The conversation peaked in April around moving from individual tools to AI-centered operating processes, then shifted toward pressure for leaner, automation-heavy teams. Share fell through July, briefly rebounded in August, and resumed declining in September; the 31% L30 drop comes as recent discussion turns to hiring and developing people while the technology changes weekly.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Granola | 52 |
| 3 | beehiiv | 51 |
| 4 | Claude Code | 99 |
| 5 | Clay | 91 |
| 6 | ElevenLabs | 55 |
| 7 | HubSpot | 88 |
| 8 | Lovable | 60 |
| 9 | Salesforce | 94 |
| 10 | Vercel | 61 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Partner conversation climbed from July into August, then held almost perfectly flat in September, a meaningful plateau after the step-up. The L30 is down 20.1%, but the 90-day view remains 43.2% higher, supported by concrete ecosystem mechanics: co-sell discipline, partner-led demand generation, certification, directories, support, and revenue share.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | HubSpot | 88 |
| 3 | Salesforce | 94 |
| 4 | Lovable | 60 |
| 5 | Replit | 57 |
| 6 | Instantly | 63 |
| 7 | AI Ark | 46 |
| 8 | Apollo.io | 52 |
| 9 | Aurasell | 20 |
| 10 | Canva | 49 |
Multi-step work planned and executed by agents instead of fixed automation rules.
Conversation share fell from May through August, then rebounded in September; October is still partial and should not be read as a completed month. The L30 measure is up 58.3%, alongside fresh discussion of Clay’s planning agent, Aurasell’s 67-agent sales model, and Macroscope’s customer-lifecycle workflows, while L90 remains down 12.1%.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Grok Bot | 71 |
| 3 | Salesforce | 94 |
| 4 | Clay | 91 |
| 5 | Codex | 84 |
| 6 | Gong | 64 |
| 7 | 6sense | 41 |
| 8 | Apollo.io | 52 |
| 9 | Claude Code | 99 |
| 10 |  Demandbase | 31 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Forward deployed engineering rose quickly from March to May, then declined month by month through September. The evidence points to a role-definition cycle: Sierra revisited the Palantir origin story, while September posts stressed product feedback and questioned whether today’s boom qualifies as true FDE work; the L30 remains down 23.6%, so October’s partial bar is not a recovery.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Braze | 26 |
| 2 | Nooks | 48 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Codex | 84 |
| 6 | Gong | 64 |
| 7 | Lovable | 60 |
| 8 | Attio | 52 |
| 9 | Clay | 91 |
| 10 | Cursor (Anysphere) | 78 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales Ops climbed from March to a May high, then lost ground through summer and dropped sharply in September. The L30 measure is down 31.7%, while the first eight October days offer only early context. The conversation moved from Rox’s revenue automation launch toward sharper debates about rep and SDR compensation design.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 91 |
| 4 | HubSpot | 88 |
| 5 | Vercel | 61 |
| 6 | n8n | 59 |
| 7 | Airtable | 49 |
| 8 |  CaptivateIQ | 17 |
| 9 | Clari | 33 |
| 10 | Codex | 84 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
Event conversation has stayed volatile: a March high gave way to an April trough, followed by rebounds in May and July before another September dip. The L30 is up 5% and the L90 up 35%. Community meetups and hackathons supplied momentum, while October’s early discussion centers on proving event-influenced revenue.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Lovable | 60 |
| 2 | Salesforce | 94 |
| 3 | Clay | 91 |
| 4 | Substack | 53 |
| 5 | Ahrefs | 51 |
| 6 | Apify | 52 |
| 7 | Customer.io | 39 |
| 8 | Gong | 64 |
| 9 | Profound | 53 |
| 10 | 6sense | 41 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Conversation share fell 69% from March through September as SDR hiring contracted and the traditional SDR-to-AE handoff came under pressure. The last 30 days edged up 0.8%, alongside fresh signs that SDR demand is returning, though the same promotion and retention problems remain.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 | Claude Code | 99 |
| 3 | Clay | 91 |
| 4 | Nooks | 48 |
| 5 | Outreach | 46 |
| 6 | Salesforce | 94 |
| 7 | FullEnrich | 44 |
| 8 | HubSpot | 88 |
| 9 |  Unify | 32 |
| 10 | Apollo.io | 52 |
The work of earning awareness, trust and preference for a company over time.
Brand Building held near 1% from March through June, slipped in July, recovered in August, then fell hard in September. The L30 measure is down another 46.4%; the first eight October days do not establish a recovery. The posts point to a persistent budget problem: brand creates value that click-based attribution often misses.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 88 |
| 4 | Nooks | 48 |
| 5 | Optimizely | 31 |
| 6 | Salesforce | 94 |
| 7 | Semrush | 48 |
| 8 | 6sense | 41 |
| 9 | Braze | 26 |
| 10 |  Buffer | 24 |
Tracing and monitoring what a model or agent did during a production run.
Observability stayed small but rose consistently from July through September, and L30 is up 37.1%. The rise is sustained by an enterprise-stack pattern: Cloudflare combined routing, billing, and monitoring, while CrewAI’s bank story showed buyers resisting separate contracts for every layer. October’s partial bar does not establish a downturn.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Clay | 91 |
| 5 |  Kiro | 23 |
| 6 | Salesforce | 94 |
| 7 | Vercel | 61 |
| 8 |  Attention | 29 |
| 9 | Browserbase | 34 |
| 10 | Clarify | 30 |
Approval and review steps that keep a person involved in an agent's work.
The curve has stayed choppy, with a May high, a June and July retreat, and a smaller August rebound before September weakened again. The 26.8% L30 decline suggests no single oversight framework held attention, despite concrete discussion of autonomy levels, review economics, permissions, approvals, and audit trails.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Instantly | 63 |
| 3 | Attio | 52 |
| 4 | Clay | 91 |
| 5 | HubSpot | 88 |
| 6 | Outreach | 46 |
| 7 | Salesforce | 94 |
| 8 | AI Ark | 46 |
| 9 | Apollo.io | 52 |
| 10 | Codex | 84 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Content production at scale rose to a May high, then declined across June through September. The last 30 days are down another 5%, close to a plateau; the discussion has moved from sheer output toward control, with teams focused on optimization systems, video coherence, and the search penalties attached to AI spam.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | Apify | 52 |
| 3 | Claude Code | 99 |
| 4 | Lovable | 60 |
| 5 | AirOps | 39 |
| 6 | Exa.ai | 46 |
| 7 | Substack | 53 |
| 8 | n8n | 59 |
| 9 | Airtable | 49 |
| 10 | Apollo.io | 52 |
Websites and docs structured so AI crawlers and agents can read and use them.
Conversation peaked in April, softened through June, then settled into a lower band from July through September. The evidence shows an unresolved standards debate rather than one decisive event: Google reportedly dismissed AI-specific files, Scott Brinker broadened the case to agent-facing web services, and Semrush kept llms.txt under review; the L30 is down another 16.2%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | Peec AI | 29 |
| 3 | Semrush | 48 |
| 4 | Claude Code | 99 |
| 5 | Codex | 84 |
| 6 | Gamma | 44 |
| 7 | HubSpot | 88 |
| 8 | Profound | 53 |
| 9 | Webflow | 48 |
| 10 | AirOps | 39 |
A shared revenue knowledge layer that people and agents can query and update.
Conversation share fell through May, jumped in June, and stayed elevated through September as posts moved from a shared GTM brain feeding agents to a concrete CRM context graph. October is partial, while the L30 rose 2.4%, alongside continued discussion of trusted revenue context and connected workflows.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Apify | 52 |
| 4 | Grok Bot | 71 |
| 5 | HubSpot | 88 |
| 6 | Instantly | 63 |
| 7 | Octave | 31 |
| 8 | ZoomInfo | 50 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Fireflies | 37 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-serve fell hard from March through May, then settled into a narrow band through August before weakening again; the latest 30 days are down 17.7%. The conversation spans both sides of the model: Metronome opened self-serve after strong demand, while Airtable became a warning about enterprise priorities displacing product-led growth.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Replit | 57 |
| 3 | Salesforce | 94 |
| 4 | Lovable | 60 |
| 5 | Clay | 91 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Vercel | 61 |
| 8 | Ahrefs | 51 |
| 9 | Apollo.io | 52 |
| 10 |  Base44 | 20 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
Conversation moved unevenly through spring, then softened after July, with the L30 down 20.6%. Viktor’s $20 million run rate and Microsoft Teams expansion, Vista’s digital-worker thesis, and an open-source company brain show steady product activity, but no single event created durable momentum.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Viktor | 33 |
| 2 | Clay | 91 |
| 3 | HubSpot | 88 |
| 4 | Attio | 52 |
| 5 | Granola | 52 |
| 6 | Grok Bot | 71 |
| 7 | Salesforce | 94 |
| 8 | Ahrefs | 51 |
| 9 | Firecrawl | 40 |
| 10 | Gong | 64 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound systems rose sharply into May, then declined across every completed month through September; the L30 is down 45.6%. Earlier attention centered on complete automated engines, including GTMskills and Rox’s account of xbow. The newest evidence pushes the other way: a deliberately manual café-sales process rejects complex tables, signals, and automated sequences.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Attio | 52 |
| 3 | HubSpot | 88 |
| 4 | TitanX | 33 |
| 5 | 6sense | 41 |
| 6 | AI Ark | 46 |
| 7 | AirOps | 39 |
| 8 |  Amplemarket | 20 |
| 9 | Apify | 52 |
| 10 |  Calendly | 39 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI security held a narrow plateau from March through August, then dropped sharply in September. No single event explains the decline: research kept surfacing concrete risks, from Wiz’s GhostApproval flaw to Cohere’s data-leakage findings and Forrester’s focus on agent intent, but the 17.5% L30 decline shows the conversation is still thinning.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Midjourney | 36 |
| 3 | Claude Code | 99 |
| 4 | Codex | 84 |
| 5 | Grok Bot | 71 |
| 6 | Salesforce | 94 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | ElevenLabs | 55 |
| 9 | Clarify | 30 |
| 10 |  E2B | 23 |
Deciding what to build, why it matters and which product bets come first.
Product strategy has moved in waves, with highs in March and May followed by a lower, unusually steady band from July through September. The L30 is up 8.2%, but no single event explains the curve. The evidence spans roadmap pressure from AI, the upstream role of product marketing, and Automation Anywhere’s agreement to acquire Boost.ai.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Clay | 91 |
| 4 | Claude Code | 99 |
| 5 | Intercom | 44 |
| 6 | OpenRouter | 53 |
| 7 | Substack | 53 |
| 8 | Supabase | 48 |
| 9 | Vercel | 61 |
| 10 | AirOps | 39 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales tech stayed relatively steady through August, then broke lower in September; the 19% L30 decline shows that weakness remains current. The evidence reflects scattered company and ecosystem stories rather than one catalyst, and Zoom’s early October expansion into outbound sequencing and forecasting has not yet changed the broader direction.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 | Salesforce | 94 |
| 3 | Clay | 91 |
| 4 | Outreach | 46 |
| 5 | HubSpot | 88 |
| 6 | Nooks | 48 |
| 7 | Clarify | 30 |
| 8 | Claude Code | 99 |
| 9 | Common Room | 38 |
| 10 | Cursor (Anysphere) | 78 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium has been volatile: it dropped to a July low, rebounded across August and September, and is down 23% over the latest 30 days. The rebound had several concrete proofs behind it, including ChatGPT funding free access with ads and PostHog putting its 97% free-customer share directly beside the signup call to action.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Lovable | 60 |
| 2 | Replit | 57 |
| 3 | Salesforce | 94 |
| 4 | Canva | 49 |
| 5 | Clay | 91 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | HubSpot | 88 |
| 9 |  Manus | 32 |
| 10 | Attio | 52 |
The runtime around an agent that provides tools, state, controls and stopping rules.
Agent harnesses moved in waves, with stronger months in April, June, and August rather than one sustained climb. That cadence matches a series of concrete proofs: Anthropic’s multi-agent engineering work, DeepSeek’s open-source developer preview, and a September explainer that defined the runtime category. The 26.2% L30 increase shows current momentum despite limited early-October data.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Salesforce | 94 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 91 |
| 6 | AI Ark | 46 |
| 7 |  AiSDR | 19 |
| 8 | BuiltWith | 33 |
| 9 | Cline | 28 |
| 10 | Common Room | 38 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
Conversation climbed into a May peak as teams moved from mapping AI-first stacks to showing practical workflow-led GTM models. It dropped sharply in June, rebounded in July, then eased through August and September; the latest 30 days are down 13.9%, even as Zendesk’s dedicated GTM AI role shows active organizational commitment.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 91 |
| 3 | FullEnrich | 44 |
| 4 | Grok Bot | 71 |
| 5 | HubSpot | 88 |
| 6 | Profound | 53 |
| 7 | Substack | 53 |
| 8 | Vector | 37 |
| 9 | 1mind | 37 |
| 10 | 6sense | 41 |
Writing and structuring the instructions a model follows.
Prompt engineering declined from March through May, bounced in June, then lost more than half its share by September; the L30 measure is down another 26.0%. The evidence points to a vocabulary and architecture shift: teams want agents that tolerate weak prompts, while context, tools, and progressively loaded skills carry more of the work.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Clay | 91 |
| 4 | Codex | 84 |
| 5 | HubSpot | 88 |
| 6 | Attio | 52 |
| 7 | Zapier | 53 |
| 8 | Breeze | 24 |
| 9 | Granola | 52 |
| 10 | OpenClaw | 51 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
Conversation share peaked in May, then fell sharply through August before a small September rebound; the latest 30 days are down 2.8%. September posts documented point tools being dropped and Outreach deployments being replaced, while Apollo’s October launch shows broader platforms still pushing consolidation despite the softer curve.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Clay | 91 |
| 4 | Attio | 52 |
| 5 | Clarify | 30 |
| 6 | Claude Code | 99 |
| 7 | Common Room | 38 |
| 8 | Codex | 84 |
| 9 | Gong | 64 |
| 10 | Nooks | 48 |
Using AI to tailor outreach and marketing to each person at scale.
AI personalization peaked around April and May, then declined through September; the L30 is down 38.9%. The high point paired strong scale claims with restraint: Clay produced 1,800 emails in seven minutes, while LaunchDarkly narrowed roughly 1,000 accounts to 50. Iterable’s later customer result shows focused personalization still works, but not enough to reverse the broader fade.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 91 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Klaviyo | 40 |
| 7 | Outreach | 46 |
| 8 | AI Ark | 46 |
| 9 | Braze | 26 |
| 10 | Findymail | 42 |
Founders running early sales themselves before handing the motion to a sales team.
An April founder story contrasted closing every early deal with $7 million ARR today. Conversation collapsed in May, recovered in June, and peaked in July alongside a free Founding Sales book offer, then eased through September; the latest 30 days are down 16.7%, while September discussion says AI can extend the founder-led phase.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | HubSpot | 88 |
| 3 | 6sense | 41 |
| 4 | Attio | 52 |
| 5 | Clarify | 30 |
| 6 | Common Room | 38 |
| 7 | Gong | 64 |
| 8 | Granola | 52 |
| 9 |  HockeyStack | 29 |
| 10 | Instantly | 63 |
Time-limited access that lets a buyer test a product before paying.
Free-trial conversation fell sharply after March, recovered gradually from May through July, then dipped again in August. The L30 is up 22.2%, but the evidence is a mix of operating friction, abuse, and poor upselling rather than one launch: incentives delayed follow-up, Stripe flagged rising abuse, and premature pitches hurt trust.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 88 |
| 3 | Ahrefs | 51 |
| 4 | Clay | 91 |
| 5 | Gong | 64 |
| 6 | Lovable | 60 |
| 7 | AthenaHQ | 20 |
| 8 | Attio | 52 |
| 9 | Calendly | 39 |
| 10 | Clari | 33 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
The topic spiked in April, then declined steadily through September as the broad sameness critique lost momentum. The L30 move is now up 45.4%, supported by sharper evidence: major consultancies use similar AI playbooks, and a 445-homepage study found 57% average messaging overlap.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Customer.io | 39 |
| 5 |  Grammarly | 29 |
| 6 | Optimizely | 31 |
| 7 | Sequel | 31 |
| 8 | Substack | 53 |
| 9 | Vector | 37 |
| 10 | Webflow | 48 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
Lifecycle marketing rose into a May peak, fell through August, then stabilized in September; the L30 move is up 70.8%. The renewed conversation is practical: repeated onboarding optimization, AI-assisted loyalty and customer journeys, and frustration with one-size-fits-all nurture programs.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Claude Code | 99 |
| 3 | beehiiv | 51 |
| 4 | Apollo.io | 52 |
| 5 | Customer.io | 39 |
| 6 |  Explorium | 31 |
| 7 | Gong | 64 |
| 8 | Grok Bot | 71 |
| 9 | GrowthLoop | 29 |
| 10 | Instantly | 63 |
How AI changes headcount, entry-level work and the jobs people still need to do.
AI-and-jobs discussion was highest in March, bounced in May, then faded through September; the L30 remains nearly flat to slightly down at -1.7%. No single event explains the curve. The durable pattern is tension between lean-team claims and contrary hiring evidence, including Microsoft marketing openings and an OpenAI SDR role that preserves human relationship work.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 71 |
| 2 | Clay | 91 |
| 3 | Lovable | 60 |
| 4 | Ahrefs | 51 |
| 5 | Attention | 29 |
| 6 | Clarify | 30 |
| 7 | Claude Code | 99 |
| 8 | Clearskies | 22 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | HubSpot | 88 |
How sales teams use AI and how it changes the work of selling.
AI in Sales share was highest in March, rebounded in May, held roughly flat in June and July, then fell sharply through August and September. Late September conversation paired Ami and Salesloft product announcements with Josh Braun’s build-it-yourself critique, while the L30 move remains slightly negative.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clarify | 30 |
| 2 | Claude Code | 99 |
| 3 | Clay | 91 |
| 4 | Gong | 64 |
| 5 | Salesforce | 94 |
| 6 | Attention | 29 |
| 7 |  CallRail | 22 |
| 8 | Clearskies | 22 |
| 9 | Cursor (Anysphere) | 78 |
| 10 |  GitHub Copilot | 36 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise marketing rose from May through an August plateau, then fell in September; the last 30 days are down 21.9%. No single launch drove the rise. The posts show a broader operating shift toward AI-specific roles, decentralized building with centralized governance, and messaging focused on production readiness, security and compliance.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 91 |
| 3 | HubSpot | 88 |
| 4 | Aurasell | 20 |
| 5 | Braze | 26 |
| 6 | Claude Code | 99 |
| 7 | Codex | 84 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Grok Bot | 71 |
| 10 | Klaviyo | 40 |
The strategy of naming, defining and leading a new market.
Category creation stayed nearly flat from April through June, softened in July, briefly recovered in August, then dropped sharply in September. The L30 is down another 51%, despite a slightly higher early October bar. The evidence forms a critique cycle: focus on the job, compete inside known categories, and question whether AI weakened category gatekeepers.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 91 |
| 3 | HubSpot | 88 |
| 4 | Granola | 52 |
| 5 | Nooks | 48 |
| 6 | Primer | 28 |
| 7 | Adobe Marketo | 25 |
| 8 | Ahrefs | 51 |
| 9 | Attio | 52 |
| 10 | Braze | 26 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory peaked in April, dropped sharply into July, and has stayed near that lower floor; the L30 move is only up 1.8%, not a clear recovery. April’s concentration came from a specific debate over long-term fractional CMOs, while September’s fractional CRO case reinforced the model without restoring the earlier conversation level.
Posts to understand this · as of Oct 6
Rule-based software that moves business work through predefined steps and systems.
Workflow automation peaked in April and mostly declined afterward, with a 49.2% L30 drop confirming weaker current attention. No single event explains the slide; the posts show the framing broadening from Zapier-connected workflows and Salesforce no-code tools toward a larger agent stack that handles research, prioritization, follow-ups, and coaching.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 91 |
| 2 | Zapier | 53 |
| 3 | AI Ark | 46 |
| 4 | Ahrefs | 51 |
| 5 | AirOps | 39 |
| 6 | Airtable | 49 |
| 7 | Apollo.io | 52 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | ElevenLabs | 55 |
| 10 | Exa.ai | 46 |
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
Open-source AI spiked in July, alongside reports that companies were adopting open models beside closed ones, then lost ground through September. Bolt Forge added a concrete usage and training program, while debate around Nvidia, OpenAI, and Anthropic kept the category contentious, but the L30 is still down 19%.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 |  Groq | 25 |
| 3 | Substack | 53 |
| 4 | Baseten | 46 |
| 5 |  Crunchbase | 34 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | ElevenLabs | 55 |
| 8 | Grok Bot | 71 |
| 9 | Harmonic | 20 |
| 10 | HubSpot | 88 |
Advantages that grow stronger as more people, data or participants join a product.
Network effects declined every month from March through September, and the L30 measure is down 58.6%. No single launch explains the slide. Recent posts recast the compounding advantage in more specific terms: Salesforce points to governed customer data, Clay to UGC distribution loops, and Sierra to accumulated customer conversations.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | ElevenLabs | 55 |
| 4 | Granola | 52 |
| 5 | Grok Bot | 71 |
| 6 | Vercel | 61 |
| 7 | beehiiv | 51 |
| 8 | Ahrefs | 51 |
| 9 | Clarify | 30 |
| 10 | Clay | 91 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
Conversation share climbed from March to a May peak as HubSpot put per-result agent pricing into market. It then fell through August despite Salesforce investing in flexible billing infrastructure, before improving in September; the latest 30 days are up 40%, with October discussion challenging seat pricing as a measure of delivered value.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 91 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | HubSpot | 88 |
| 5 | Intercom | 44 |
| 6 | Lovable | 60 |
| 7 | Metronome | 27 |
| 8 | Vercel | 61 |
| 9 | 1mind | 37 |
| 10 | 6sense | 41 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
Conversation spiked sharply in August as new transparency rules took effect and major platforms detailed compliance. Anthropic introduced Claude text watermarking, Synthesia automated machine-readable marks, and Google’s large watermarking footprint broadened the story. Share then fell hard, with the L30 down 73.6%, though the L90 remains well above the earlier baseline.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 71 |
| 4 | HeyGen | 33 |
| 5 | Granola | 52 |
| 6 | Runway | 36 |
| 7 | Vercel | 61 |
| 8 | Docket | 31 |
| 9 |  Ghost | 18 |
| 10 | Higgsfield | 38 |
AI-generated creators, avatars and user-style content used in marketing.
Conversation spiked in April, cooled through summer, then recovered in September; the 38% L30 rise shows that momentum is continuing without treating partial October as complete. Recent discussion centers on filming barriers, marketers testing their own avatars, and narration tools that remove repeated shoots when demo copy changes.
Posts to understand this · as of Oct 11
AI-native firms that sell finished work instead of software, delivered by agents and a small human team.
Services-as-Software fell sharply after its spring concentration, from 0.345% in June to 0.155% in August, before a small September lift. The L30 is up 18.8%, but the L90 remains down 43.1%. Spring had concrete fuel from Emergence’s category blueprint and Daydream’s $15M round; September’s Sequoia thesis brought the model back into view.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Crunchbase | 34 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
Conversation held near a steady plateau from June through August, then dropped in September; the L30 is down another 71.9%. No single event explains the decline. Product distribution continues through Anthropic’s marketplace, Zapier’s 9,000-plus-tool Claude connection, and fal’s Claude and Codex integrations, but launches are no longer sustaining the earlier discussion level.
Posts to understand this · as of Oct 12
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | HeyGen | 33 |
| 4 |  Lambda | 25 |
| 5 | Lovable | 60 |
| 6 | Salesforce | 94 |
| 7 | Zapier | 53 |
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent Loops surged in June, stayed near that high in July, then declined through September; L30 is down 37.4%. Joe Rhew’s June prediction helped define the concept, while Palantir’s Agent Engine and SDK gave July a concrete launch; Atlassian’s September focus on governed loops shows the idea persisting in a narrower form.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Attio | 52 |
| 2 | Claude Code | 99 |
| 3 | Clay | 91 |
| 4 |  Deepline | 31 |
| 5 | HubSpot | 88 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | LangChain | 47 |
| 9 | OpenClaw | 51 |
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing emerged in April, built through a July high, then fell sharply across August and September. The curve tracks a clear reframing from consumption to value: Sierra argued for outcomes-based pricing, Databricks demonstrated budget controls and efficient routing, and October commentary says corporate buyers now question token bills; despite that fresh discussion, the L30 remains down 17.8%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | Clay | 91 |
| 5 | Codex | 84 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Midjourney | 36 |
| 8 | Profound | 53 |
| 9 |  Retool | 27 |
| 10 |  Writer | 28 |
Interfaces that let agents understand and operate software built for human users.
Agent interfaces remain small and volatile: a May spike collapsed in June, rebounded in July, then eased through September. The last 30 days are up 13%, supported by a pattern rather than one event as Hightouch, Salesforce, and major GTM platforms build connectors, experience layers, CLIs, and MCP access for agents.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Browserbase | 34 |
| 3 | Claude Code | 99 |
| 4 | Clay | 91 |
| 5 | Exa.ai | 46 |
| 6 | HubSpot | 88 |
| 7 | Peec AI | 29 |
| 8 | Twilio | 43 |
| 9 | Vercel | 61 |
Pushback against AI from customers, workers and the public, and brands repositioning as pro-human.
The curve is choppy, with a May spike around direct attacks on the backlash and an August rebound as critics highlighted an AI sales company’s return to human labor. September remained active as anti-AI graffiti surfaced in San Francisco, but the conversation has fallen 37.6% over the last 30 days.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Bland | 19 |
| 3 | Browserbase | 34 |
| 4 | ElevenLabs | 55 |
| 5 | Granola | 52 |
| 6 | Grok Bot | 71 |
| 7 |  Gumloop | 25 |
| 8 | HubSpot | 88 |
| 9 | Lovable | 60 |
| 10 | Replit | 57 |
The online channel mix used to reach, convert and retain customers.
Conversation climbed into June, then fell through September. Around that turn, marketers argued that brand mattered more than adopting each new tool, then said zero-click behavior was weakening legacy digital work; by September, the focus had shifted to AI-agent recommendations, while the L30 measure shows attention remains down 27.7%.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | AI Ark | 46 |
| 2 | Apollo.io | 52 |
| 3 |  Chili Piper | 35 |
| 4 | Clay | 91 |
| 5 |  Default | 27 |
| 6 |  Freckle.io | 34 |
| 7 | HeyReach | 53 |
| 8 | HubSpot | 88 |
| 9 | Instantly | 63 |
| 10 | Lovable | 60 |
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
Autonomous Business discussion declined from March to an August low, rebounded in September, and is down 14.8% over the last 30 days. The September lift came with concrete efficiency claims from RB2B and Swan AI, but it did not restore earlier attention. The recurring hook is revenue per employee, anchored by Polsia’s one-employee operation.
Posts to understand this · as of Oct 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Lovable | 60 |
| 2 | Vercel | 61 |
| 3 | Claude Code | 99 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | ElevenLabs | 55 |
| 6 | Gamma | 44 |
| 7 | Grok Bot | 71 |
| 8 |  Lusha | 29 |
| 9 |  Netlify | 28 |
| 10 | OpenRouter | 53 |
The argument over requiring a form before someone can access useful content.
The gated-content debate has contracted sharply since March, despite a May rebound around a more nuanced rule: ungate the argument, gate the utility. Share then declined through September as later posts pushed the harder position that forms create false leads and buyer friction. The L30 move is slightly positive, suggesting stabilization rather than a clear comeback.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | AI Ark | 46 |
| 3 | ActiveCampaign | 32 |
| 4 | Ahrefs | 51 |
| 5 | Apify | 52 |
| 6 | Attio | 52 |
| 7 | BuiltWith | 33 |
| 8 | Chili Piper | 35 |
| 9 | Clay | 91 |
| 10 |  Crossbeam | 26 |
Brands use human authorship and craft as a reason to trust or value their work.
The curve has swung month to month, with no single event behind it. Dave Gerhardt framed human-made work as a premium in May, while GTM Skills and Alex Fine turned that claim into concrete offers around human-crafted expertise and writing. August strengthened and September eased; the L30 is down 18.3%, though the L90 remains up 46.9%.
Posts to understand this · as of Oct 11
| Brand | GTM Index | |
|---|---|---|
| 1 | Attention | 29 |
| 2 | Clarify | 30 |
| 3 | Clay | 91 |
| 4 | Clearskies | 22 |
| 5 | Nooks | 48 |
| 6 | Rox | 31 |
| 7 | Sumble | 32 |
| 8 | Claude Code | 99 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | HubSpot | 88 |
Software designed for agents to operate as the primary user.
Conversation emerged in June, rose through August, dipped in September, then accelerated 94% over the last 30 days. No single event drove it: Ploy opened sites to agents, Lorikeet launched agent-traffic detection, and Amazon and Cloudflare restrictions made the new tension concrete as agent traffic grew.
Posts to understand this · as of Oct 10
| Brand | GTM Index | |
|---|---|---|
| 1 | Vercel | 61 |
| 2 | Ahrefs | 51 |
| 3 | Breeze | 24 |
| 4 | Clay | 91 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Gamma | 44 |
| 7 | Grok Bot | 71 |
| 8 | HubSpot | 88 |
| 9 | Intercom | 44 |
| 10 | Lovable | 60 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
Trust-Based Marketing remains small and volatile: it recovered through July, dropped sharply in August, then partly returned in September. G2’s public Trust & Safety Index gave that rebound a concrete proof point, while the broader posts favor coherence and repeated credibility over content volume. The L30 move is positive, though the 90-day direction remains down.
Posts to understand this · as of Oct 11
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
Conversation jumped in July as Substack’s Pangram-backed validation feature drew scrutiny over false positives. It stayed elevated in August as people debated whether AI writing can be reliably spotted and pushed back on stylistic signals such as em dashes. After falling sharply in September, share is down 76% over the last 30 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 71 |
| 4 | Replit | 57 |
| 5 | Substack | 53 |
Using product activity to identify, time and support sales opportunities.
Product-Led Sales remains a tiny, intermittent conversation, with zero-share months punctuated by small bursts in March, June, August, and September. Its 180% L30 rise comes from that very low base, not a broad breakout; the first eight October days add only early context. Posts frame the topic through HubSpot infrastructure and consolidation after Pocus joined Apollo.
Posts to understand this · as of Oct 8
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 88 |
How model costs, services and agent work put pressure on software gross margins.
This is a sparse conversation, with a brief April high of 0.031% and zero-share months in May and July. The current L30 move is down 60%, and the evidence remains split between lower AI gross margins and a services model where smaller engagements can unlock a larger market.
Posts to understand this · as of Oct 9
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Share fell steadily from 11.5% in March to 4.3% in September, with the L30 down another 16.3%. The selected posts span an April model integration, July terminal frustration, and an October outbound workflow, showing that practical use continues even as the conversation contracts.
Posts to understand this · as of Oct 10
Cursor is an AI code editor with agents that write, edit and review code.
Cursor declined from March through July, then spiked in August when its SpaceX acquisition closed and the product joined the SpaceXAI portfolio. That deal-driven attention faded sharply in September, and the 44.9% L30 decline shows the slide continuing. A reported Nvidia usage signal did not sustain the acquisition bump; October remains incomplete.
Posts to understand this · as of Oct 10
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay climbed to a May high, then lost share through the summer and remained lower in September; the last 30 days are down 11.2%. May’s $770,000 pipeline case supplied a sharp proof point, but later conversation split between ecosystem training and Ocean.io’s claims of replacing Clay in enterprise deals, a pattern consistent with a maturing, contested category.
Posts to understand this · as of Oct 8
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n’s spring lift maps to two concrete distribution moves: Gamma’s native integration in April and the multi-year SAP partnership announced in May, which put n8n inside Joule Studio. Share topped out in June, then declined through September; the 37.2% L30 drop says the event-led attention has continued to cool.
Posts to understand this · as of Oct 11
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable’s March peak coincided with its free global SheBuilds day, while a parent’s account showed the event turning a first-time builder into an app creator. Share then fell through July and stabilized around 1% in August and September, when Slack included Lovable among its agent partners, but the latest L30 measure is down 23.2%.
Posts to understand this · as of Oct 11
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit conversation reached its high point in May, fell sharply in June, then settled into a narrower band through September. The L30 is down 11.9%, so current direction remains soft. GPT-5.6 Luna powering Free Mode and Apollo joining Replit’s Growth Kit supplied fresh product news, while the SaaStr database incident kept safety concerns in view.
Posts to understand this · as of Oct 12
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
OpenClaw started from an elevated March base after its creator joined OpenAI, then declined steadily through September; the L90 is down 49.8% and the L30 is down 9.1%. Later discussion shifted from OpenClaw itself to the broader harness model, while Grok bot drew attention as an easier, more reliable alternative.
Posts to understand this · as of Oct 12
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
Codex jumped in May, then held close to 3% share from June through September. That plateau is meaningful: the L90 is effectively flat at 0.2%, while Exa and Clay integrations keep extending Codex beyond coding into research, enrichment, prospecting, and GTM workflow execution.
Posts to understand this
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Hermes Agent appeared sharply in April and remained elevated in May as image-generation access expanded across agent workflows. Attention then declined month by month through September; free Perplexity search added a useful capability, but it has not changed the current direction, with the L30 down 11.6%.
Posts to understand this · as of Oct 10
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce’s share slid from April through July, edged up in August, then jumped in September. Informatica’s announcement coincided with that jump, while recent hands-on use of Salesforce inside Claude better matches the 9.2% L30 rise; June’s Fin agreement belongs to the earlier backdrop, not the current move.
Posts to understand this · as of Oct 12
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
Conversation peaked in May alongside HubSpot’s launch of per-outcome pricing for its prospecting and support agents, then fell through August. The curve began recovering in September as the Trigify team joined HubSpot, extending an acquisition thread that included Warmly; the latest L30 reading is up 18.9%, while the 90-day view remains down 26.8%.
Posts to understand this · as of Oct 12
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Share peaked in April, fell through August, then edged up in September; the selected evidence does not establish what drove the April high. September conversation paired Gong’s call benchmark with direct competitor positioning, while fresh competitor comparisons align with the 7.7% L30 rise.
Posts to understand this · as of Oct 10
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
Vercel’s share moved unevenly, with an August spike alongside its inclusion in Slack Code’s agent launch and hands-on interest in Vercel Workflows. September gave that gain back, and the 20.2% L30 decline points to continued softness; October’s partial bar is only early context.
Posts to understand this · as of Oct 10
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Conversation share fell steadily from March through September after early Cowork discussion centered on ambitious hands-on builds, from an automated customer-lookalike agent to a live, multi-asset content workflow. The L30 increase points to a recent pickup, with Docusign’s September launch placing Cowork inside concrete small-business contract work.
Posts to understand this · as of Oct 12
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly rose from March to a June high, then settled into a lower but stable band from July through September; the L30 is down 15.1%. That plateau still reflects operational use, not passing mentions: teams run hundreds of mailboxes, centralize replies in Slack and Attio, and recruit specialists for warming, testing, and deliverability.
Posts to understand this · as of Oct 11
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter rose from a small March base, then spiked in August when Stripe agreed to acquire it. September cooled sharply, and the L30 is down 44%, though share remains well above spring levels over the last 90 days. Model availability and a rare OpenAI-over-Anthropic spending shift kept the platform in the conversation.
Posts to understand this · as of Oct 11
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
Substack’s share bounced through spring and summer, then declined from July through September; the latest 30 days fell another 27.7%. The conversation is mixed: creators are testing more customizable alternatives, while Substack is still adding prominent writers and Notes is gaining publishing support.
Posts to understand this · as of Oct 10
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Semrush climbed into a June peak after its Lovable partnership and a burst of discussion about AI visibility, then fell sharply through August. September stabilized, and the L30 is up 10.9%, helped by practical relevance around Google’s new redirect system and Semrush’s claim that its tracking remained unaffected.
Posts to understand this · as of Oct 10
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva’s conversation share peaked in April, then fell through September, with a brief pause in August. The selected posts capture May connector exposure, August scrutiny of a lower growth forecast and AI serving costs, and September’s upgrade announcement, but none explains the longer decline. The L30 reading is up 22.9%, showing a recent rebound.
Posts to understand this · as of Oct 10
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Ahrefs jumped in May and stayed high in June as its AI visibility research fed a broader argument for treating LLM discovery as a distinct channel. Attention then dropped and settled into a narrower August-to-September range. The L30 is essentially flat at down 0.4%, even as Google redirects created fresh product scrutiny.
Posts to understand this · as of Oct 10
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier rebounded in May, then settled lower through summer before another September drop; the L30 is down 46.5%. The posts show a consistent pressure pattern: Claude hooks remove Zapier from workflows, agents propose handling integrations themselves, and adjacent GTM products keep absorbing orchestration.
Posts to understand this · as of Oct 10
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
ZoomInfo fell from March’s high, briefly recovered in June, then lost share through September; the L30 is down another 32%. No single event explains the slide: Ava 2.0 positioned itself as a ZoomInfo replacement, while Exa Connect and ZoomInfo’s Slack MCP increasingly cast its data as infrastructure inside other products.
Posts to understand this · as of Oct 10
Profound measures and improves how brands appear in AI answers.
Profound has been volatile but directionally stronger, from 0.2% in March to 0.7% in September, with the L30 up 51%. The latest lift aligns with its $180M Series D and unicorn valuation, while sustained criticism of content quality and sampling reliability keeps the conversation from becoming purely celebratory.
Posts to understand this · as of Oct 7
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
ElevenLabs recovered in September after a June-to-August lull, and the last 30 days added 58.9%; October’s partial bar is early context. The rebound is commercial, not just model news: posts point to more than $600 million in ARR, 59 open enterprise roles, and a sales team pushing vendors such as lemlist for fast product changes.
Posts to understand this
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio climbed steadily into a May high, then lost share each month through September. The May release of GTM Atlas fits the crest, following April attention around Intercom’s Fin for Sales and Attio’s inbound motion; with the L90 down 35.6% and the L30 down just 1.6%, the decline has recently flattened at a lower base.
Posts to understand this
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo.io surged from March to a May high as Claude-based workflows turned its database and actions into an agent-accessible layer. Conversation then eased across June through September, and the L30 is down 23.5%. The spring spike reflects a cluster of practical integrations that moved prospecting, enrichment, CRM work, and sequences out of Apollo’s interface.
Posts to understand this · as of Oct 12
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify’s share surged from 0.142% in March to 0.913% in May, but the selected conversation only becomes visible in June, when creators framed it as the data layer for Claude-based social analysis and content systems. Share held near 0.9% through July, then fell through September; a September GTM workflow mention shows continued utility, while the L30 move is down 28.9%.
Posts to understand this · as of Oct 7
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Granola peaked in May, declined through July, then recovered some attention in August and held near that level in September. Apple Watch access and a Grok sales integration broadened its footprint, while Muesli’s free, local alternative sharpened the competitive contrast; the L30 is now up 10.6%.
Posts to understand this · as of Oct 10
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
HeyReach rose from March through June, fell in July, stayed flat in August, then slipped again in September; the last 30 days fell another 41.2%. October’s first 13 days are only early context. Posts show no single reversal event: attention shifted from LinkedIn platform risk to doubts about automated outbound quality, with a quieter September milestone around $17 million ARR and 7,000 teams.
Posts to understand this
RB2B identifies the people and companies visiting a website so sales can follow up.
RB2B’s share climbed from March to a June high, then fell sharply through August before a modest September rebound. The conversation spans a late-May $9.1M ARR milestone and two September outbound playbooks that use website visits as a sales signal, while the latest 30 days are down 5.3%.
Posts to understand this · as of Oct 11
Intercom is a customer messaging platform built around Fin, its AI support agent.
Intercom fell from March through May, bounced in June, then collapsed to a much lower level in July before a modest September lift. No one post explains that volatility: discussion spans Fin observability, a reported Salesforce exit, and RB2B’s use of Fin for support. The L30 is up 26.0%, but the 90-day picture remains down 58.8%.
Posts to understand this · as of Oct 9
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
LangChain dropped sharply in April, recovered by June, then held a meaningful plateau through September instead of fading after the rebound. L30 is up 47.4% and L90 up 21%, with the conversation broadening across production agent evaluation, internal GTM agents, and teams comparing LangChain with Dust, Gumloop, and Vercel Workflows.
Posts to understand this · as of Oct 10
Baseten deploys and runs custom AI models in production.
Baseten built from July into August as Kimi K3 day-zero API support and the free Inference Engineering release gave the rise two concrete anchors. September stayed near that higher band as Harvey disclosed an M&A diligence partnership, but L30 has since fallen 33.2%; October’s first eight days are early context, not a completed drop.
Posts to understand this · as of Oct 8
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Conversation share climbed from March through July, dropped sharply in August, then recovered in September. The selected posts show Nooks appearing in an AI-native sales stack by May, a September critique of parallel dialing, and an October message about reliable revenue agents; October remains partial, while the last 30 days are up 13.7%.
Posts to understand this · as of Oct 10
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Common Room climbed steadily from March to a July high, when Zoom announced its acquisition, then attention dropped hard in August and September. The L30 is down 23.5%, so October’s partial bar is early context, not a reversal. Later discussion placed the deal inside a wider intent-data consolidation wave alongside Pocus and Warmly.
Posts to understand this · as of Oct 8
Exa.ai is a web search API designed for models and AI agents.
Conversation climbed through May, dipped in June, rebounded in July, then fell back in August. Applied GTM research, a technical explanation of agent search, and a September Sprites connector show the narrative broadening from use case to architecture to distribution, while the latest 30 days are up 25.3%.
Posts to understand this · as of Oct 6
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly’s share climbed from 0.263% in March to 0.540% in July, with a June product launch followed by HubSpot acquisition commentary in early July. It fell to 0.120% in September, when the acquisition resurfaced in a broader GTM consolidation discussion; the L30 move is nearly flat at 1.3%.
Posts to understand this · as of Oct 9
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode rose steadily from March to an August high as model and workflow integrations widened its reach, including Linear and Grok. Share dropped in September, and the last 30 days fell 26.8%; October’s partial bar is early context. Databricks’ Unity Gateway support shows the conversation has shifted from access toward centralized policy, model, and budget control.
Posts to understand this
Gamma turns prompts into presentations, documents, websites and images.
Gamma’s March high coincided with a Claude connector workflow, but the larger pattern is uneven decline rather than one decisive event. Atlassian integrations produced major moments in April and September without sustaining a climb; after a July low and August bounce, the last 30 days are nearly flat at +1.8%, while the 90-day trend is down 30.7%.
Posts to understand this · as of Oct 7
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps has moved in bursts rather than a sustained climb. Attention jumped in May around AirOps Next and the Quill release, then fell through July and settled into a narrow August-September plateau. That steadiness matters after the drop: category research still supports conversation, and the L30 is up 7.8% despite a 55.1% L90 decline.
Posts to understand this · as of Oct 10
1mind provides AI sales agents for websites, demos, live calls and customer success.
1mind reached modest highs in March and June, then lost ground through September; the last 30 days are down another 5.3%. The March Clari and Salesloft partnership and May marketing hire created distinct bursts, while an October CEO roundup offers early visibility but no evidence yet of renewed momentum.
Posts to understand this
Firecrawl turns websites into clean, structured data for models and agents.
Firecrawl’s share climbed from March through May, fell in June, hit a higher peak in July, then settled lower through August and September. May’s Claude Code lead-gen walkthrough and July’s onboarding praise tracked the two bursts, while a late-September data-provider listing aligns with the current L30 rebound.
Posts to understand this · as of Oct 11
Higgsfield generates video and images for ads and social content.
Higgsfield climbed from April through June, held flat in July, then lost ground in August before a modest September recovery. The L30 gain of 27.9% aligns with fresh product heat around AI Influencer, while Together AI’s infrastructure support explains how Higgsfield can sustain high-volume video workloads.
Posts to understand this · as of Oct 6
Grok Bot is an always-on agent that learns routines and completes work across existing software.
The conversation appeared in August alongside the beta launch and an early example of the bot handling a service cancellation, then gained share in September. October is still partial, while the last 30 days are down 13.2%; a recent X-data update is the clearest current thread.
Posts to understand this
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce appeared in August and grew in September around its launch and Dreamforce discussion. The announcement burst has cooled, with the L30 down 39.7%, while the remaining conversation centers on a sharper question: when should Claude provide the interface, and when should a company own its AI harness?
Posts to understand this · as of Oct 12
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
Conversation jumped from 0.31% share in August to 5.07% in September, alongside an early-September benchmark, broad token access, and a later customer account of day-to-day use. The last 30 days are down 5.1%, so attention has eased from that September peak as discussion widened from model performance to availability and production use.
Posts to understand this · as of Oct 10
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Claude Fable appeared from almost zero in June and reached its high in July after the Fable 5 launch. Attention fell in August, rebounded with Fable 5.1’s September arrival in Cursor, then dropped 55.9% over the last 30 days; October’s first eight days only provide early context for that cooling.
Posts to understand this · as of Oct 8
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
After an April spike, GPT-5 fell sharply in May and stayed low through September. No single launch in the posts explains the recent movement: benchmark comparisons, inclusion in Replit’s model picker, and September cost criticism form a thin but recurring drumbeat. The L30 measure is up 107.7%, though L90 remains down 28.6%.
Posts to understand this · as of Oct 7
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Claude Opus moves in launch-driven bursts: an April jump held through May after Opus 4.7 reached Perplexity and Harvey, followed by sharp resets in June and August. September rose again, and the 259.4% L30 gain points to fresh momentum from Opus 5.5 entering Cursor with stronger benchmark results and lower task costs.
Posts to understand this · as of Oct 10
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Grok 4’s July spike aligns with Grok 4.5 distribution and benchmark wins: Perplexity added it as an orchestrator, while AutomationBench ranked it first. Share eased in August and September, but the last 30 days rose 43.5%; the early October bar is incomplete, and September’s Grok 4.7 coding result suggests renewed model-led attention.
Posts to understand this
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Conversation spiked in June, fell through August, then turned up in September. The rebound followed late-September Sonnet 5.5 rollouts across Snowflake, Netlify, and Hyperbrowser, while the 348.9% L30 increase shows attention is still rising in October rather than treating the partial month as complete.
Posts to understand this · as of Oct 10
Muse Spark is Meta's AI model for running coding and other agents.
Muse Spark built gradually from July through September after a small and volatile spring base, but the last 30 days fell 34.3%; October’s partial bar is early context. The rise came from repeated product and benchmark exposure rather than one event: Meta introduced Muse on Spark 1.3, while leaderboards placed Spark 1.1 near the top and Spark 1.3 behind Mistral Large 4.
Posts to understand this
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Conversation surged with the May release, then rebounded in July as independent tests highlighted strong browser-agent price and performance. September’s security partnership showed continued adoption, but momentum has since cooled, with share down 66.4% over the last 30 days.
Posts to understand this · as of Oct 10
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
Kimi’s sharp July spike came from K3’s price-performance story: Together AI put it near Claude Fable 5 performance at about 35% of the price, while Vercel showed a lower-cost cybersecurity tradeoff. Share then fell through August and September, and the last 30 days dropped 27.5%; a limited free offer in Cline created attention but did not sustain the July level.
Posts to understand this
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen climbed in July and reached an August high as n8n added a Qwen Cloud node for multimodal and agent workflows. September fell sharply despite a local deployment example and the Qwen-Image-2.1 release; the 45.9% L30 decline shows those updates did not sustain the integration-led lift.
Posts to understand this · as of Oct 11
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM broke from near-zero share in June when GLM 5.2 drew attention as a local, open coding model, then held a much higher band through summer. September brought Notion distribution and strong Bolt adoption for GLM 5.3 Flash, but the L30 measure is down 32.3%, so recent reach has not sustained the earlier pace.
Posts to understand this · as of Oct 9
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos spiked in April on the controlled cybersecurity preview, then again in June as scarce access and zero-day claims kept curiosity high. Attention fell back after each burst and is down 45% over the last 30 days; even September’s Claude Mythos 5.1 introduction did not restore those launch-driven highs.
Posts to understand this
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney’s share jumped from 0.358% in May to 0.637% in June, when Gamma showed the product inside its brand system and discussion highlighted its community-funded model. Share then fell through September, with a further 26.0% L30 decline; the latest evidence casts Midjourney as one component inside a Claude-built film workflow, not the main launch.
Posts to understand this · as of Oct 10
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Devin’s conversation has been episodic: Windsurf 2.0 drove an April burst, then attention returned around parallel cloud agents and software factories in August. L90 remains up 56.4%, but L30 has fallen 64.1%, so the current direction is sharply lower. October’s early security benchmark is fresh context, not evidence of a completed reversal.
Posts to understand this · as of Oct 12
Runway is an AI platform for generating and editing video and images.
Runway’s share softened through July and August, then jumped sharply in September; the August competitor pricing comparison is the closest visible lead-in, but it does not establish the spike’s cause. October is partial, and the L30 measure is down 7%, even as fresh future-of-work coverage keeps Runway in view.
Posts to understand this · as of Oct 9
Jev is TypeSafe AI's decision model, which returns typed answers such as choices, probabilities and scores instead of text.
Jev went from no visible share through August to an immediate September burst. It remains a new conversation in the L30, while October’s first 12 days offer only early context; the launch spread through fast AI Gateway adoption, LangChain evaluation, and a concrete HeyGen lead-routing workflow.
Posts to understand this · as of Oct 12
Muse is Meta's personal AI agent, which connects to a person's email, calendar and payments to shop, book and schedule for them.
Muse was absent through July, appeared in August, then jumped sharply in September; the 401.2% L30 gain says attention is still expanding. The rise came from concrete demonstrations and debate: restaurant reservation prompts, Bland-powered phone calls, and questions about accountability when consumer and service agents interact.
Posts to understand this · as of Oct 11
Instinct is a personal AI agent with its own email address that creates accounts, contacts businesses and handles support requests for its user.
Instinct emerged in August, broke out in September, and is up 385.1% over the last 30 days. The curve reflects a cluster, not one announcement: rapid valuation chatter and repeated word of mouth established the brand, while October’s early Personal Agent Protocol announcement connected Instinct to Meta, Sierra, Shopify, Stripe, and Walmart.
Posts to understand this · as of Oct 8
Join 19,413+ GTM leaders and practitioners. Free, unsub anytime.
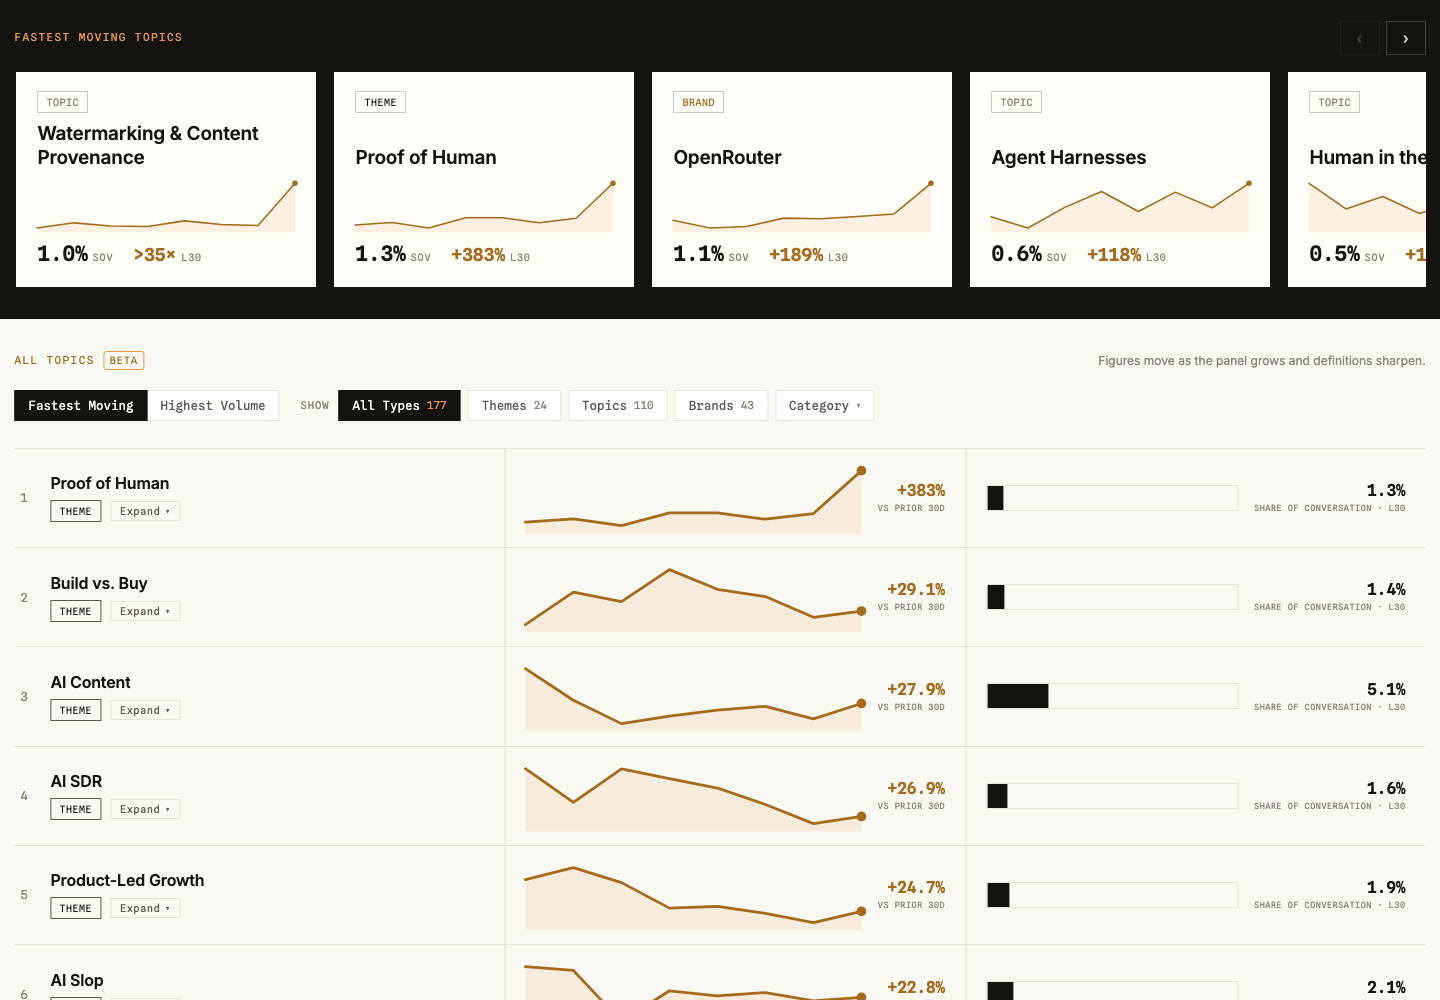
Loading people…
join 19,413+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-10-13.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,413+ gtm leaders, unsub anytime.