What’s moving now
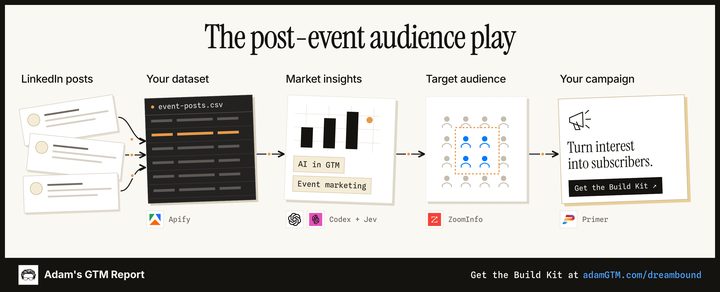 My post-conference playbookSep 24 · How to collect the conversation, find an angle, and build
 15.2× the usual response · 1,047 engagements
 14.6× the usual response · 1,637 engagements
 11.0× the usual response · 19,894 engagements
 F10.4× the usual response · 109 engagements
 4.6× the usual response · 458 engagements
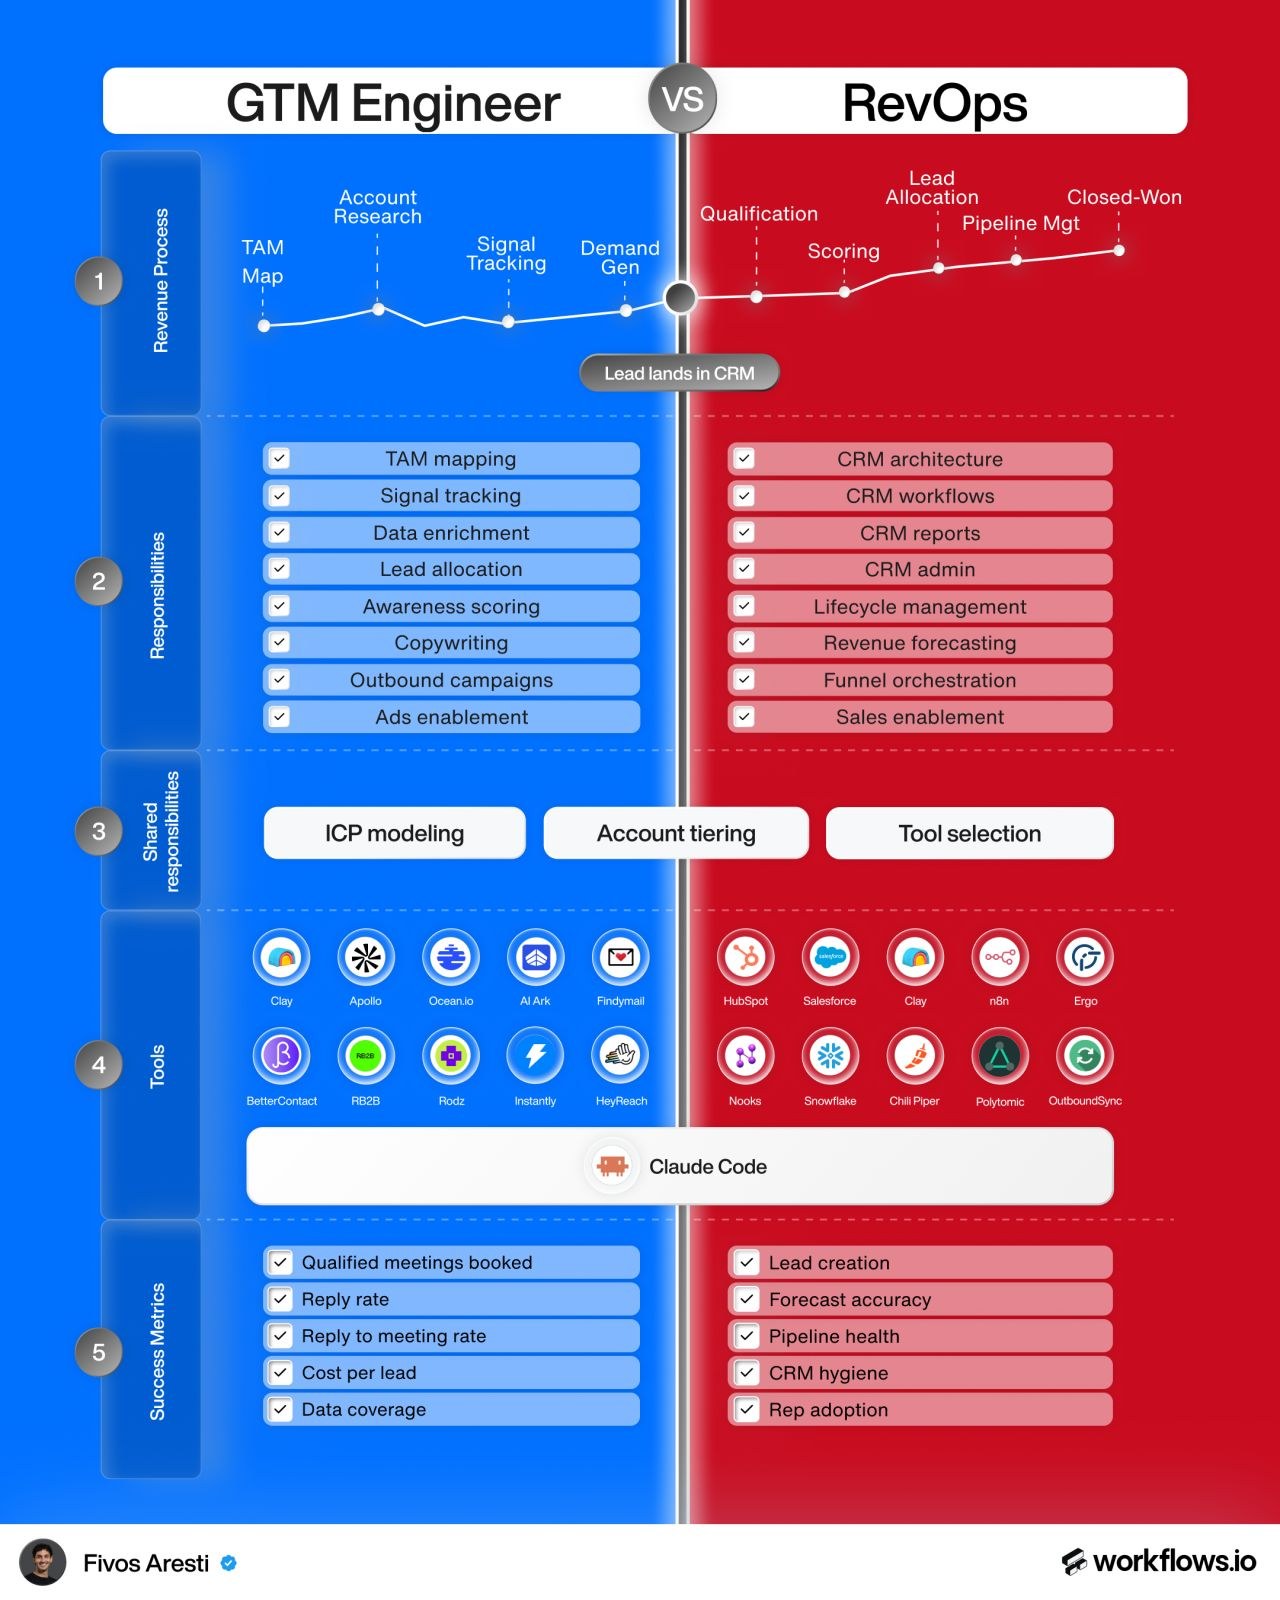
 Fivos ArestiDefines GTM engineering around research, signals, and demand generation, and RevOps around CRM and pipeline management, with shared responsibilities varying by company.
 676 interactions · 1d agoTrending Creator
 Ryan WalshPredicts AI companies’ expanding sales teams will recruit from traditional software firms, triggering backfills and a stronger job market for tech sales candidates.
 582 interactions · 1d agoTrending Creator
 Morgan IngramPredicts B2B sales will return to personal outreach and face-to-face meetings, citing a claimed $74,000 AppZen deal from an in-person event strategy.
 504 interactions · 2d agoTrending Creator
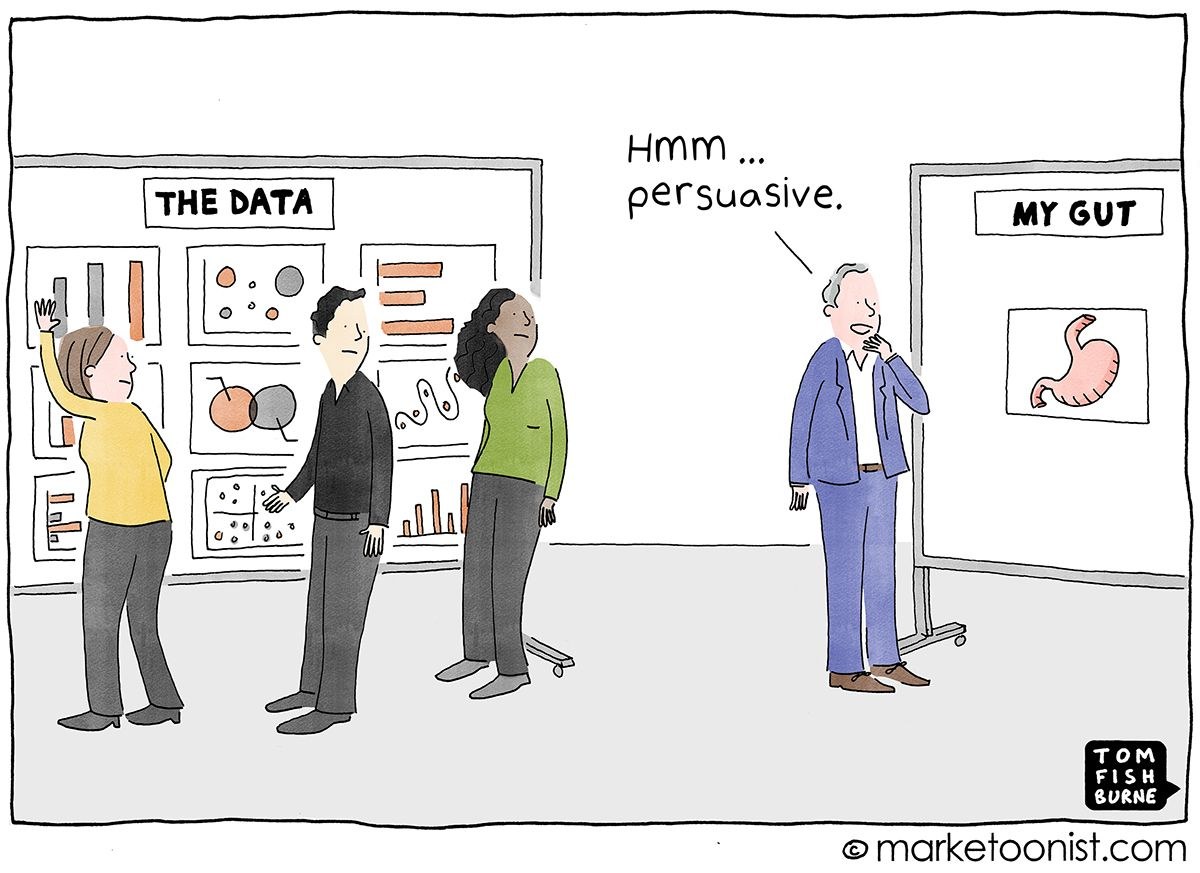
 Tom FishburneWarns that AI-assisted decisions can amplify senior leaders’ opinions and users’ biases, urging scrutiny of whether recommendations reflect evidence or gut feelings.
 480 interactions · 2d agoTrending Creator
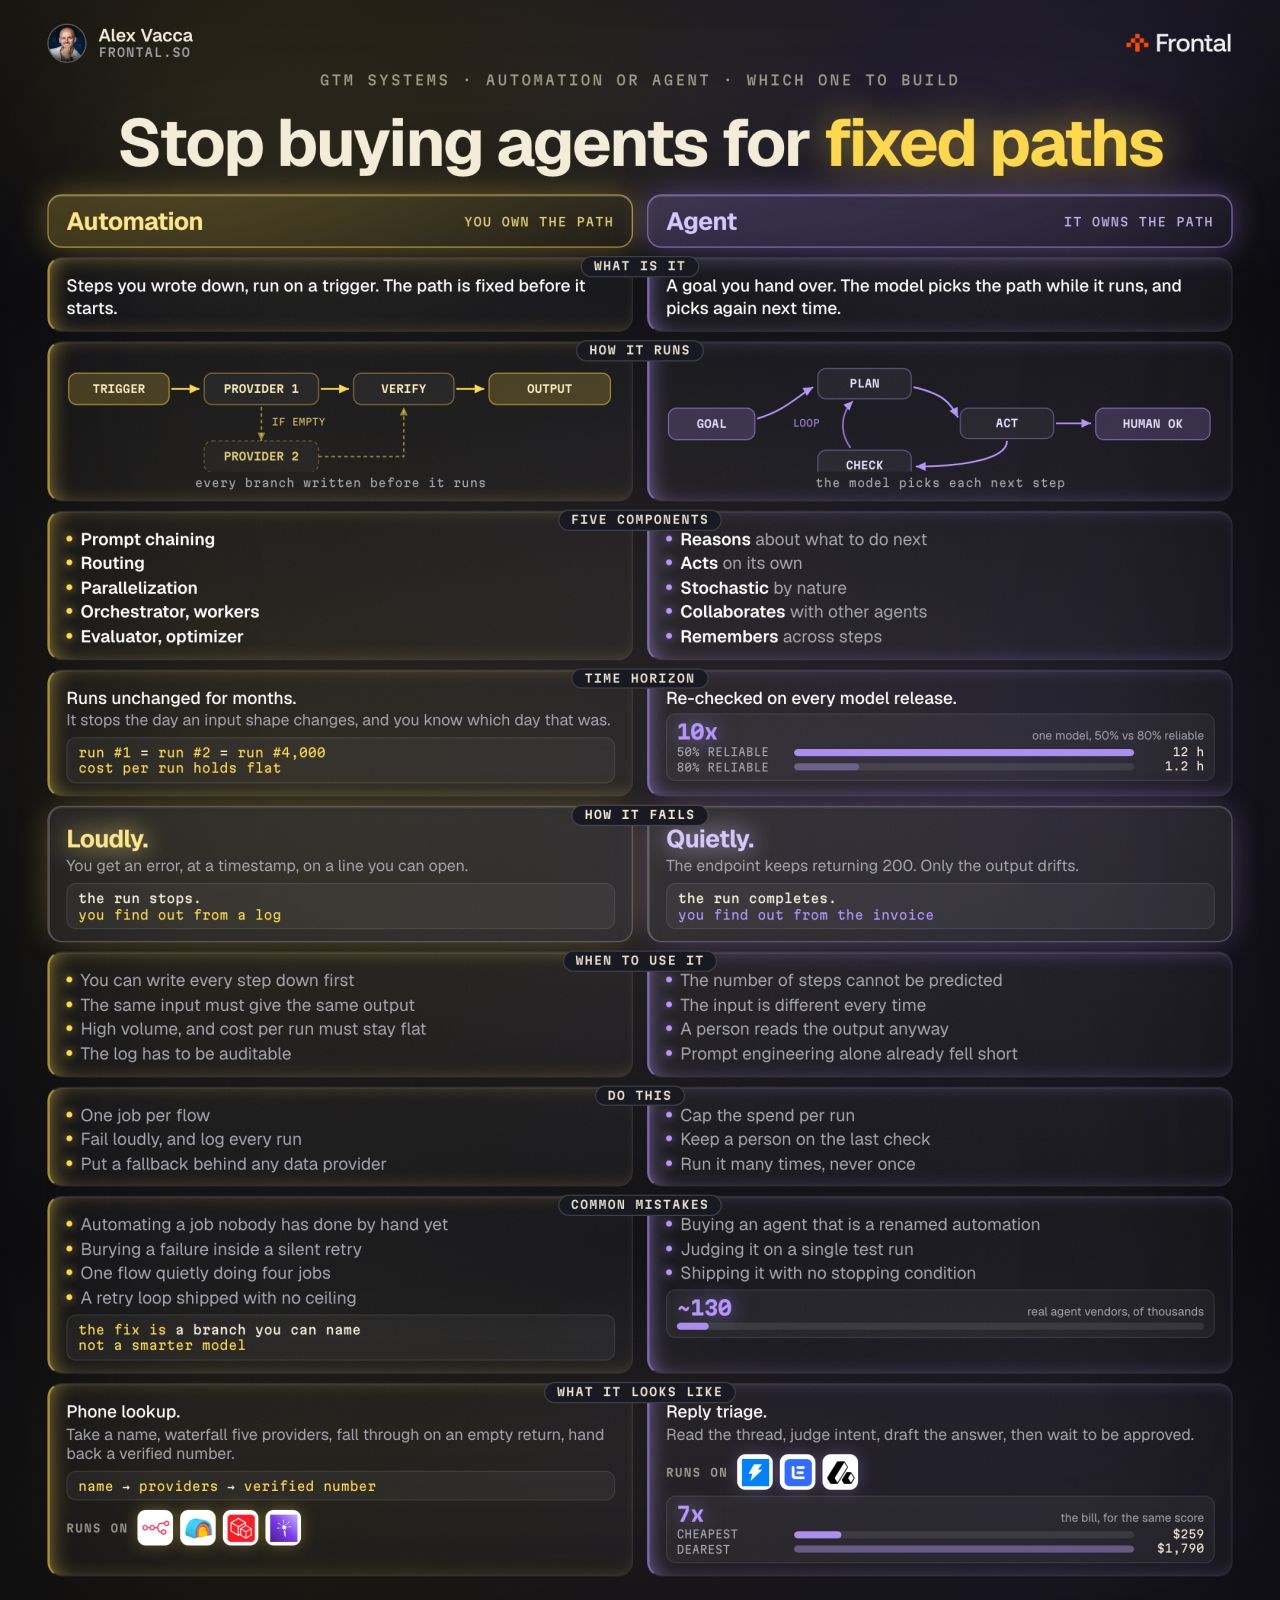
 Alex VaccaReports $384 monthly n8n costs, estimates $60,000 for equivalent Claude workloads, and argues fixed workflows suit automations while agents need human oversight.
 465 interactions · 1d agoTrending Creator
 Lenny RachitskyMarty Cagan argues that good product work fundamentally requires thinking and says he underestimated the lengths people would go to avoid it.
 438 interactions · 10h agoTrending CreatorFivos ArestiReports $3.3M ARR and 21 employees at Q3’s end, slower AI adoption, problems with flat management, and planned engineering and sales hires.
 341 interactions · 15h agoTrending Creator
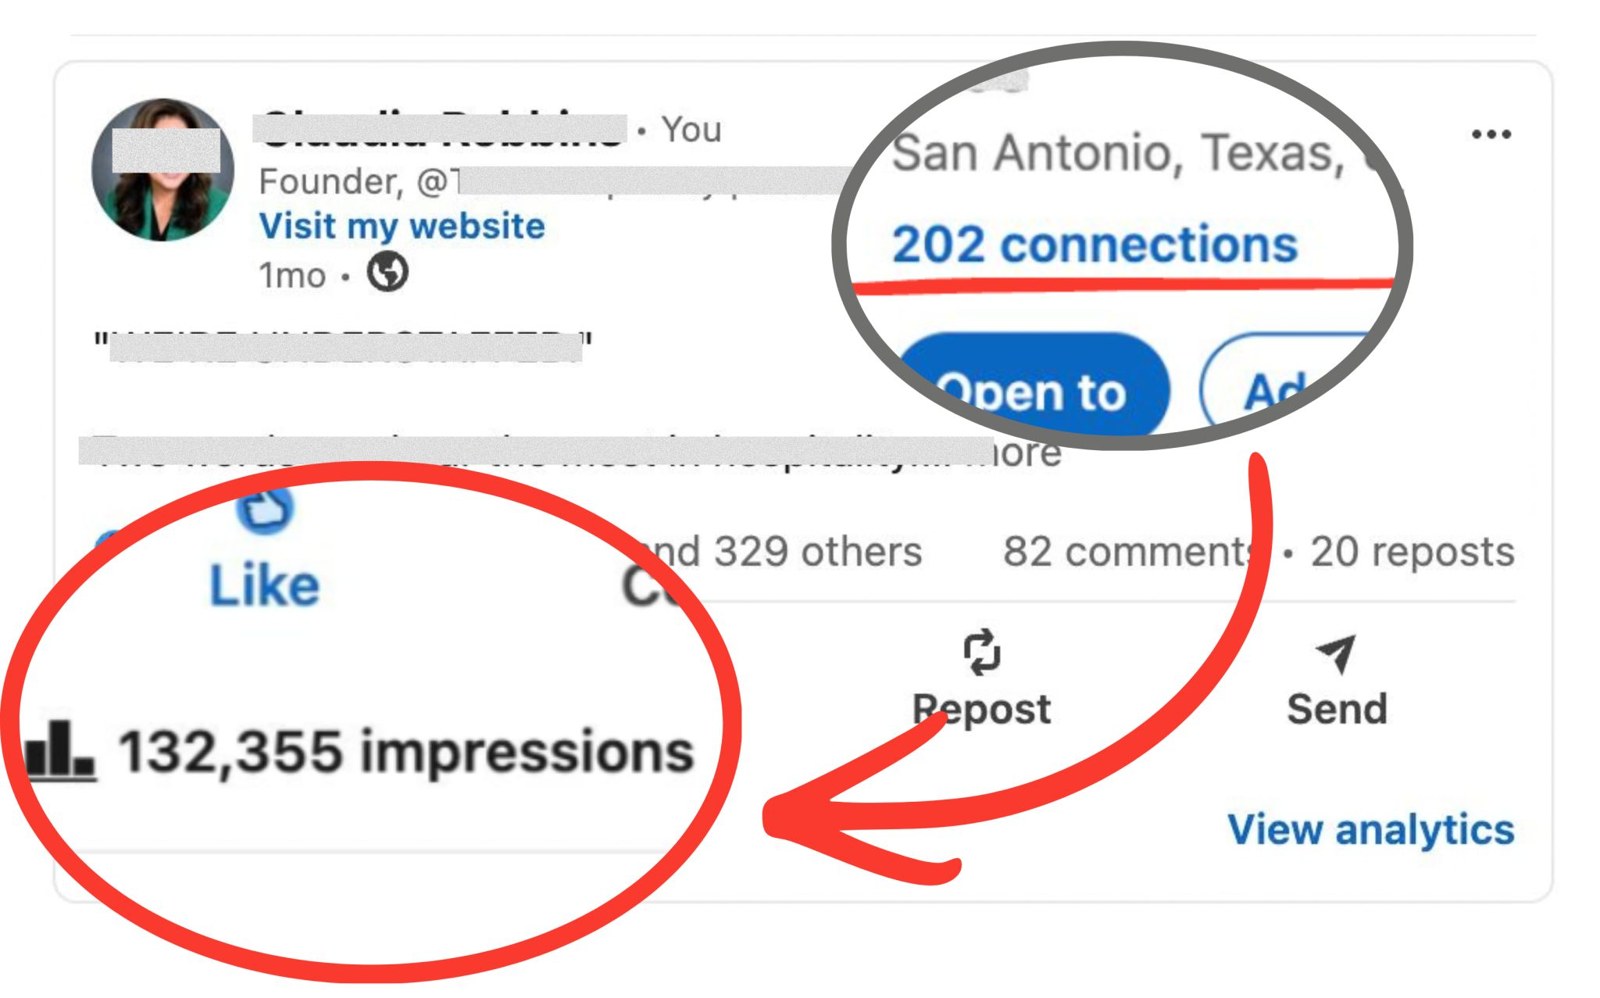
 Diandra EscobarDistinctiva argues that industry opinions backed by experience can establish authority and attract buyers for founders with small networks, using its GASP content framework.
 304 interactions · 2d agoTrending Creator
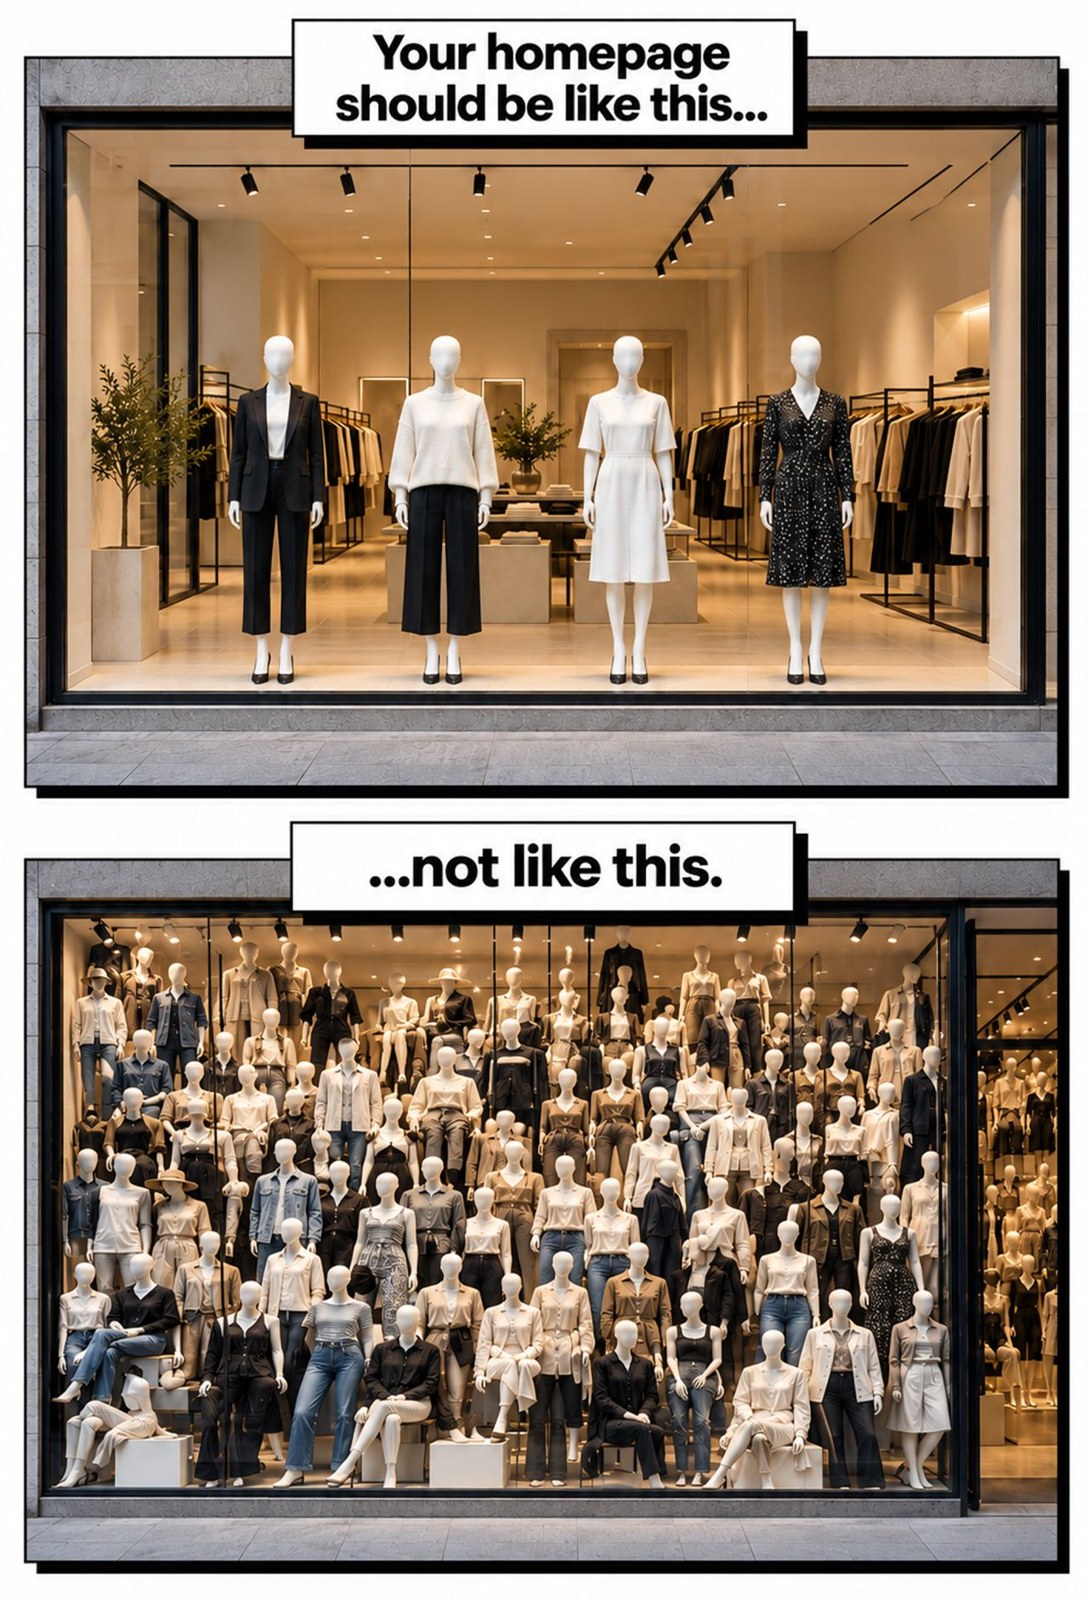
 Anthony PierriRecommends using inbound sales calls to identify buyers’ key capabilities and emphasizing those on homepages, arguing that additional features rarely overcome flagship feature disinterest.
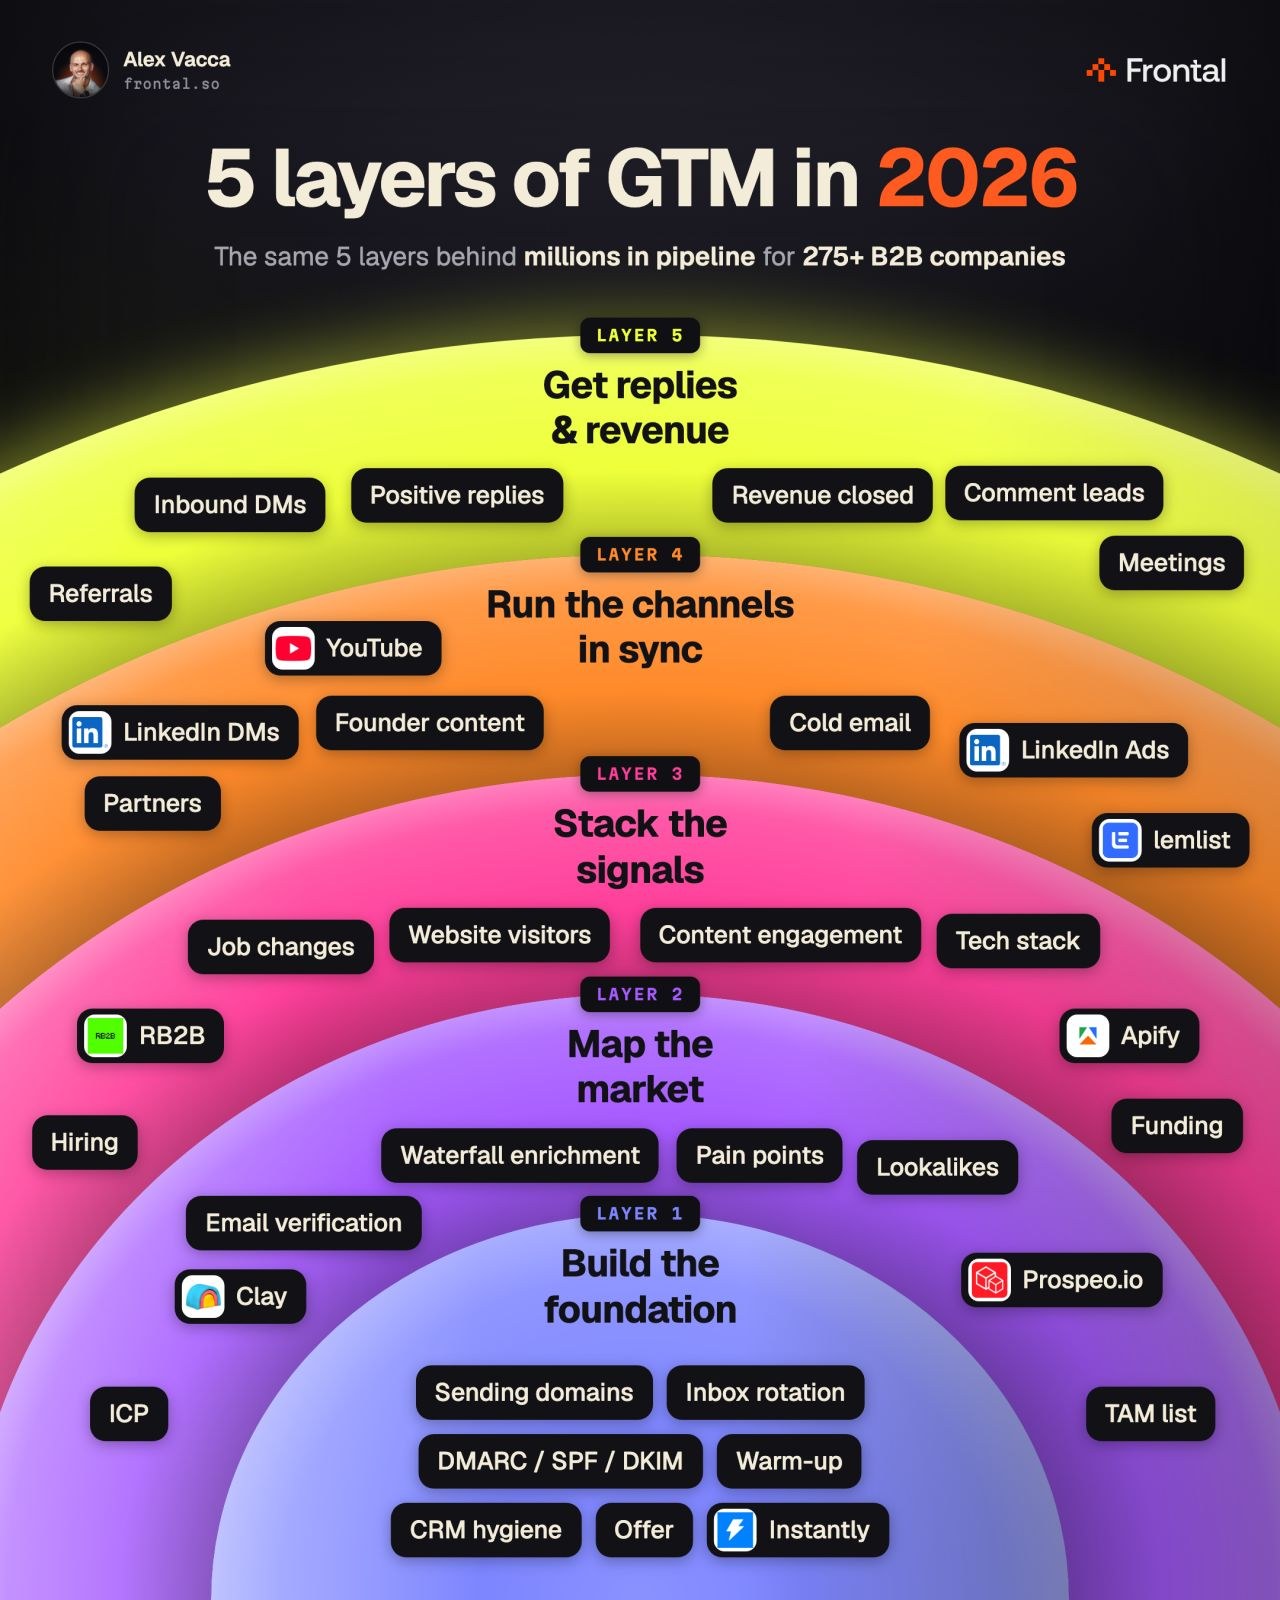
 301 interactions · 2d agoTrending CreatorAlex VaccaFrontal AI argues outbound performance depends on infrastructure, market targeting, buying signals, and coordinated channels before copy, with positive replies and revenue as measures.
 294 interactions · 16h agoTrending Creator
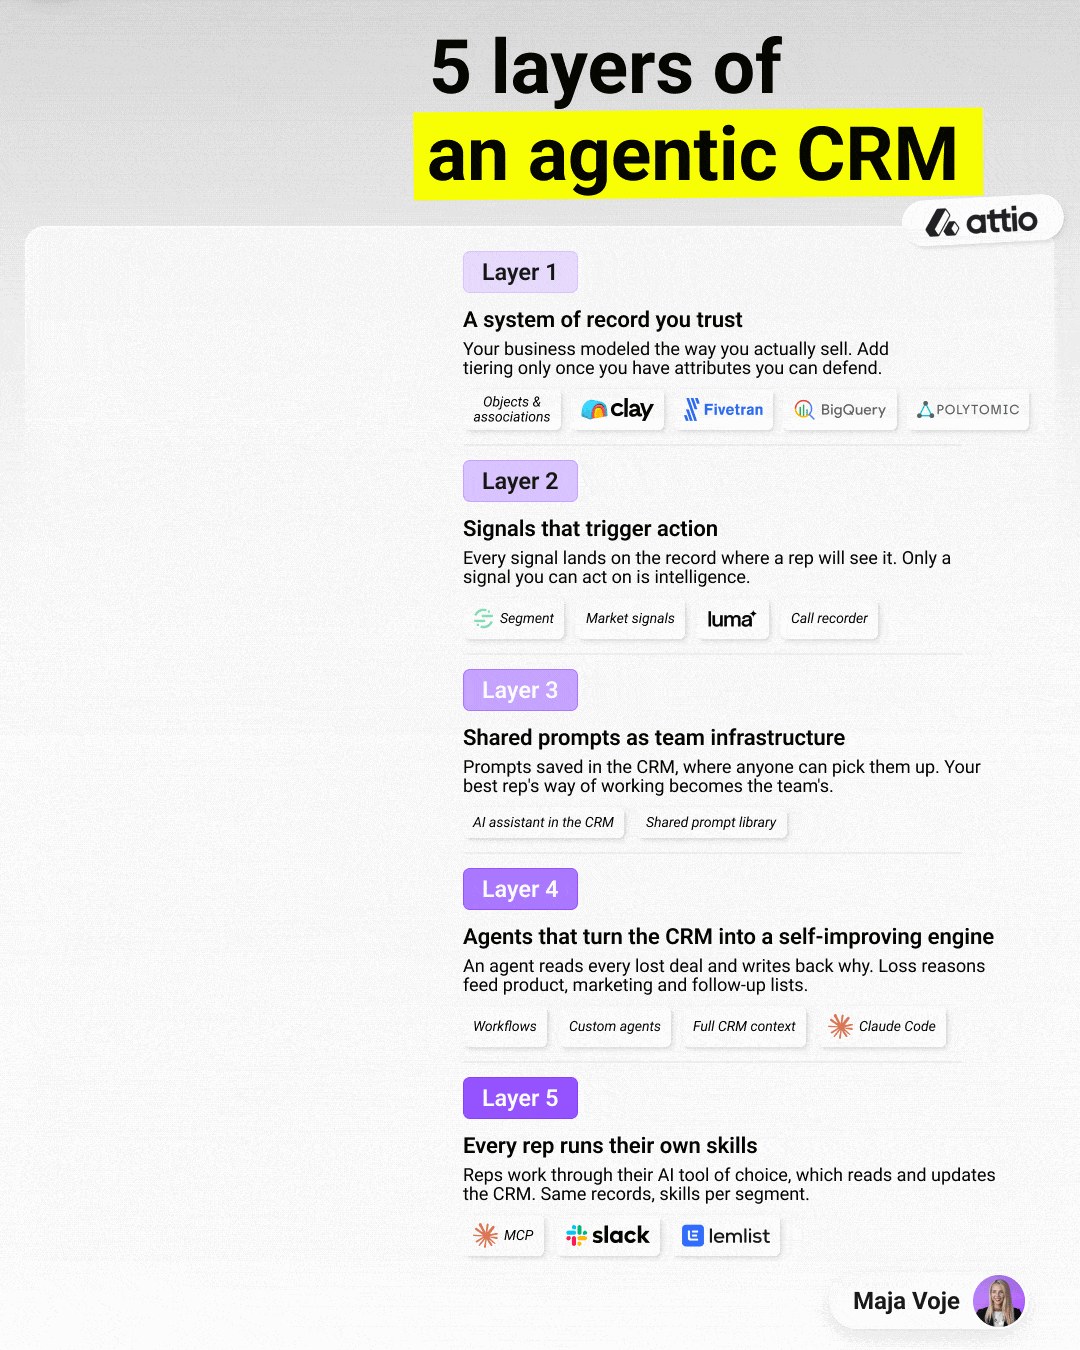
 Maja VojeDescribes Attio’s CRM approach: trusted records, actionable signals, shared prompts, automated loss analysis, and personalized Claude skills.
 280 interactions · 2d agoTrending CreatorDiandra EscobarAnnounces a free Claude skill that reportedly generates LinkedIn hooks in four formats, identifies promising draft passages, and checks mobile display fit.
 278 interactions · 1d agoTrending Creator
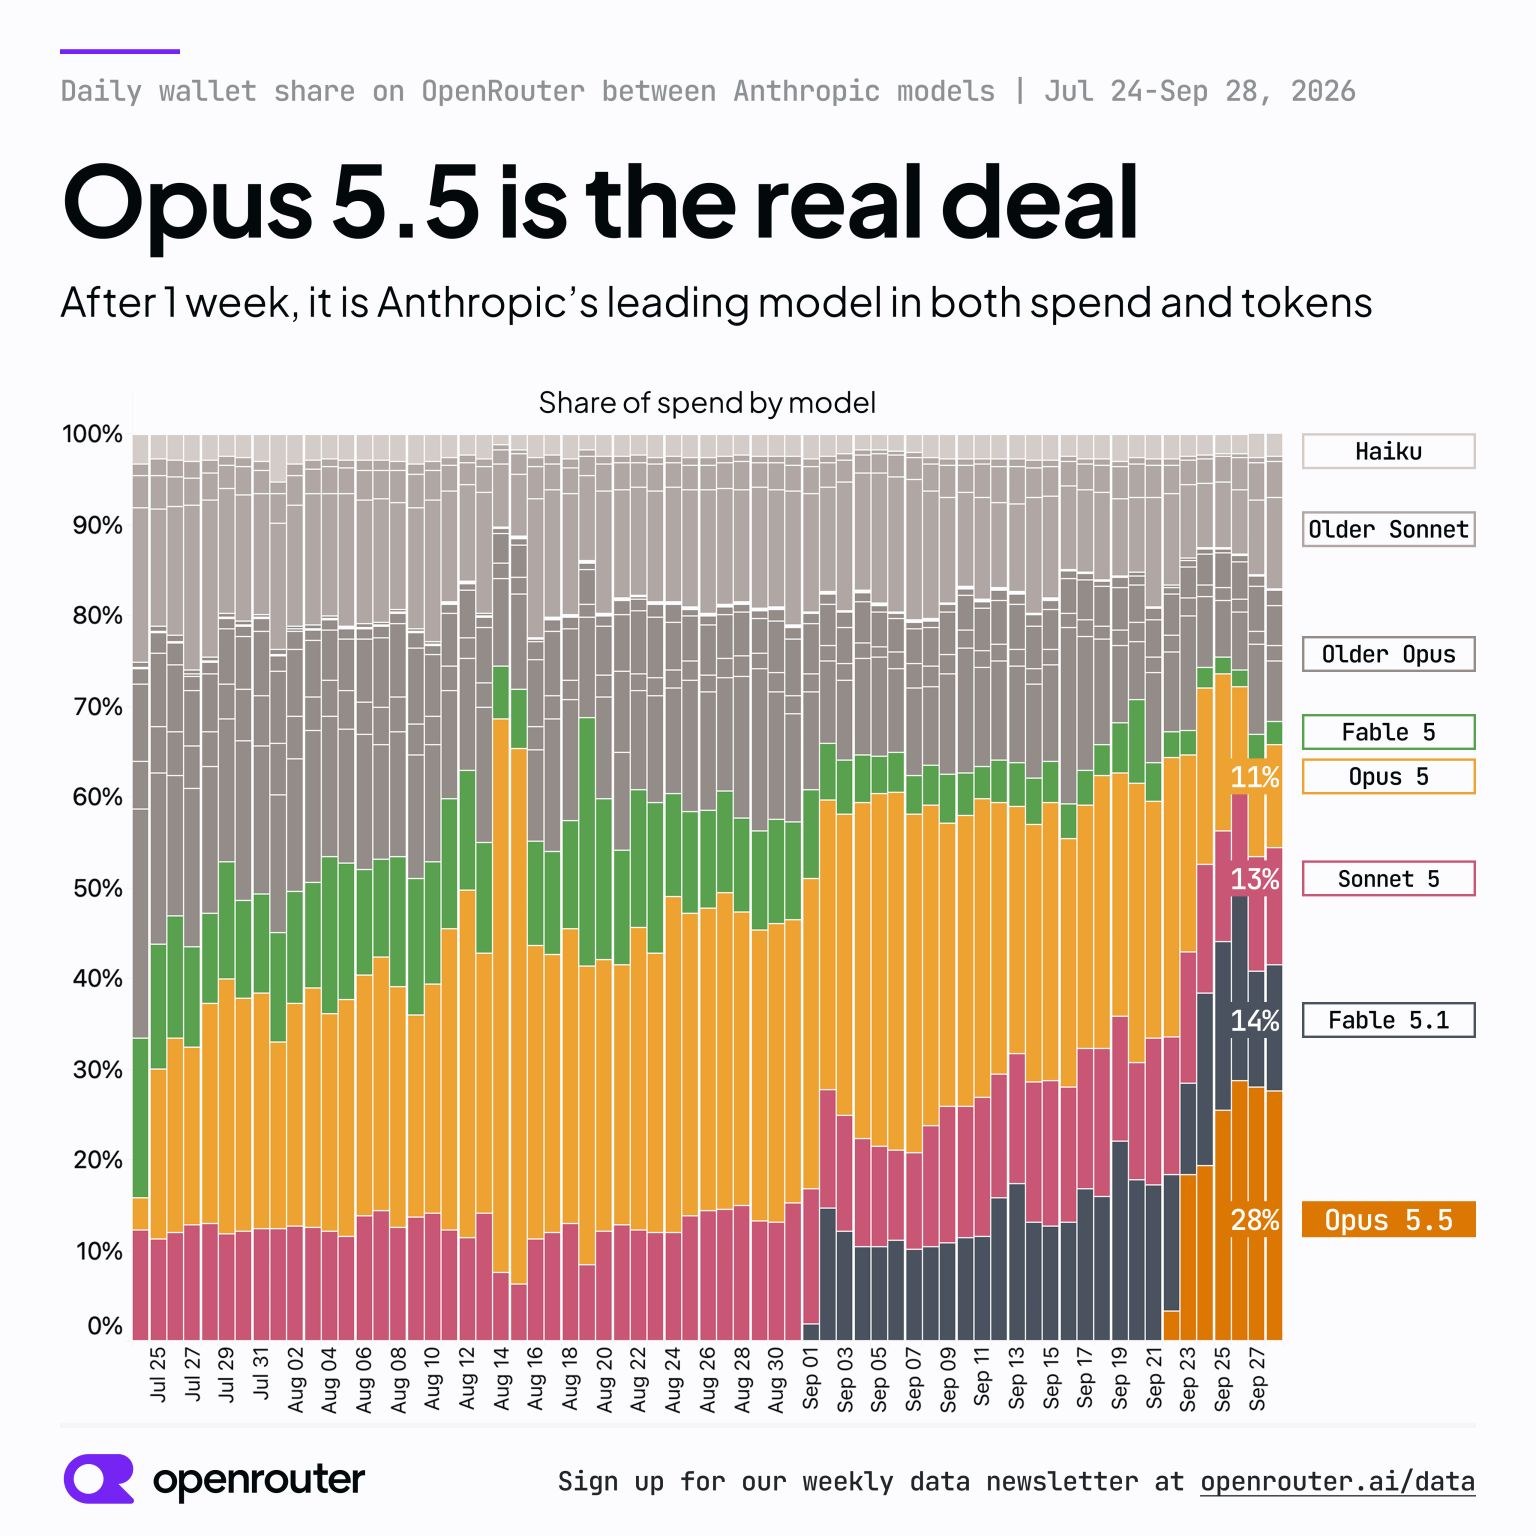
 Peter WalkerExpresses optimism about Claude Opus 5.5, reporting leading OpenRouter spending, complete migration by 54% of Opus 5 users and adoption by 28% of initial testers.
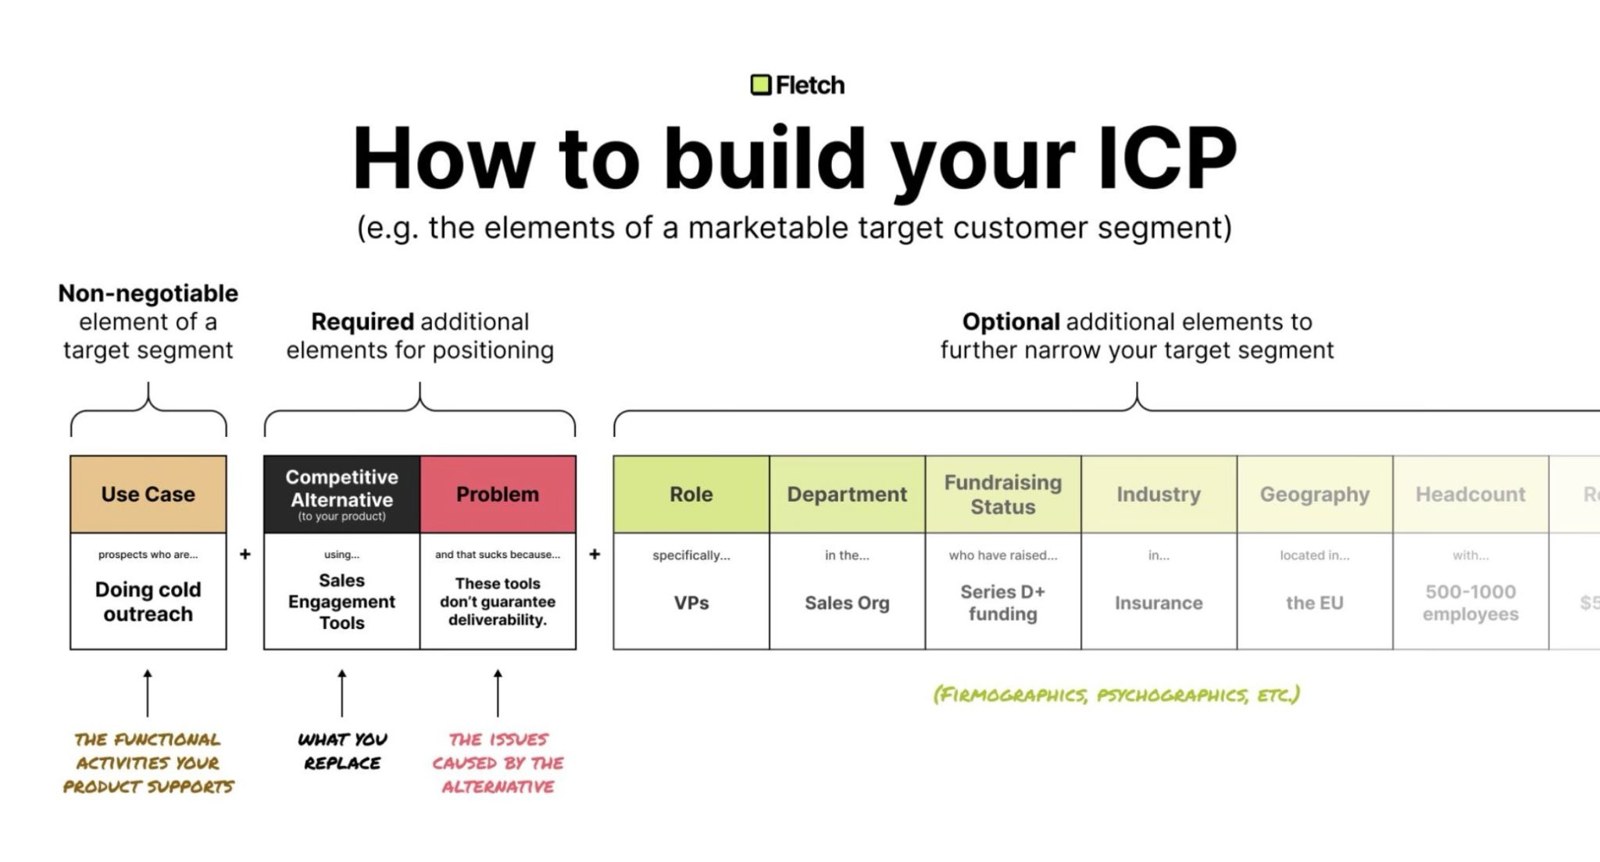
 278 interactions · 2d agoTrending CreatorAnthony PierriArgues that ideal customer profiles should prioritize activities the software supports, such as outbound sales, before adding firmographics and other segment details.
 274 interactions · 1d agoTrending Creator
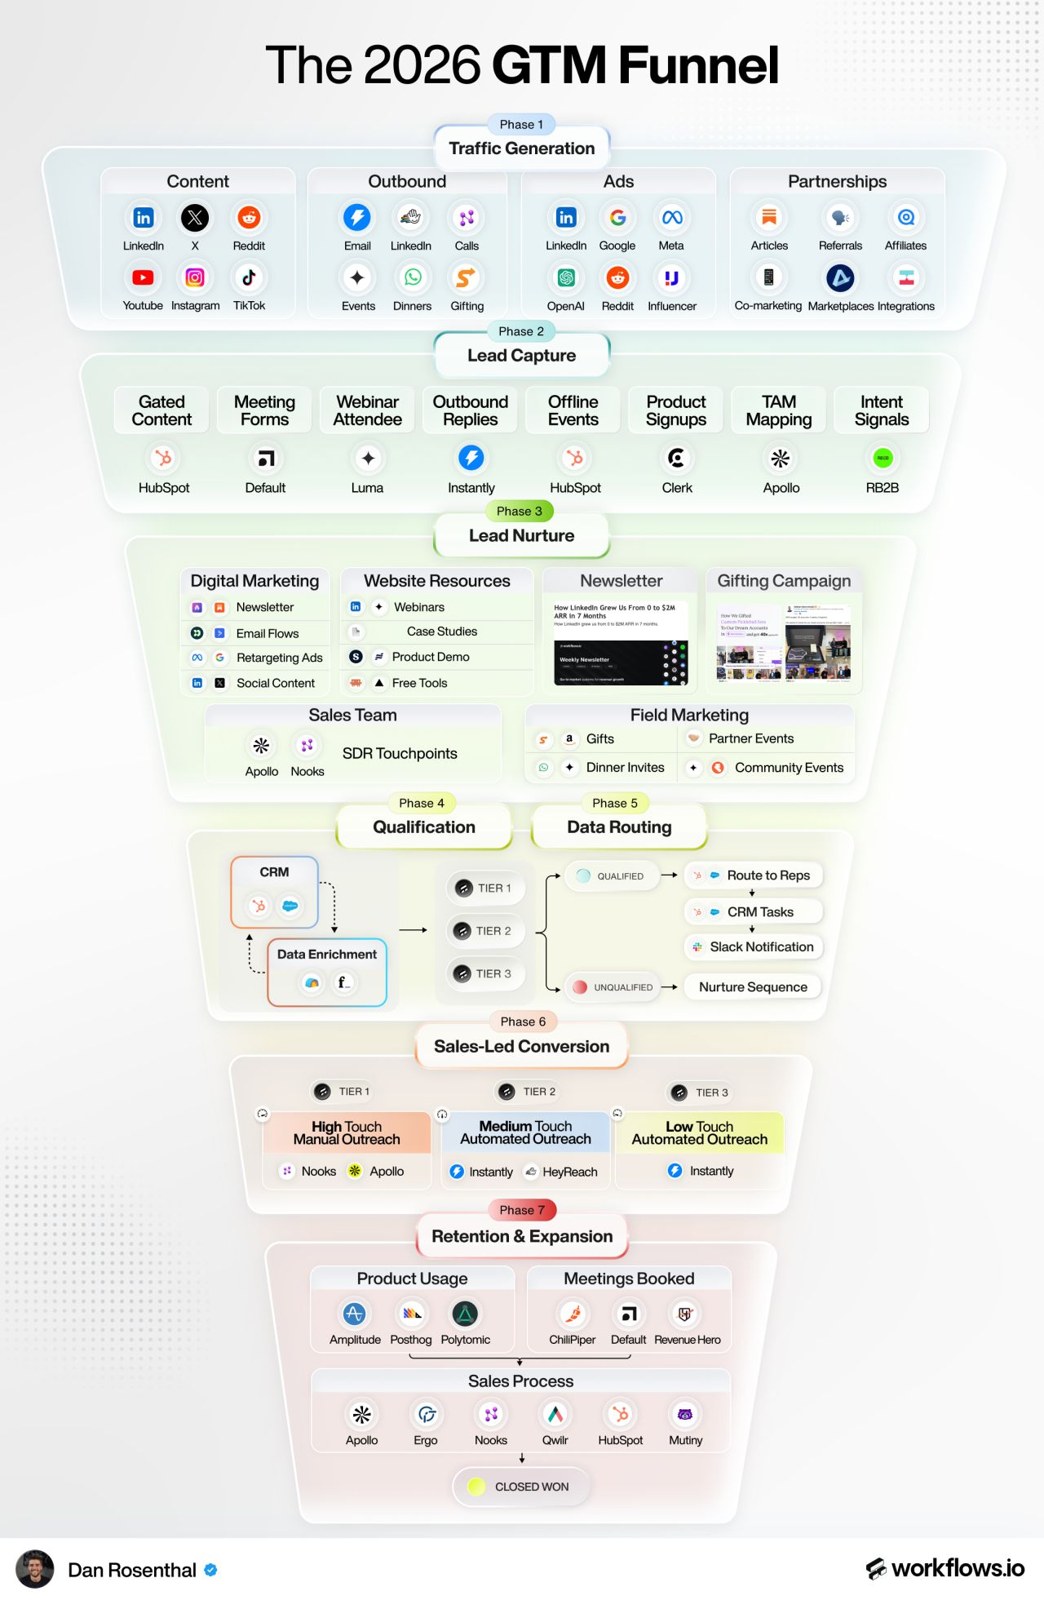
 Dan RosenthalWorkflows.io shares its seven-stage client funnel blueprint, covering traffic generation, lead capture, nurture, qualification, routing, tiered sales outreach, and retention and expansion.
 264 interactions · 1d agoTrending Creator
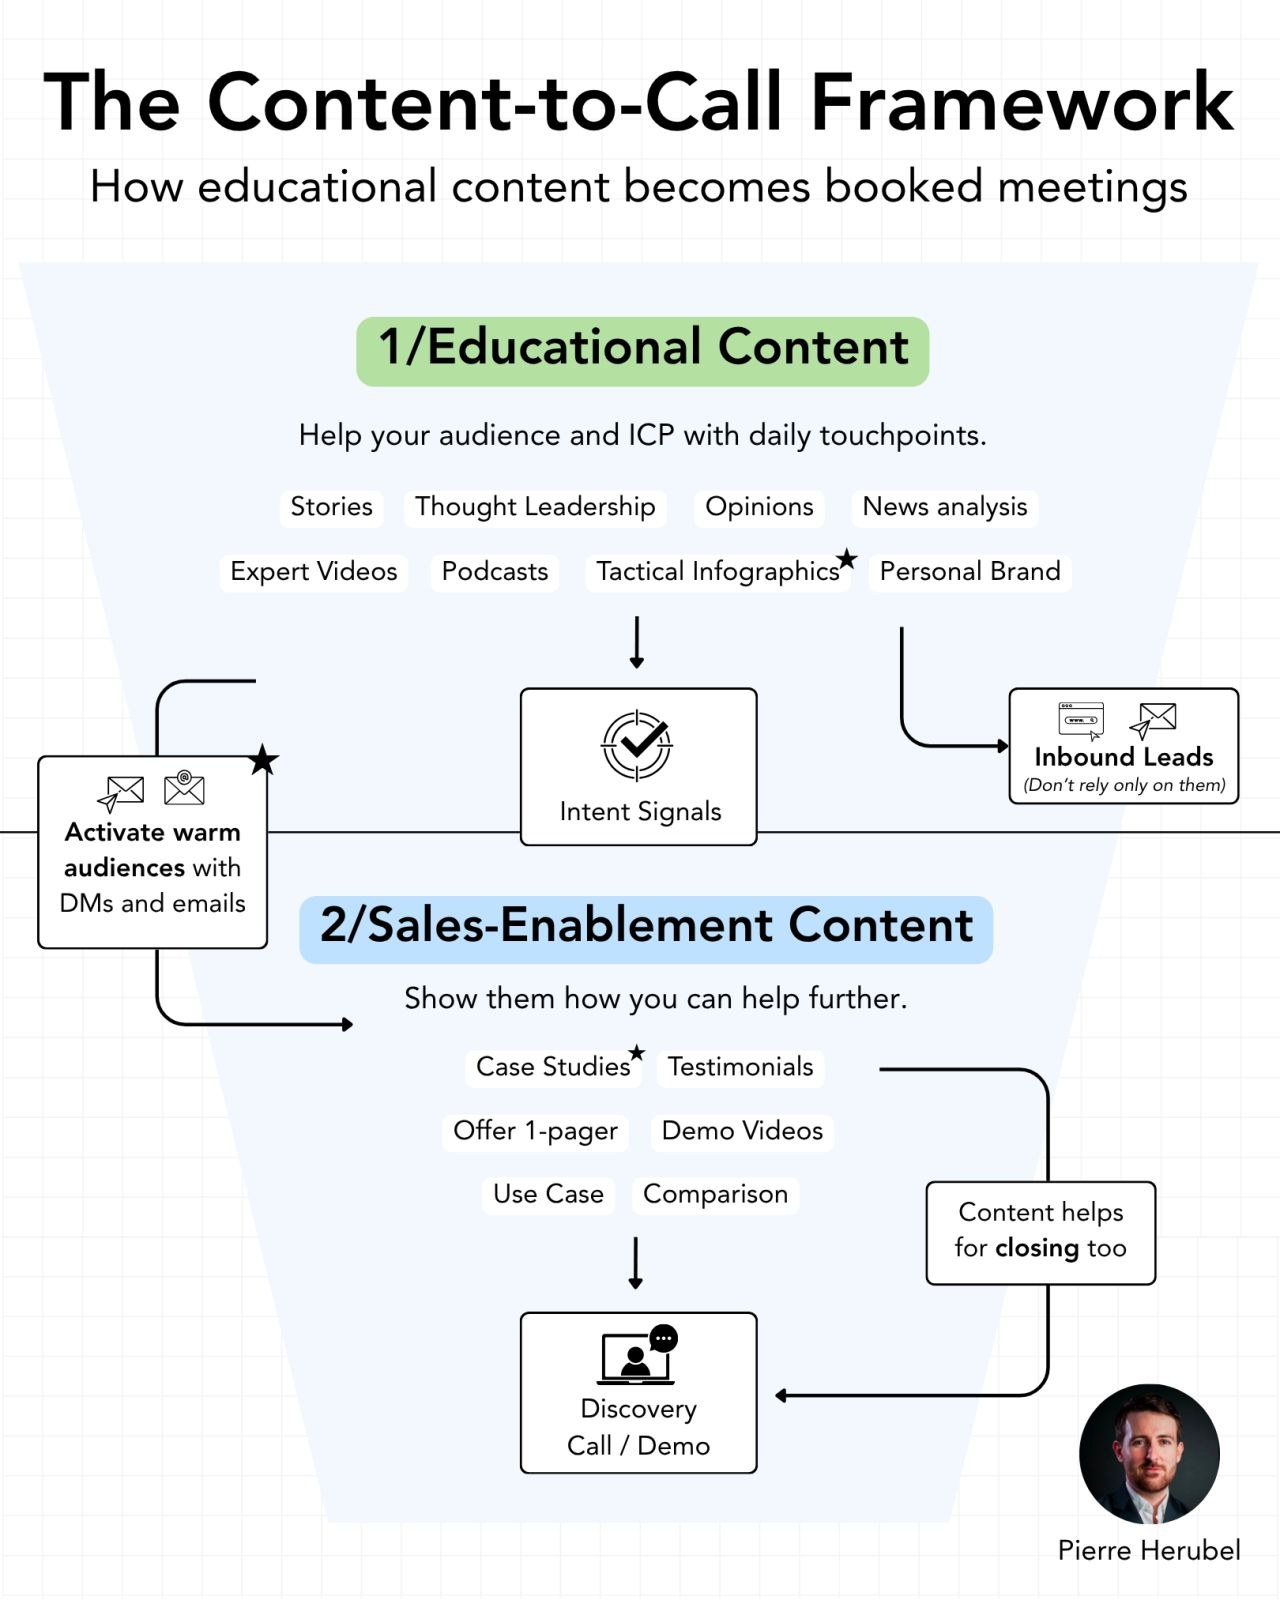
 Pierre HerubelProposes a content-to-call framework combining educational content, demand capture, intent detection, warm outbound and sales enablement to address missed B2B sales opportunities.
 258 interactions · 2d agoTrending Creator
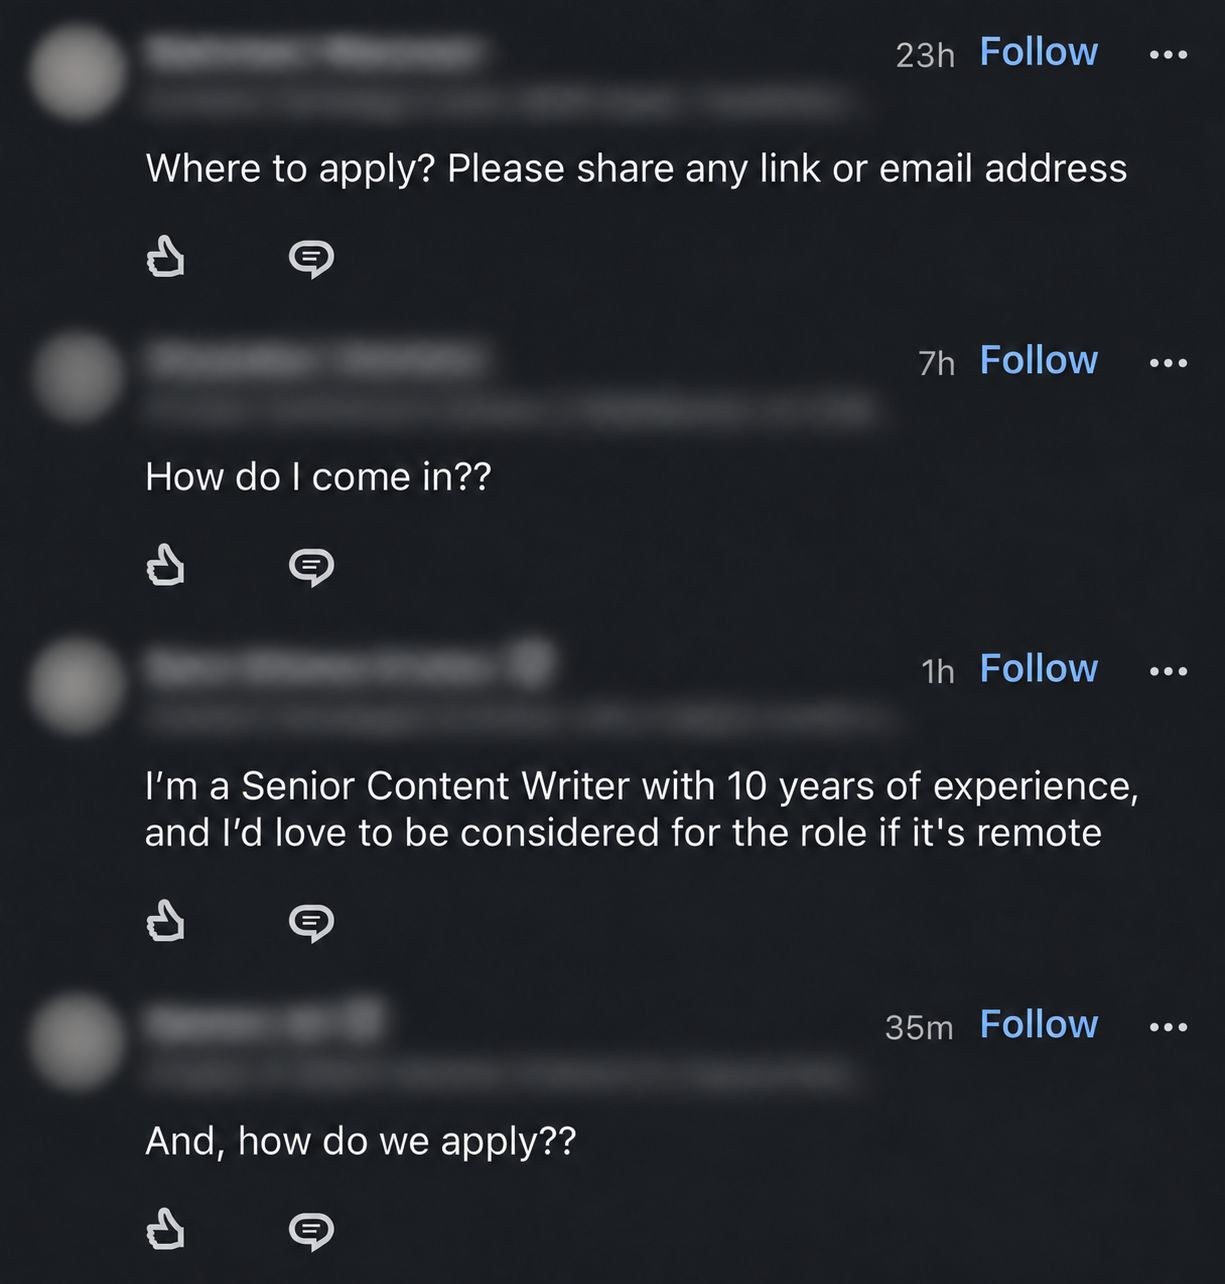
 Tommy ClarkCompound’s author argues that candidates asking where to apply for its Senior Content Writer role, instead of finding the company’s LinkedIn listing, signal insufficient initiative.
 247 interactions · 1d agoTrending Creator
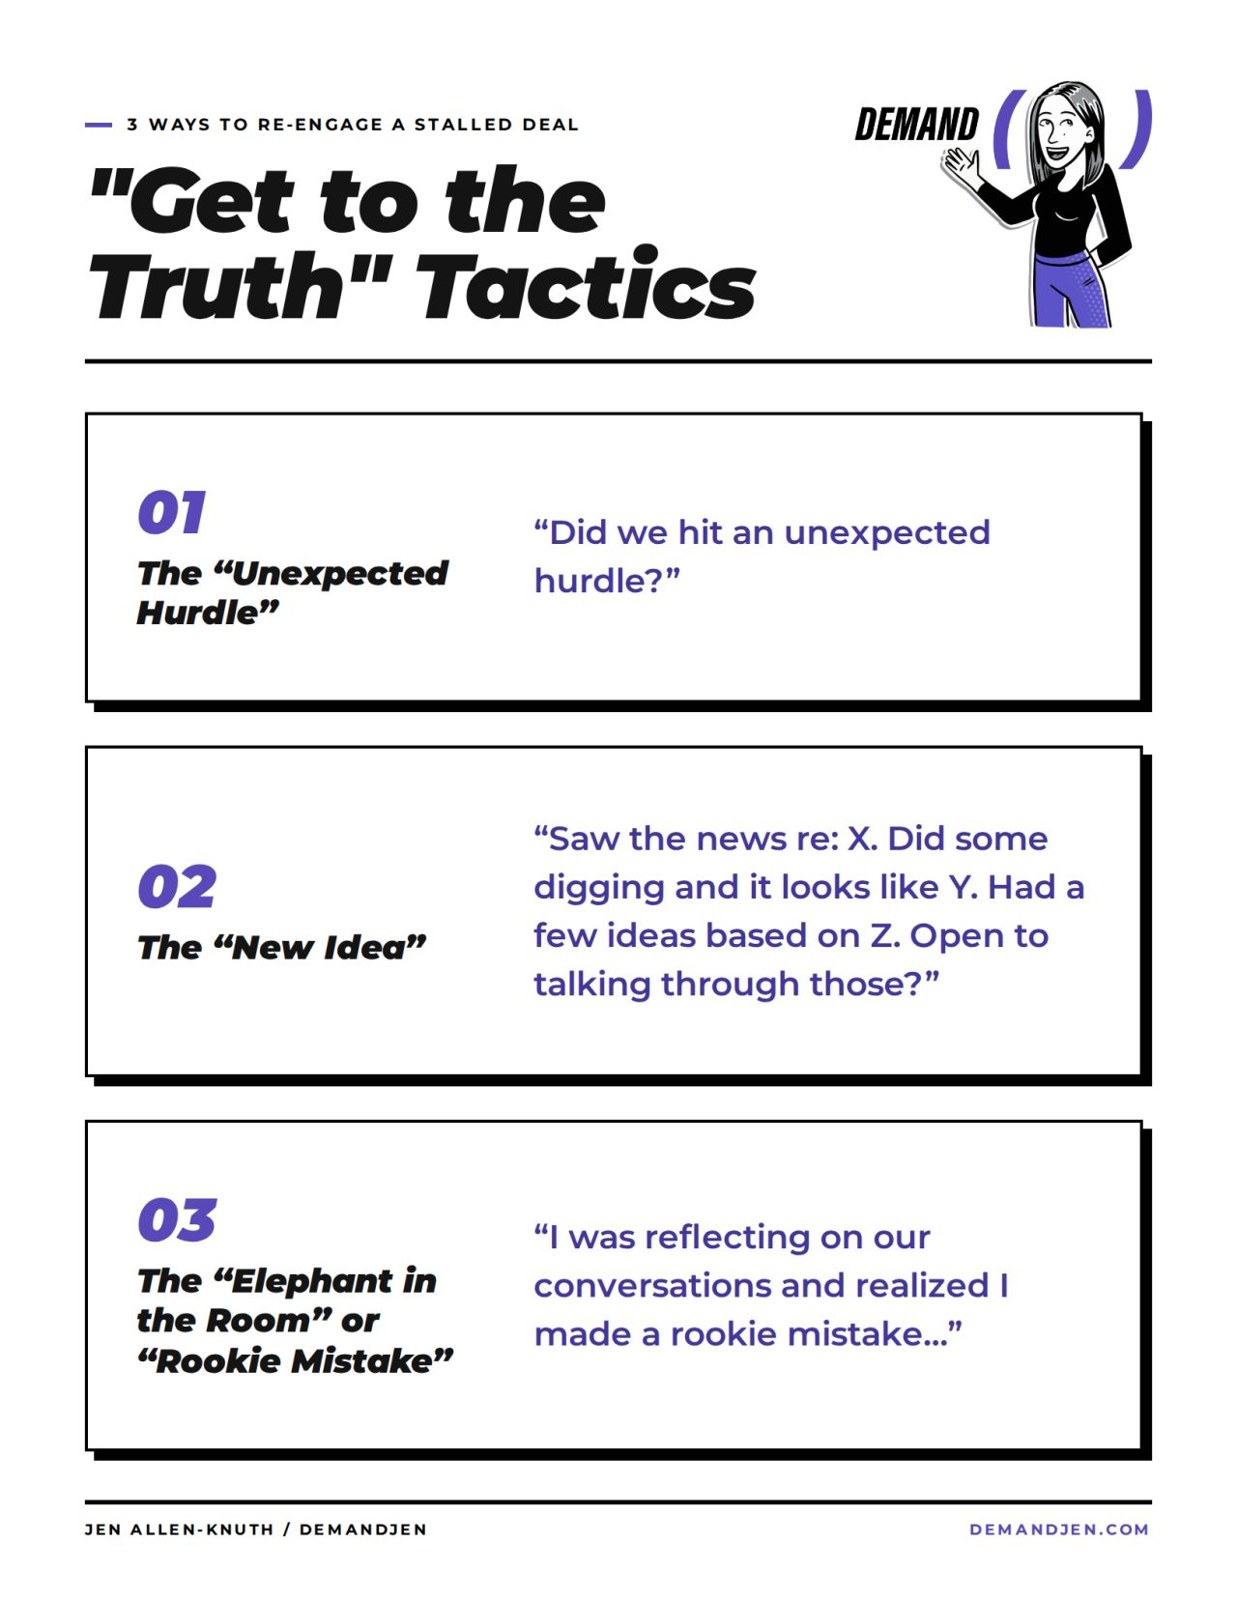
 Jen Allen-KnuthRecommends reviving stalled deals by inviting disclosure of roadblocks, introducing business-relevant ideas or acknowledging premature sales assumptions, depending on why conversations stopped.
 241 interactions · 2d agoTrending topicDreamforce+434% vs prior 30d · 3.9% of the conversationTrending topicHubSpot UNBOUND+329% vs prior 30d · 1.5% of the conversationTrending topicAI Safety+153% vs prior 30d · 2.1% of the conversationTrending topicFoundation Models+57.6% vs prior 30d · 10.8% of the conversation
 Cline↑7 places in Coding Agents & Harnesses for GTM
 Ploy↑5 places in AI-Native GTM Challengers
 TitanX↑27 places in AI-Native GTM Challengers
 Clearskies↑8 places in GTM Developer Tools
 OpenCode↑2 places in Coding Agents & Harnesses for GTM
Trending Topics
Market Moves
 41,256 engagements · 2.8× usualPost ↗F109 engagements · 10.4× usualPost ↗
 93 engagements · 0.9× usualPost ↗
 209 engagements · 1.4× usualPost ↗
 209 engagements · 1.4× usualPost ↗
 D261 engagements · 1.2× usualPost ↗1,637 engagements · 14.6× usualPost ↗
GTM Tech Index
Latest Posts
Sep 24My post-conference playbookHow to collect the conversation, find an angle, and build a unique audience. Lessons from Dreamforce and UNBOUND.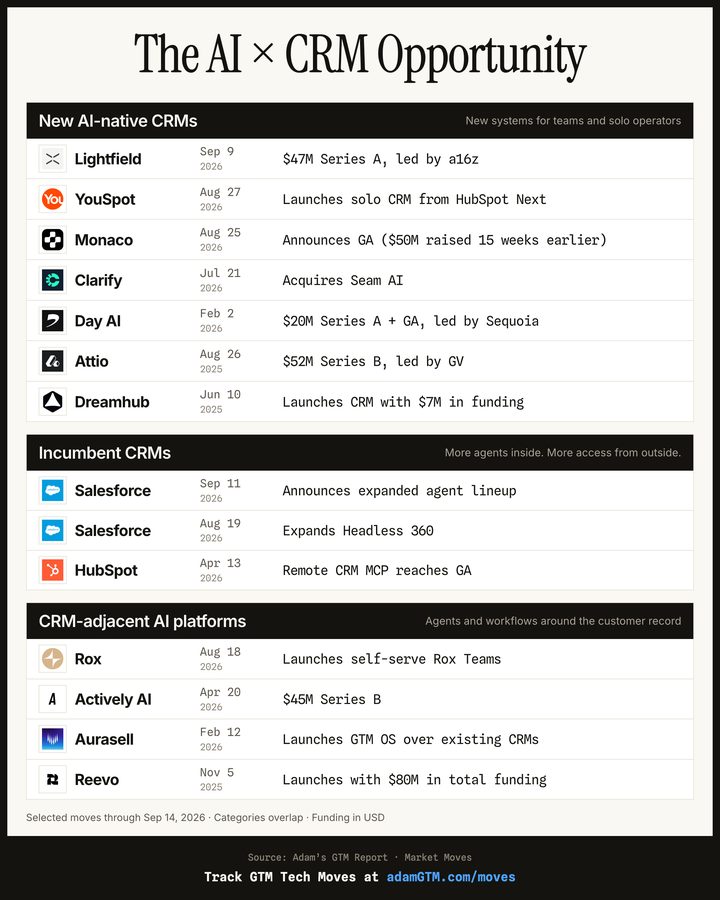 Sep 17CRM got interestingLightfield's $47M, AIforce, YouSpot, and the growing pie with headless CRMs + agents.
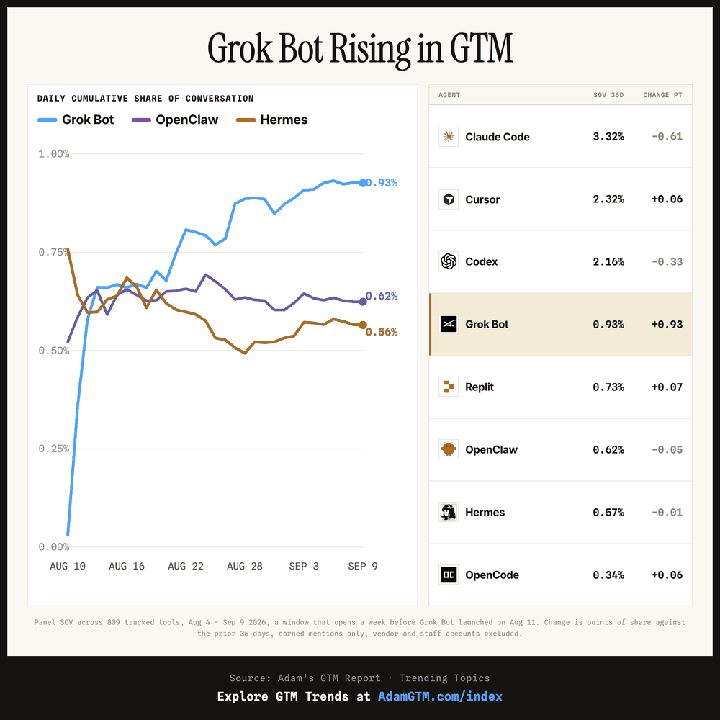 Sep 10Grok Bot or NotMy tests, the hype cycle, and why I'm not pivoting.
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
All topics
BetaFigures move as the panel grows and definitions sharpen.
>19×vs prior 30d+20.5%vs prior 30d-21.2%vs prior 30d-5.8%vs prior 30d+7.6%vs prior 30d-3.5%vs prior 30d +96.0%vs prior 30d+61.6%vs prior 30d-34.5%vs prior 30d+5.6%vs prior 30d+4.9%vs prior 30d+270%vs prior 30d+1.7%vs prior 30d-36.3%vs prior 30d+51.6%vs prior 30d-28.8%vs prior 30d
 -18.7%vs prior 30d+50.2%vs prior 30d-19.3%vs prior 30d+13.6%vs prior 30d
 +0.3%vs prior 30d-16.8%vs prior 30d
 -52.7%vs prior 30d-31.2%vs prior 30d-15.1%vs prior 30d+57.6%vs prior 30d-22.1%vs prior 30d
 -23.7%vs prior 30d-22.1%vs prior 30d-10.0%vs prior 30d-12.9%vs prior 30d
 -34.4%vs prior 30d-15.1%vs prior 30d
 +52.5%vs prior 30d-15.6%vs prior 30d-25.8%vs prior 30d+15.4%vs prior 30d+18.1%vs prior 30d+26.3%vs prior 30d+16.6%vs prior 30d-12.7%vs prior 30d
 +37.1%vs prior 30d-60.5%vs prior 30d
 -16.0%vs prior 30d+178%vs prior 30d-36.6%vs prior 30d
 -59.4%vs prior 30d+137%vs prior 30d+50.9%vs prior 30d
 ±0%vs prior 30d-17.7%vs prior 30d
 -11.2%vs prior 30d
 +32.3%vs prior 30d
 -40.9%vs prior 30d
 -36.9%vs prior 30d
 -48.8%vs prior 30d
 -13.3%vs prior 30d
 -38.8%vs prior 30d
 -52.8%vs prior 30d+247%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
Share climbed from February to an April peak near 27%, slid to about 21% by July and August, and fell another 11% over the last 30 days to about 19%. In February, Alan Zhao laid out the walls teams hit building agents on GTM data. Recent posts turn to single Claude skills and bets on world models for agents.
Posts to understand this · as of Sep 25
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | Grok Bot | 64 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 88 |
| 6 | Salesforce | 92 |
| 7 | HubSpot | 87 |
| 8 | Lovable | 58 |
| 9 | Replit | 55 |
| 10 | OpenClaw | 49 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO climbed from 9.2% in April to a 12.1% high in June, when vendors like HubSpot pitched AEO straight to brands. It has cooled since and is down 7% over the last 30 days. Later posts pull the topic back toward SEO, with Eli Schwartz quoting Google's John Mueller: there is no AEO or GEO without SEO fundamentals.
Posts to understand this · as of Sep 28
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 51 |
| 2 | Ahrefs | 50 |
| 3 | Semrush | 48 |
| 4 | HubSpot | 87 |
| 5 | Clay | 88 |
| 6 | Webflow | 48 |
| 7 | Claude Code | 99 |
| 8 | AirOps | 38 |
| 9 | Instantly | 61 |
| 10 | Codex | 83 |
How software exposes its data and actions so agents can use it directly.
Talk about agent interfaces more than doubled from February to April, reaching 9.1% of the conversation, and held at 9.4% in May, when Anthropic agreed to buy Stainless. Share eased to 7.3% by August, with ElevenLabs shipping an MCP for Claude mid-month. It is up 16% over the last 30 days, to about 8.1%, with Templafy pitching a free MCP.
Posts to understand this · as of Sep 25
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Clay | 88 |
| 4 | Codex | 83 |
| 5 | HubSpot | 87 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Grok Bot | 64 |
| 8 | Instantly | 61 |
| 9 | Lovable | 58 |
| 10 | Nooks | 48 |
The people, tools and operating model behind custom go-to-market systems.
GTM Engineering climbed steadily from February to a May high near 10%, then eased to about 7% by August. It is down 10% over the last 30 days, even as Clay shipped a CLI in July and raised $115M at a $7.1B valuation in September. Unify now pitches GTM engineer powers to every rep through chat.
Posts to understand this · as of Sep 27
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Codex | 83 |
| 5 | Prospeo | 51 |
| 6 | Instantly | 61 |
| 7 | Salesforce | 92 |
| 8 | Nooks | 48 |
| 9 |  FullEnrich | 42 |
| 10 | Cursor (Anysphere) | 78 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click held between 7.8% and 9.4% of the conversation from February through July, peaking in May. It fell to 6.8% in August and is still slipping, down 7.7% over the last 30 days. The August posts that did land were practical: a B2B playbook, AI answers that favor established brands, and a shrug at falling Reddit citations.
Posts to understand this · as of Sep 29
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 51 |
| 2 | Ahrefs | 50 |
| 3 | Semrush | 48 |
| 4 | HubSpot | 87 |
| 5 | Clay | 88 |
| 6 | Webflow | 48 |
| 7 | Claude Code | 99 |
| 8 | AirOps | 38 |
| 9 | Instantly | 61 |
| 10 | Lovable | 58 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Open versus closed models climbed for five months to an 8.6% high in July. That month, Jensen Huang shared an NVIDIA letter on why open models matter and Anthropic published its views on open weights. The share has cooled since and is down 37% over 30 days, though Mistral's €3 billion Series D kept the open side in the news.
Posts to understand this · as of Sep 24
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | OpenRouter | 51 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Baseten | 46 |
| 7 | Vercel | 59 |
| 8 |  Together AI | 32 |
| 9 | Grok Bot | 64 |
| 10 | Lovable | 58 |
How companies prove AI delivers enough value to move beyond a pilot.
Proving AI ROI held between 6% and 8% of the conversation from February through July, then slipped in August. The last 30 days are down 33%. What remains is vendors selling a way out of pilot mode, like OpenAI's Fabletics advice and Workato's control plane at WOW 2026, while Morgan J Ingram asks what reps will actually do with the time AI frees up.
Posts to understand this · as of Sep 24
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Codex | 83 |
| 4 | HubSpot | 87 |
| 5 | OpenRouter | 51 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | OpenClaw | 49 |
| 8 | Clay | 88 |
| 9 | Cline | 27 |
| 10 | Grok Bot | 64 |
How large companies move AI from small pilots into secure, useful production work.
Enterprise AI Adoption peaked at 7.2% in April and held near 6.6% through June. It then slid to 5.3% in August and is down another 14% over the last 30 days. The posts that still land are about accountability: who approves AI decisions, who owns the risk, and whether anyone can spell out the process being automated.
Posts to understand this · as of Sep 28
 inRisk frameworkEC-Council's adopt, defend, govern roadmap, framed by the Replit agent that deleted SaaStr's databaseCH
 inAccountability gapCEOs expect AI to make 48% of operational decisions by 2030. Who is accountable?LR
 inProcess realityThe slowest part of an AI project is mapping the process first
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Codex | 83 |
| 6 | Grok Bot | 64 |
| 7 | Clay | 88 |
| 8 | Lovable | 58 |
| 9 | OpenClaw | 49 |
| 10 | Midjourney | 36 |
How teams use buyer signals to decide who to target, when and why.
Signal-based selling has slid most months since February, from 7.8% to 4.1% in August, and the last 30 days are flat. Apollo's March acquisition of Pocus was the big early deal. Since then, signals read more like plumbing than a category: Clay and Claude Code make ABM possible for lean teams, and Dreamdata pushes Orb's account signals into ads, CRM and Clay.
Posts to understand this · as of Sep 25
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 92 |
| 5 | Instantly | 61 |
| 6 | Nooks | 48 |
| 7 | Codex | 83 |
| 8 | HeyReach | 51 |
| 9 | Apollo.io | 52 |
| 10 | Prospeo | 51 |
How teams create, distribute and judge marketing content made with AI.
AI Content has stayed in a narrow band all year, between 4.3% and 5.1%. The last 30 days are down 22%, but the 90-day line is nearly flat, so this looks like a dip, not a break. Recent posts are about distribution inside chat tools: Higgsfield as a ChatGPT plugin and Templafy's MCP for branded slides.
Posts to understand this · as of Sep 28
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Runway | 35 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Higgsfield | 38 |
| 5 | Salesforce | 92 |
| 6 | Clay | 88 |
| 7 | Lovable | 58 |
| 8 | Codex | 83 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Grok Bot | 64 |
How companies keep agents secure, accountable and under control as they take on real work.
Agent governance rose steadily from about 3% of the conversation in February to 6.5% in July, then fell in August. It is down 41% over the last 30 days. The September posts that remain are practical: whose credentials an agent uses, what an agent run costs, and how to catch failures that passing evals miss.
Posts to understand this · as of Sep 25
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | HubSpot | 87 |
| 6 | Vercel | 59 |
| 7 | Grok Bot | 64 |
| 8 | OpenRouter | 51 |
| 9 | LangChain | 46 |
| 10 | Cline | 27 |
How AI changes what software companies build, charge for and deliver.
Share has fallen by more than half since February, from 6.3% to about 2.9%, with one bounce in May. Spring posts were about new models: Intercom doubling down on its help desk next to Fin, and Daydream raising $15M for an AI-native agency. Salesforce's strong August quarter pushed back with numbers, and the last 30 days are flat.
Posts to understand this · as of Sep 29
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Clay | 88 |
| 5 | Codex | 83 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Lovable | 58 |
| 8 | ZoomInfo | 49 |
| 9 | Nooks | 48 |
| 10 | Replit | 55 |
How companies build trust and stand out when AI makes content cheap and abundant.
August lifted this to 3.7% on a fight over AI writing: Ann Handley on slop buttons and humanizer tools, and Clay publishing its internal AI writing policy. The last 30 days are down 35.5%. September's thread is narrower, with Ethan Smith and Gaetano Dinardi arguing that mass AI pages rank and then tank.
Posts to understand this · as of Sep 29
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 88 |
| 3 | HubSpot | 87 |
| 4 | Salesforce | 92 |
| 5 |  Clarify | 29 |
| 6 | Lovable | 58 |
| 7 | Nooks | 48 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Ahrefs | 50 |
| 10 |  Attention | 29 |
How AI changes software pricing, usage costs and gross margins.
A steady climb from March to a June high of 4.7%, then a drop through August, with the last 30 days down 32.6%. August posts framed the cost question: Peter Walker on token volume and cheap open-weight models, May Habib on enterprises reaching a spending ceiling. September news is narrower, like Factory's router cutting inference costs 63%.
Posts to understand this · as of Sep 29
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Codex | 83 |
| 4 | Claude Code | 99 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | OpenRouter | 51 |
| 7 | Vercel | 59 |
| 8 | Clay | 88 |
| 9 | Replit | 55 |
| 10 | Lovable | 58 |
How teams track and control the cost of models, tokens and agent work.
Token Spend more than doubled from February to 3.6% in July. Rippling launched an AI Spend Console in August, and Peter Walker showed most agent tokens are cached re-reads. The last 30 days are down 37%, though Harvey's swing from 50% to -50% gross margin gave the topic its sharpest number yet.
Posts to understand this · as of Sep 25
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | OpenRouter | 51 |
| 5 | Vercel | 59 |
| 6 | Cline | 27 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | LangChain | 46 |
| 9 | Baseten | 46 |
| 10 | Clay | 88 |
How people and agents share work, hand off tasks and make decisions together.
After a May high of 3.0%, share has held near 2.1% since July. The flat line hides steady product news: SpaceXAI launched Grok Bot as an AI teammate in August, team bots followed in late September, and Asana now includes AI teammates for every paid customer. The launches keep coming while share holds steady.
Posts to understand this · as of Sep 29
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | HubSpot | 87 |
| 4 | Salesforce | 92 |
| 5 |  Viktor | 32 |
| 6 | Clay | 88 |
| 7 | Grok Bot | 64 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Granola | 48 |
| 10 | Lovable | 58 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal agents fell from 1.35% of the conversation in February to about 0.65% by midsummer. Their share then nearly doubled in the last 30 days, as Instinct and Muse, two fast-growing personal assistants, came up across GTM conversations along with agents that shop for people. September is not over, so it is not yet a new high.
Posts to understand this · as of Sep 28
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 64 |
| 2 | OpenClaw | 49 |
| 3 | Codex | 83 |
| 4 | HubSpot | 87 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Claude Code | 99 |
| 7 | Midjourney | 36 |
| 8 | Vercel | 59 |
| 9 | Lovable | 58 |
| 10 | ElevenLabs | 52 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context engineering rose steadily from February to a June high of 2.9%. That month, Databricks put a "context layer" in its keynote and Charlie Hills called prompt engineering a 2024 habit. The share slid through July and August and is down 34% over the last 30 days, even as cognee passed 30,000 GitHub stars for agent memory.
Posts to understand this · as of Sep 24
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | Codex | 83 |
| 4 | HubSpot | 87 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Clay | 88 |
| 7 | Grok Bot | 64 |
| 8 |  Sumble | 32 |
| 9 | Profound | 51 |
| 10 | Gong | 63 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
Human Experience share hovered between about 2.1% and 3.2% from February through August, peaking in March and dipping to its low in April. In the last 30 days it fell 39% to about 1.6%, the lowest point on the chart. April posts mocked AI-made authenticity and pushed people over company pages, and a September post argues phone creators now out-influence studios.
Posts to understand this · as of Sep 28
 inCliché roundupMarketer cliché list mocks 'we need humanity' next to an AI avatar spokespersonSM
 inPeople over pagesSays 64% of buyers trust thought leadership over company content; company pages become storefrontsSF
 inCreator reachSelfie-camera TikTokers beat Hollywood, and a creator with a phone can out-influence marketing teams
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Nooks | 48 |
| 5 | Lovable | 58 |
| 6 | Salesforce | 92 |
| 7 | Ahrefs | 50 |
| 8 | Clarify | 29 |
| 9 | Attention | 29 |
| 10 | Clearskies | 21 |
Growth driven by people using the product before they talk to sales.
Product-Led Growth fell by more than half, from 3.4% in February to 1.2% in July, and has stayed near that floor since. No single event drove the slide. The recent posts are practical: Casey Hill on PostHog telling visitors 97% of customers pay nothing, and Leadfeeder hiring to support thousands of small accounts.
Posts to understand this · as of Sep 28
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Lovable | 58 |
| 4 | Clay | 88 |
| 5 | Replit | 55 |
| 6 | Canva | 49 |
| 7 | Ahrefs | 50 |
| 8 | Cursor (Anysphere) | 78 |
| 9 |  Docusign | 36 |
| 10 | Nooks | 48 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR share climbed from 2.2% in February to 3.2% in March, then held near 3% through May while Ava 2.0 launched at $250 a month and Sara McNamara warned that dirty CRM data breaks agents. Share then fell by more than half, to 1.4% in July. It bounced in August and is down 22% over the last 30 days, with ElevenLabs describing its own AI SDR on inbound.
Posts to understand this · as of Sep 28
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | Claude Code | 99 |
| 4 | Lovable | 58 |
| 5 | HubSpot | 87 |
| 6 | Nooks | 48 |
| 7 | ZoomInfo | 49 |
| 8 | n8n | 59 |
| 9 | Codex | 83 |
| 10 | Cursor (Anysphere) | 78 |
The argument that agents and custom software will break the classic SaaS model.
The debate has shrunk by nearly two thirds since February, and recent voices mostly argue against it. Benioff cited near-record low attrition at Salesforce, and Tyler Denk listed the SaaS tools beehiiv still pays for while HubSpot stock sits about 55% off its high. The last 30 days tick up 7.7%, from a low base.
Posts to understand this · as of Sep 29
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 88 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 49 |
| 6 | Clarify | 29 |
| 7 | Codex | 83 |
| 8 | Nooks | 48 |
| 9 | Attio | 51 |
| 10 | Sumble | 32 |
Low-quality AI content and the fight to make automated work worth reading.
After a March dip, slop held near 2% through August, when Ann Handley called out slop buttons and humanizer tools. The last 30 days are down 32%. The September tone is quieter: Kamil Rextin admitting his agency shipped workslop, and Scott Brinker telling marketers to be the counterweight to AI sameness.
Posts to understand this · as of Sep 29
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Claude Code | 99 |
| 3 | Clay | 88 |
| 4 | Salesforce | 92 |
| 5 | Clarify | 29 |
| 6 | Codex | 83 |
| 7 | Canva | 49 |
| 8 | Cursor (Anysphere) | 78 |
| 9 |  Docket | 30 |
| 10 | Higgsfield | 38 |
The choice between building software internally and buying another product.
Share fell by more than half from February to a July low, then settled near 1%. Late-September posts show the question moving into daily work: Maja Voje's survey finds sub-$1M startups building their own tooling with Claude Code, Ahrefs doubled API and MCP limits for builders, and Chris Orlob coaches reps on the "we can just build this with Claude" objection.
Posts to understand this · as of Sep 29
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Clay | 88 |
| 5 | ZoomInfo | 49 |
| 6 | Clarify | 29 |
| 7 | Codex | 83 |
| 8 | Nooks | 48 |
| 9 | Apify | 52 |
| 10 | Attention | 29 |
Ways to verify whether digital content or online activity came from a person or AI.
Proof of Human stayed under half a percent until August, when it nearly tripled to 1.1%. Anthropic's watermarking FAQ, tied to EU AI Act compliance, set it off, and Synthesia followed on Article 50 and California's AI Transparency Act. The last 30 days are down 72%, so this looks like a compliance moment, not a new baseline.
Posts to understand this
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Runway | 35 |
| 4 | Clay | 88 |
| 5 |  HeyGen | 31 |
| 6 | Higgsfield | 38 |
| 7 | HubSpot | 87 |
| 8 | Lovable | 58 |
| 9 | Salesforce | 92 |
| 10 | Substack | 53 |
AI tools that write, edit, test and operate software alongside a human builder.
Coding agents peaked in March at 21% of the conversation and have eased since, down 24% over 90 days. Early posts were builders sharing tools, like ColdIQ's Claude Code ad skills. Later ones were platform and money news: Notion as code in July, and Cursor's founders after SpaceX's $60 billion acquisition in August. The last 30 days are down 14%.
Posts to understand this · as of Sep 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 64 |
| 5 | Clay | 88 |
| 6 | Lovable | 58 |
| 7 | HubSpot | 87 |
| 8 | Replit | 55 |
| 9 | Salesforce | 92 |
| 10 | OpenClaw | 49 |
The frontier models and labs that provide the base layer for AI products.
Foundation Models jumped in April, when Anthropic launched Project Glasswing around Claude Mythos Preview with partners including AWS, Apple, Google and Microsoft. Share climbed to 11% in July, dipped in August, and is up 52% over the last 30 days. September talk leans toward OpenAI, which took a record 31% of OpenRouter spend in 48 hours.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 64 |
| 5 | HubSpot | 87 |
| 6 | OpenClaw | 49 |
| 7 | Midjourney | 36 |
| 8 | OpenRouter | 51 |
| 9 | Salesforce | 92 |
| 10 | Vercel | 59 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP more than doubled its share from February to May, then settled near 6% and has held there. A steady run of vendor launches keeps it level: ElevenLabs shipped an MCP server in Claude, Neo4j built a hosted server into Aura, and Databox launched MCP connectors. The last 30 days are up 3.3%.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | HubSpot | 87 |
| 4 | Clay | 88 |
| 5 | Codex | 83 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Instantly | 61 |
| 8 | Grok Bot | 64 |
| 9 | Nooks | 48 |
| 10 | FullEnrich | 42 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO climbed to its high in May, a month after HubSpot launched its AEO tool with claims that AI-sourced leads convert up to 3x better. Share held above 7% through July, then fell to 5.7% in August and is still slipping over the last 30 days. The August talk turned sober: Wil Reynolds argued challengers can't hack their way into a settled pool of four or five brands.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 51 |
| 2 | Ahrefs | 50 |
| 3 | Semrush | 48 |
| 4 | HubSpot | 87 |
| 5 | Clay | 88 |
| 6 | Webflow | 48 |
| 7 | AirOps | 38 |
| 8 | Claude Code | 99 |
| 9 | Instantly | 61 |
| 10 | Codex | 83 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce barely registered until a small August lift, then rose more than sixfold over the last 30 days around the mid-September event. Informatica's debut as part of the Salesforce family and Crossbeam's AgentExchange launch-partner news led the posts, while Tom Wentworth questioned whether the trip is real work.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Apify | 52 |
| 4 | Codex | 83 |
| 5 | Outreach | 46 |
| 6 | 1mind | 37 |
| 7 | Claude Code | 99 |
| 8 | ZoomInfo | 49 |
| 9 | Clay | 88 |
| 10 | Cursor (Anysphere) | 78 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
AI for the Enterprise peaked in April, the month Mistral released Workflows to move enterprise AI from prototype to production. It has drifted down since and is off 9% over the last 30 days. The current talk is about the value gap: Dario Amodei told Dreamforce companies capture only 5 to 10% of what AI offers, and BCG puts 70% of success in people and process.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | HubSpot | 87 |
| 5 | OpenClaw | 49 |
| 6 | ElevenLabs | 52 |
| 7 | Lovable | 58 |
| 8 | OpenRouter | 51 |
| 9 | Attio | 51 |
| 10 | Docusign | 36 |
Email sent to people with no prior relationship to start a sales conversation.
Cold email climbed from about 3% of the conversation in February to a 5.5% high in May, then settled back near 3% by July. The May high carried a tactics fight, like Jason Bay's claim that one-off inbox sends beat his sequencer by 15x. Since then the share is flat, and the talk has shifted to what makes personalization relevant.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Instantly | 61 |
| 2 | Claude Code | 99 |
| 3 | Clay | 88 |
| 4 | Prospeo | 51 |
| 5 | HubSpot | 87 |
| 6 | Lemlist | 48 |
| 7 | Apollo.io | 52 |
| 8 | Codex | 83 |
| 9 | Nooks | 48 |
| 10 | Apify | 52 |
Measuring whether AI answers mention, cite and recommend a brand.
AI visibility climbed to a June peak above 4% share and held near 3.6% through August. The last 30 days are down 22%, but the posts have turned practical. Corey Haines runs weekly press releases built for AI citation, Ahrefs pitches instant client reports from Brand Radar, and Forrester published a report on turning AEO into brand growth.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | Profound | 51 |
| 3 | Ahrefs | 50 |
| 4 | HubSpot | 87 |
| 5 | Claude Code | 99 |
| 6 | Docket | 30 |
| 7 | Peec AI | 28 |
| 8 |  Vector | 38 |
| 9 | AirOps | 38 |
| 10 |  AthenaHQ | 19 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps is still a big topic, but its share fell every month from March to August, down about 40%. The last 30 days are flat. The posts suggest the work is being renamed: Janis Zech sees marketing ops merging with GTM engineering, and Darrell Alfonso's future ops team includes an AI engineer and an AgentOps manager.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 88 |
| 4 | Claude Code | 99 |
| 5 | Attio | 51 |
| 6 | Gong | 63 |
| 7 | Instantly | 61 |
| 8 | HeyReach | 51 |
| 9 | n8n | 59 |
| 10 | Codex | 83 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer Success has lost more than half its share since February, with only a small bump in August. The posts show the work being absorbed elsewhere. Rox pitches agents that run renewals and expansion, Vanta puts account management under its sales leader, and Salesforce says Agentforce resolves 80% of Fisher & Paykel's online queries. The last 30 days fell 26.5%.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 88 |
| 4 | Claude Code | 99 |
| 5 |  Salesloft | 41 |
| 6 |  Twilio | 41 |
| 7 | Attio | 51 |
| 8 | Lovable | 58 |
| 9 | Nooks | 48 |
| 10 | Replit | 55 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Prospecting has slid slowly since May, from about 4.2% of the conversation to under 3% by summer, and the last 30 days are down another 13.5%. No single event did it. Launches keep coming, from YC-backed Origami in April to Clay's rebuilt sequencer and API in September, but they pitch prospecting as a job an agent does inside a workflow.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 88 |
| 3 | Salesforce | 92 |
| 4 | HubSpot | 87 |
| 5 |  AI Ark | 44 |
| 6 | Instantly | 61 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Grok Bot | 64 |
| 9 | Prospeo | 51 |
| 10 | Apollo.io | 52 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand gen has slid from its March high, down 23% over 90 days and 15% over the last 30. The posts question the model itself. Dave Gerhardt says AI lets buyers skip the PDF and the sales call, Joe Chernov says founders no longer hire demand gen first, and Brigitta Ruha shows how form fills train Meta to find junk leads.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Clay | 88 |
| 3 | Salesforce | 92 |
| 4 | Claude Code | 99 |
| 5 | Docket | 30 |
| 6 | RB2B | 47 |
| 7 | Vector | 38 |
| 8 | Instantly | 61 |
| 9 | Webflow | 48 |
| 10 | Nooks | 48 |
Voice and chat software that talks with buyers and customers.
Conversational AI climbed steadily from 1.4% in April to 2.1% in August and is up 26% over 90 days. Voice agents moving into real deployments keep it there. In early September, OpenAI put gpt-live-1 in its API, ElevenLabs partnered with Genesys, and Sierra announced a voice agent for Philippine Airlines. The last 30 days are level.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Claude Code | 99 |
| 4 | ElevenLabs | 52 |
| 5 | Vector | 38 |
| 6 | Docket | 30 |
| 7 | Instantly | 61 |
| 8 |  Cartesia | 29 |
| 9 | Codex | 83 |
| 10 | Cursor (Anysphere) | 78 |
The debate over AI risk, alignment, regulation and responsible development.
AI Safety held at about 0.6% to 1% of the conversation from February through August. Over the last 30 days its share rose 155% to about 2.1%. The selected posts, from Sept. 14 to 18, respond to fresh AI risk concerns, but none names the trigger, so it remains unidentified.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 64 |
| 4 | beehiiv | 49 |
| 5 | Salesforce | 92 |
| 6 | Substack | 53 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | OpenClaw | 49 |
| 9 | ElevenLabs | 52 |
| 10 |  Frontier | 24 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid Media peaked at 2.7% of the conversation in February, dropped to 1.8% in April, held near 2.1% through July and rose to 2.5% in August. Over the last 30 days its share fell 18%, to about 2%. September posts weighed search against LinkedIn, while Jeff Green's Zuma launch landed in the last days of August.
Posts to understand this · as of Sep 23
 inLate-August launchZuma, the newest Kokai version, launched August 27 with AI-driven ad optimizationsGR
 inSearch costsNon-branded Google search CPCs up almost 30%, click-through rates down over 25% year over yearPD
 inChannel returnsReport on $150M+ LinkedIn ad spend finds 1.6x return versus Google's 1.18x
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Clay | 88 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 61 |
| 5 | HeyReach | 51 |
| 6 | Nooks | 48 |
| 7 | Ahrefs | 50 |
| 8 | Apollo.io | 52 |
| 9 |  Fibbler | 35 |
| 10 | Granola | 48 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold Outbound held near 3% through May, then slid every month to 2.4% in August. No single event caused it. The last 30 days are down 15.5%. The posts that still land are about systems: Rippling's 150-SDR build, 11x's voice agents and Clay's four-agent prospecting workflow.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Claude Code | 99 |
| 3 | Instantly | 61 |
| 4 | Nooks | 48 |
| 5 | HubSpot | 87 |
| 6 | Prospeo | 51 |
| 7 | HeyReach | 51 |
| 8 | Apollo.io | 52 |
| 9 | FullEnrich | 42 |
| 10 | Gong | 63 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Evals rose five months straight, from 0.8% in February to a 3.0% peak in July. The April jump lines up with model launch posts like Lovable's GPT-5.5 eval results. Share has cooled since, down 24% over 30 days but still up 16.5% over 90, with Vercel and Mercor treating evals as production tooling.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 92 |
| 5 | LangChain | 46 |
| 6 | HubSpot | 87 |
| 7 | Vercel | 59 |
| 8 | Cline | 27 |
| 9 | OpenRouter | 51 |
| 10 | Grok Bot | 64 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
AI video's share has been choppy, swinging between 1.3% and 1.8% from February to July. It rose to 2.0% in August and has held about flat at 2.0% so far in September. Late-summer posts span live generation from fal, HeyGen's 30-minute avatars and Higgsfield's free filmmaking academy.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Runway | 35 |
| 2 | Higgsfield | 38 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 92 |
| 5 | HubSpot | 87 |
| 6 | Codex | 83 |
| 7 | Lovable | 58 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Grok Bot | 64 |
| 10 | HeyGen | 31 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
Data infrastructure has lost about 60% of its February share, with a brief bump in June. The talk has moved from platforms to access: Pocus folding into Apollo in March, then Salesforce's Headless 360 connector for Claude and Informa TechTarget's MCP server for intent data. The last 30 days are down 8%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 88 |
| 4 | Claude Code | 99 |
| 5 |  GrowthLoop | 29 |
| 6 | Gong | 63 |
| 7 | Twilio | 41 |
| 8 | Attio | 51 |
| 9 | Nooks | 48 |
| 10 | n8n | 59 |
Sales and marketing coordinating around a defined set of target accounts.
ABM lost almost half its share between February and April, then settled near 2% and slid lower. The last 30 days are down 10%, even with Vector's September 16 launch pitching contact-level signals against legacy ABM platforms. Much of the remaining talk treats ABM as a strategy choice, like Dan Rosenthal weighing it against PLG.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Claude Code | 99 |
| 3 | Clay | 88 |
| 4 | Instantly | 61 |
| 5 | Nooks | 48 |
| 6 | Salesforce | 92 |
| 7 | Codex | 83 |
| 8 | HeyReach | 51 |
| 9 |  6sense | 40 |
| 10 | Apollo.io | 52 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Data Enrichment held between about 2.9% and 3.8% of the conversation from February through June, then fell hardest in July, to about 2%. It kept sliding through August and is down 11% over the last 30 days. The September posts in view put enrichment inside coding agents like Claude and Cursor, or pitch cheaper data against Clay.
Posts to understand this
 inAgent launchClay launches its API and CLI so coding agents can find and enrich prospectsNM
 inChallenger pitchNathan Merzvinskis pitches cheaper data and a simpler product against Clay's action creditsHS
 inIn the editorHenry Schuck puts ZoomInfo data enrichment inside Cursor through gtm.ai, with free credits
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Instantly | 61 |
| 5 | Prospeo | 51 |
| 6 | HeyReach | 51 |
| 7 | Salesforce | 92 |
| 8 |  Findymail | 40 |
| 9 | n8n | 59 |
| 10 | AI Ark | 44 |
The training, fine-tuning and modeling work underneath AI products.
Machine Learning sat between 0.97% and 1.30% through June, then rose to 1.45% in August. The last 30 days are up 9%. Robotics and world models lead the recent talk: Skild AI's S1 robot model, Black Forest Labs' open Flux 3 Action and World Labs joining AMD.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | LangChain | 46 |
| 5 | Salesforce | 92 |
| 6 | Baseten | 46 |
| 7 | OpenClaw | 49 |
| 8 | OpenRouter | 51 |
| 9 | Vercel | 59 |
| 10 | Cline | 27 |
Mapping and winning the committee of people involved in a business purchase.
Buying groups is a large, steady topic that has slowly given back share since March and held flat over the last 30 days. The plateau is practical talk: Dreamdata's research putting the average committee at 10 people, Becca Lindquist's Slack channel for exec multithreading at Clay, and Anthony Pierri arguing homepages are read by the people executives delegate to.
Posts to understand this · as of Sep 27
 inSales practiceBecca Lindquist shares Clay's Slack channel for executive multithreading into accountsAP
 inMessaging critiqueAnthony Pierri says enterprise homepages are written for executives who don't read themAD
 inResearch dataAlice de Courcy cites Dreamdata: buying committees grew from 6.8 to 10 people
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | HubSpot | 87 |
| 4 | Claude Code | 99 |
| 5 | Gong | 63 |
| 6 | Vector | 38 |
| 7 | Apollo.io | 52 |
| 8 |  BuiltWith | 33 |
| 9 | Codex | 83 |
| 10 | Cursor (Anysphere) | 78 |
The work of connecting marketing activity to pipeline and revenue.
Attribution is a steady baseline that is slowly shrinking. Its share peaked in March, has eased most months since, and is down 14% over the last 30 days. No single event drives it. The live threads are AI answers breaking last-touch tracking, as Ethan Smith shows with n8n, and marketers like Adam Holmgren defending attribution as evidence, not credit.
Posts to understand this · as of Sep 26
 inPlaybookKieran Flanagan's modern B2B playbook puts data-model attribution inside paid advertisingES
 inCase studyn8n case study: self-reported attribution catches zero-click AI conversions last-touch missesAH
 inDefenseAdam Holmgren argues attribution should show correlation with pipeline, not claim credit
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 88 |
| 4 | Docket | 30 |
| 5 | Claude Code | 99 |
| 6 | GrowthLoop | 29 |
| 7 |  MoEngage | 22 |
| 8 | 6sense | 40 |
| 9 | Fibbler | 35 |
| 10 | Gong | 63 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
UNBOUND barely registered most of the year, then built in August ahead of the show. The last 30 days are up 412% as the Boston conference ran in mid-September. Yamini Rangan hosted 1,300 partners at Partner Day, Dave Gerhardt put the crowd near 13,000, and booth stories are still landing after the event.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 88 |
| 4 | Gamma | 43 |
| 5 | Claude Code | 99 |
| 6 | Vector | 38 |
| 7 | Apify | 52 |
| 8 |  Breeze | 21 |
| 9 | Codex | 83 |
| 10 | Profound | 51 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability peaked in May at 2.2% share, then eased and has sat between 1.4% and 1.8% since. The last 30 days are down 18.6%. September's visible posts teach the basics: an AMA on spam and sender reputation, a webinar on SPF, DKIM and DMARC, and conference talks on list decay.
Posts to understand this · as of Sep 28
 inSpam questionsCustomer.io deliverability lead hosts a Reddit AMA on spam, authentication and sender reputationSM
 inAuthentication basicsSinch Mailgun and Red Sift webinar on SPF, DKIM, DMARC and getting BIMI liveZ
 inList hygieneZeroBounce COO's UNBOUND talks on email list decay and validating contacts in HubSpot
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | HubSpot | 87 |
| 3 | Instantly | 61 |
| 4 | Claude Code | 99 |
| 5 | Prospeo | 51 |
| 6 | Grok Bot | 64 |
| 7 | Salesforce | 92 |
| 8 | Lemlist | 48 |
| 9 | ZoomInfo | 49 |
| 10 | Codex | 83 |
Programmable tools used to build custom go-to-market systems, agents and automations.
GTM Developer Tools tripled from February to a May peak as Claude Code became a GTM workbench, with posts like Eric Nowoslawski's free repo of 29 cold email skills. Share settled back through August but is up 13% over the last 30 days. Recent posts are stack tours, like Bill Stathopoulos running outbound for 100+ clients with 22 tools in one Claude window.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Prospeo | 51 |
| 2 | Clay | 88 |
| 3 | Instantly | 61 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 87 |
| 6 | FullEnrich | 42 |
| 7 | HeyReach | 51 |
| 8 | Apollo.io | 52 |
| 9 | Findymail | 40 |
| 10 | Lemlist | 48 |
People asking AI assistants for answers instead of using a traditional search engine.
Share climbed from an April low to a June peak, then fell through August. September is partial, and the last 30 days are down slightly. The recent posts are practical: Chris Donnelly on the clicks a top Google result loses under an AI Overview, Forrester on how answer engines shape shortlists, and Scrapingdog on zero-click searches.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | HubSpot | 87 |
| 3 | Profound | 51 |
| 4 | Ahrefs | 50 |
| 5 | Clarify | 29 |
| 6 | Claude Code | 99 |
| 7 | Clay | 88 |
| 8 | ElevenLabs | 52 |
| 9 | Gamma | 43 |
| 10 | Gong | 63 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product marketing lost more than a third of its share from March to April and has drifted lower since, down 17.8% over the last 30 days. No single event explains it. In April the conversation shifted toward marketing engineers, and much of what remains is PMMs defending their work or teaching it.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Profound | 51 |
| 4 | Gong | 63 |
| 5 | Lovable | 58 |
| 6 | HubSpot | 87 |
| 7 | Ahrefs | 50 |
| 8 | Codex | 83 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Semrush | 48 |
The choice of go-to-market motion and the plan for making it work.
GTM Strategy held between 2% and 3.3% of the conversation from February to May, then slid to 1.7% in August. It is still falling, down 28% over the last 30 days. Early in the year, Swan AI's all-agent motion drew big numbers, while recent posts ask who to hire to run a motion rather than which motion to pick.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | HubSpot | 87 |
| 6 | Lovable | 58 |
| 7 | Docusign | 36 |
| 8 | Nooks | 48 |
| 9 | Codex | 83 |
| 10 | Ahrefs | 50 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise sales has drifted down from 2.45% in March. August bounced to 1.65% when Bending Spoons agreed to buy Airtable for $1.285B, and Elena Verna read it as a PLG company pulled off course by enterprise ambitions. The last 30 days are down 26.6%, though Higgsfield's jump from $20M to $700M run rate keeps the consumer-to-enterprise story alive.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Salesforce | 92 |
| 3 | Clay | 88 |
| 4 | HubSpot | 87 |
| 5 | Lovable | 58 |
| 6 | Claude Code | 99 |
| 7 | Grok Bot | 64 |
| 8 | Replit | 55 |
| 9 | Attio | 51 |
| 10 | Codex | 83 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting has drifted down from 2.5% in February to about 1.2%, with one bump in May. The last 30 days are down 14%. What remains is mostly vendor positioning: Creatio comparing AI and rep forecasts, Salesloft folding forecasting into a predictive revenue system, and Lightfield pitching CRM as a business world model.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 88 |
| 4 | Claude Code | 99 |
| 5 |  Clari | 33 |
| 6 | Gong | 63 |
| 7 | Nooks | 48 |
| 8 | n8n | 59 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Grok Bot | 64 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing sat below 0.4% of the conversation through May, then more than doubled in June and passed 1% in July. It held near 1.1% in August, when OpenRouter joining Stripe was the biggest post and CodeRabbit argued model choice belongs inside the product. The last 30 days are down 8%, even as Harvey's margin numbers led Rob Litterst to call routing really important.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Salesforce | 92 |
| 5 | LangChain | 46 |
| 6 | OpenRouter | 51 |
| 7 | Cline | 27 |
| 8 | Vercel | 59 |
| 9 | beehiiv | 49 |
| 10 | Clay | 88 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales leadership held above 2% through May, stepped down in June and has drifted lower since, off 15% in the last 30 days. What's left is about people more than tools: hiring reps better than you, building an AI-native team at Campfire, and CROs asking whether AI lifts the best reps while pulling teams back to the sales floor.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Gong | 63 |
| 4 | Clay | 88 |
| 5 | Codex | 83 |
| 6 | MoEngage | 22 |
| 7 | Outreach | 46 |
| 8 | Replit | 55 |
| 9 | Salesloft | 41 |
| 10 | Twilio | 41 |
How companies create demand, build trust and reach buyers at other businesses.
B2B Marketing peaked in March at 2.6% and has lost a third of its share over 90 days, down 14.1% in the last 30. No single event explains the slide. Early in the year, posts like Devin Reed's made broad calls about the shift. The ones holding up now argue about specifics: Kieran Flanagan on channels, Matt Heinz on the MQL.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Claude Code | 99 |
| 3 |  Optimizely | 30 |
| 4 | Salesforce | 92 |
| 5 | Webflow | 48 |
| 6 |  CHEQ | 15 |
| 7 | Clay | 88 |
| 8 |  Meltwater | 25 |
| 9 |  Primer | 24 |
| 10 | ZoomInfo | 49 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Revenue agents peaked in April, when HockeyStack raised $50M for revenue agents and Eoghan McCabe opened Fin to sales roles. Share then fell by more than two thirds through August. The last 30 days are up 10%, helped by Yuriy Zaremba's Ami launch, pitched as a fix for AI SDRs that overpromised.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 88 |
| 3 | Salesforce | 92 |
| 4 | Nooks | 48 |
| 5 | Sumble | 32 |
| 6 | HubSpot | 87 |
| 7 | Codex | 83 |
| 8 |  Rox | 31 |
| 9 | ZoomInfo | 49 |
| 10 | Clarify | 29 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search Strategy share roughly doubled from 0.9% in April to a 1.9% June peak, then fell through July and August. Over the last 30 days it is down 16.6%. September posts weigh what organic search is worth: Ahrefs data on a 7.5% traffic drop, Similarweb counting AI Mode referrals as organic, and a case for buyer intent over traffic volume.
Posts to understand this · as of Sep 28
inIntent over volumeArgues B2B SEO chases top-of-funnel traffic while buyers search comparisons and migration pathsI XLost clicksShares Ahrefs finding that organic search traffic fell 7.5% across 75,000 websitesS
 XMeasurement changeRetweets note that Similarweb reclassified Google AI Mode referrals from gen AI to organic
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | Semrush | 48 |
| 3 | HubSpot | 87 |
| 4 |  SparkToro | 27 |
| 5 |  Composio | 29 |
| 6 | Granola | 48 |
| 7 | Instantly | 61 |
| 8 |  Similarweb | 32 |
| 9 | AirOps | 38 |
| 10 | Apify | 52 |
The durable knowledge and memory an agent can use across tasks and sessions.
Agent memory climbed to a June high, when Perplexity launched Brain and Databricks announced Genie Ontology within days of each other. It has cooled since, down 23% over the last 30 days. The talk has shifted from platform launches to personal setups, like Henry Hund routing local meeting transcripts into his own context layer.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Clay | 88 |
| 6 | Codex | 83 |
| 7 | Gong | 63 |
| 8 | Profound | 51 |
| 9 | Sumble | 32 |
| 10 | Attention | 29 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence share has roughly halved since February, apart from a July bump. Call analysis now shows up inside bigger platforms: Outreach and Zoom were each named leaders in revenue orchestration reports, and Momentum is powering the data foundation for Salesforce's new Hunter sales agent. The last 30 days are down 7%.
Posts to understand this
 inForrester WaveOutreach named a leader in Forrester's Q3 2026 revenue orchestration WaveZ
 inIDC MarketScapeZoom named a leader in IDC MarketScape for unified revenue orchestration platformsAW
 inSalesforce partnerMomentum powers the data foundation for Salesforce's Hunter agent, shown at Sales Cloud keynote
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Gong | 63 |
| 3 | HubSpot | 87 |
| 4 | Clay | 88 |
| 5 | Claude Code | 99 |
| 6 | Outreach | 46 |
| 7 | Grok Bot | 64 |
| 8 | Instantly | 61 |
| 9 | Salesloft | 41 |
| 10 | Ahrefs | 50 |
Starting and running a business, including the economics and experience of the founder path.
Entrepreneurship is a steady background topic, dipping in July and back to about 1% since. The last 30 days are up 19%, led by founder stories rather than funding news: Tally reaching $6M ARR bootstrapped with a team of 10, Peep Laja on his freelance start in Panama, and Debra Aho Williamson's solo research business.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | Clay | 88 |
| 4 | Lovable | 58 |
| 5 | Substack | 53 |
| 6 | Replit | 55 |
| 7 | Codex | 83 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | Grok Bot | 64 |
| 10 | HubSpot | 87 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
CLIs for GTM climbed from under 0.1% of the conversation in February to nearly 1% by May, before any of these posts. It peaked at 1.2% in July, the month Clay launched a CLI and API. Share has held near 1% since, with vendors like Rox pitching more CLI and less UI, and it is up slightly over the last 30 days.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Claude Code | 99 |
| 3 | Codex | 83 |
| 4 | Salesforce | 92 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | HubSpot | 87 |
| 7 | Grok Bot | 64 |
| 8 | Nooks | 48 |
| 9 | ZoomInfo | 49 |
| 10 | Apify | 52 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing held near 2% through June, then dropped to about 1.5% in July and August. The last 30 days are down another 33.4%. No single event explains it. The posts that break through argue the old playbook is breaking: LLMs answer the searches blogs used to win, and Kyle Lacy says the question is now whose voice is missing.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Clay | 88 |
| 4 | Ahrefs | 50 |
| 5 | HeyReach | 51 |
| 6 | Instantly | 61 |
| 7 | Profound | 51 |
| 8 | Semrush | 48 |
| 9 | Grok Bot | 64 |
| 10 | Nooks | 48 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Headless software jumped to 1.5% in April, then faded to 0.36% by July. The L30 share is up 65%, driven by mid-September launches. Salesforce pushed Headless 360 and AgentExchange at Dreamforce, Lovable and Gainsight announced builds on it, and Klaviyo said it went headless at K:BOS. Vendors now put the word in their own launch headlines.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | ZoomInfo | 49 |
| 4 | HubSpot | 87 |
| 5 | Claude Code | 99 |
| 6 | Apify | 52 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Clarify | 29 |
| 9 | Exa.ai | 45 |
| 10 | Nooks | 48 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth marketing peaked in March, lost more than half its share by April, and kept sliding into August. Bruno Estrella's April post named the argument: the future of growth marketing is GTM engineering. The last 30 days are up 30%, carried by Andrew Yan's case for experiment volume over hit rate and Davide Grieco hiring for Clay's growth team.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Webflow | 48 |
| 3 | Optimizely | 30 |
| 4 | Ahrefs | 50 |
| 5 | Claude Code | 99 |
| 6 | Profound | 51 |
| 7 | AirOps | 38 |
| 8 |  Metronome | 24 |
| 9 | Semrush | 48 |
| 10 | Cursor (Anysphere) | 78 |
How companies sell to other companies and how business buyers make decisions.
B2B sales talk swings month to month, between 0.9% and 1.4% share, with no single event behind it. The steady theme is the buyer. Gal Aga argues AI now does the summarizing a rep used to do, and Morgan J Ingram says AI slop is pushing buyers back toward sellers they trust. The last 30 days are down 37%.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 88 |
| 4 |  AiSDR | 22 |
| 5 | Apify | 52 |
| 6 | Attio | 51 |
| 7 | Codex | 83 |
| 8 |  Cognism | 30 |
| 9 |  Consensus | 26 |
| 10 | FullEnrich | 42 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement talk was loudest in February, led by Gal Aga's playbook for displacing 11 enablement contracts worth over $100K each. It has slid since with small bumps, and the last 30 days are down 38%. Recent posts question the category: Sam Jacobs notes enablement spend rose about 7x while quota attainment fell from 60% to about 20%.
Posts to understand this · as of Sep 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Cursor (Anysphere) | 78 |
| 3 | Claude Code | 99 |
| 4 | Gong | 63 |
| 5 | HubSpot | 87 |
| 6 |  Winn.ai | 25 |
| 7 | Apollo.io | 52 |
| 8 |  CallRail | 22 |
| 9 | Clay | 88 |
| 10 |  Customer.io | 38 |
The software stack marketers use to plan, run, measure and improve their work.
Martech jumped in March when Scott Brinker published The new martech stack for the AI age with Databricks, and Jon Miller and Joe Chernov wrote responses. That level held through May, then fell back. The August bump coincided with Dreamforce agenda posts, including a Brinker session on the end of martech.
Posts to understand this · as of Sep 24
| Brand | GTM Index | |
|---|---|---|
| 1 | GrowthLoop | 29 |
| 2 | HubSpot | 87 |
| 3 | Salesforce | 92 |
| 4 | Twilio | 41 |
| 5 |  Augment Code | 17 |
| 6 | Claude Code | 99 |
| 7 | Codex | 83 |
| 8 | Clay | 88 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Customer.io | 38 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent Skills more than doubled from February to a May peak, when operators shared working playbooks: Michel Lieben's ad-management skills and Maja Voje and Kyle Poyar's Claude Code guide from 200 GTM operators. Share eased through the summer despite Vercel's August agent plugins standard, built with GitHub, Cursor and OpenAI. It is down 32% over the last 30 days.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Salesforce | 92 |
| 4 | Clay | 88 |
| 5 | Codex | 83 |
| 6 | Nooks | 48 |
| 7 | Optimizely | 30 |
| 8 | Instantly | 61 |
| 9 | Profound | 51 |
| 10 | Webflow | 48 |
How marketing teams use AI, where it helps and how it changes the job.
Share fell by nearly half from April to May and has sat in a flat band since. The last 30 days are unchanged. The spring posts argued about the job itself, like Marvin Chow's case for marketing engineers. The biggest recent post is Andy Mowat joining Inflection as CMO to build a base for marketing agents.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Profound | 51 |
| 3 |  Buffer | 26 |
| 4 | Claude Code | 99 |
| 5 | LangChain | 46 |
| 6 | Lovable | 58 |
| 7 | Salesforce | 92 |
| 8 |  Framer | 34 |
| 9 |  Adobe Marketo | 25 |
| 10 | Airtable | 48 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
The topic peaked in April and May, when Brian Halligan described AI-pilled CEOs running on recorded meetings and Stevie Case reported AI-native companies rebuilding classic GTM teams. Since June it has held near 0.8%. Elena Verna's August post, comparing an AI-native build at Lovable with an enterprise rollout, fits the later tone: comparing notes over bold claims.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | Clay | 88 |
| 5 | Codex | 83 |
| 6 | beehiiv | 49 |
| 7 |  AssemblyAI | 32 |
| 8 | ElevenLabs | 52 |
| 9 | Exa.ai | 45 |
| 10 | Rox | 31 |
Systems where several agents divide a job, coordinate their work and combine the result.
Multi-agent systems held near 1% share through June, then slid through July and August. The talk has moved from the idea to proof runs. Workato expanded Airo, its team of specialist agents, and Mercor ran more than 100 subagents for nearly five hours. Share is still falling, down 18% over the last 30 days.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | ElevenLabs | 52 |
| 4 | Grok Bot | 64 |
| 5 | LangChain | 46 |
| 6 | OpenClaw | 49 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Profound | 51 |
| 9 | Salesforce | 92 |
| 10 | Vercel | 59 |
The point where a product solves a real need for a market that will buy it.
Product-market fit has lost more than half its February share, bottoming in July and down 6% over the last 30 days. The idea still circulating is Elena Verna's line from Lenny Rachitsky's December interview: in AI, you re-find fit every three months. ClickUp now says every few weeks, and Andrew Chen asks whether deeptech breaks the revenue-first theory.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Lovable | 58 |
| 3 | Claude Code | 99 |
| 4 | Granola | 48 |
| 5 | HubSpot | 87 |
| 6 | Salesforce | 92 |
| 7 |  Bland | 19 |
| 8 |  Fireflies | 34 |
| 9 | HeyReach | 51 |
| 10 | Profound | 51 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing Automation lost more than half its share from February to June. It turned in July, when HubSpot launched Agent Hub and Agent Builder, and the recovery has held, up 11.3% over 90 days and 8% in the last 30. In September, Jon Miller, holding his 2006 Marketo shirt, argued the category never moved on and marketers want AI-native tools.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | GrowthLoop | 29 |
| 4 | Attio | 51 |
| 5 | Twilio | 41 |
| 6 |  ActiveCampaign | 31 |
| 7 | Clay | 88 |
| 8 |  DemandScience | 24 |
| 9 |  Gainsight | 27 |
| 10 | n8n | 59 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Partner Marketing jumped from almost nothing in February to a steady plateau from March to July, then hit its high in August. That month brought Moloco's agency partner program and Will Taylor's Catalyst26 takeaway that partner pipeline needs real demand generation. The last 30 days are down 21%, still above the spring level.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Clay | 88 |
| 3 | Salesforce | 92 |
| 4 | Lovable | 58 |
| 5 | Instantly | 61 |
| 6 | Replit | 55 |
| 7 | AI Ark | 44 |
| 8 | Apollo.io | 52 |
| 9 |  Aurasell | 18 |
| 10 |  Chili Piper | 36 |
Teams building internal software with AI instead of buying another SaaS product.
Share sat near 1% through April, dropped to a June low, and has held around 0.6 to 0.7% since. The last 30 days are up 10.6%, and the new posts push back on the trend: Sara McNamara on RevOps teams rebuilding an $18-a-month Granola, and Manisha Raisinghani on the upkeep that follows a homemade RFP bot.
Posts to understand this · as of Sep 29
 inOpportunity costSara McNamara questions RevOps teams vibe coding replacements for cheap SaaS like GranolaCO
 inSales adviceChris Orlob tells reps facing "we can just build this" to sell a point of viewMR
 inField notesAt SolCon, SE leaders describe maintenance and accuracy problems with homemade RFP bots
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Clay | 88 |
| 5 | Clarify | 29 |
| 6 | ZoomInfo | 49 |
| 7 | Attention | 29 |
| 8 | Augment Code | 17 |
| 9 | Codex | 83 |
| 10 | Customer.io | 38 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing ops talk peaked in March at 2.1% of the conversation, then slid through July. It is up 5% over the last 30 days but down about a third over 90, and the September bar covers only 23 days. The recent posts are about people running the stack: org change lagging AI, missing owners, and ops shortcuts.
Posts to understand this · as of Sep 23
 inOrg lagScott Brinker says org change lags AI-accelerated martech and reshapes marketing talentAL
 inOps confessionsAshley Langford shares late-night workflow builds and unexplained "do not delete" fieldsMR
 inOwnership gapMike Rizzo found one of about 40 UNBOUND attendees could name their stack owner
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Docket | 30 |
| 3 | GrowthLoop | 29 |
| 4 | HubSpot | 87 |
| 5 | MoEngage | 22 |
| 6 | Augment Code | 17 |
| 7 | Twilio | 41 |
| 8 | Customer.io | 38 |
| 9 | Lovable | 58 |
| 10 | Salesloft | 41 |
Scoring leads and accounts to decide who deserves attention first.
Lead Scoring held between 1.4% and 1.8% through May, then slid to 0.68% in August. No single event explains it. Spring posts treated scoring as its own agent, like Joe Reitz's MQL scoring agent. Recent posts fold it into a wider agent stack. The last 30 days are down 9%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Clay | 88 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 92 |
| 5 | Grok Bot | 64 |
| 6 | Webflow | 48 |
| 7 | 6sense | 40 |
| 8 | Attio | 51 |
| 9 | Codex | 83 |
| 10 | FullEnrich | 42 |
AI agents that discover, compare and buy products on a person's behalf.
Agents as Buyers has stayed between 0.4% and 0.9% all year, with March the high. The last 30 days are up 33% on a run of commerce news: Shopify partnering with Muse for agentic checkout with Shop Pay, Browserbase enabling agent payments through Stripe Link, and Tobi Lütke on agentic shopping at Vercel's Ship SF.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Vercel | 59 |
| 3 | HubSpot | 87 |
| 4 | Lovable | 58 |
| 5 | Clarify | 29 |
| 6 | ElevenLabs | 52 |
| 7 | Exa.ai | 45 |
| 8 | Gamma | 43 |
| 9 |  Lightfield | 24 |
| 10 | OpenClaw | 49 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting rose from March to a June high of 1.27%, then slid through July and August. The last 30 days are down 33%. The biggest posts argue that the copy is rarely the real problem: Corey Haines shipped an /offers skill, Pierre Herubel points to messaging and the offer, and Pam Didner blames the AI brief.
Posts to understand this · as of Sep 28
 XOffer firstCorey Haines ships marketing skills v2.5.0 with an /offers skill for offer designPH
 inDeeper diagnosisPierre Herubel says weak website conversion usually comes from messaging, offer or audience, not copyPD
 inAI briefPam Didner says AI copy reads as formulaic because teams give it weak briefs
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Instantly | 61 |
| 4 | Clay | 88 |
| 5 | Grok Bot | 64 |
| 6 | Midjourney | 36 |
| 7 | AI Ark | 44 |
| 8 | HeyReach | 51 |
| 9 | Nooks | 48 |
| 10 |  Ocean.io | 40 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
Usage pricing talk fell from February to an April low, then rose again in May and June. That stretch brought Kyle Poyar's April roundup of shifts away from seats, monday.com's credit launch in May and Lemkin on Navan's usage revenue in June. Share dropped in July and has stayed near that lower level, with the last 30 days about flat.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Replit | 55 |
| 4 | Vercel | 59 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Claude Code | 99 |
| 7 | Lovable | 58 |
| 8 | OpenRouter | 51 |
| 9 | Supabase | 46 |
| 10 | Twilio | 41 |
A go-to-market operating model where agents execute work across the revenue motion.
Agentic GTM swings month to month, but it has run high since August and is up 24% over 30 days. BCG's finding that only 8% of CMOs run hands-off agentic campaigns framed August. In September, Clay carried it: a $115M Series D at a $7.1B valuation pitched around growth agents, then an API and CLI for Claude, Codex and Cursor.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Clay | 88 |
| 3 | Salesforce | 92 |
| 4 | Claude Code | 99 |
| 5 | Codex | 83 |
| 6 | n8n | 59 |
| 7 | Gong | 63 |
| 8 | Grok Bot | 64 |
| 9 | Outreach | 46 |
| 10 | ZoomInfo | 49 |
Multi-step work planned and executed by agents instead of fixed automation rules.
Agentic Workflows has moved between about 0.4% and 0.6% share since February, then fell to 0.36% in August. The last 30 days are up 53%, back near the top of that range. The lift shows up in late-September vendor posts: D&B wiring its data into Microsoft Copilot Studio agents, Relevance AI pitching autonomous agent workflows at Pavilion's GTM2026, and n8n previewing a Microsoft session.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Codex | 83 |
| 4 | Gong | 63 |
| 5 | Apollo.io | 52 |
| 6 | Claude Code | 99 |
| 7 | Granola | 48 |
| 8 | Grok Bot | 64 |
| 9 | Twilio | 41 |
| 10 | n8n | 59 |
Founders, executives and employees using their own voices to distribute the company's ideas.
This was one of the steadiest topics, near 1% of the conversation from February through August. The last 30 days are down 40%, and no single event explains the drop. The posts still coming are about craft: Diandra Escobar's four-bucket post funnel, Charlotte Lloyd on buyers who watch for months, and Katelyn Bourgoin on owning one idea.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | RB2B | 47 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 87 |
| 5 | HeyReach | 51 |
| 6 | Instantly | 61 |
| 7 | Lovable | 58 |
| 8 | Nooks | 48 |
| 9 |  Tally | 33 |
| 10 | Vector | 38 |
B2B brands paying creators and independent voices to reach trusted audiences.
B2B creator talk has moved in waves, dipping in April and recovering by June. August held up as Maja Voje cited TopRank's figure that 85% of B2B marketers run influencer programs. The last 30 days are down about 30%, even as LinkedIn invited creators like David Walsh into a new entertainment community.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 88 |
| 3 | Gamma | 43 |
| 4 | ElevenLabs | 52 |
| 5 | Granola | 48 |
| 6 | HeyReach | 51 |
| 7 | HubSpot | 87 |
| 8 | Lovable | 58 |
| 9 | Replit | 55 |
| 10 | Vector | 38 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales Ops climbed steadily to a May high, then eased back. The late-summer posts argue about quotas and pay. Collin Cadmus points to a decade of 40% attainment, Kevin Dorsey says SDR cuts didn't work, and Ryan Walsh defends paying a rep $870K. The last 30 days are down 14%.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | ElevenLabs | 52 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 87 |
| 5 |  Monaco | 25 |
| 6 | Chili Piper | 36 |
| 7 | Clay | 88 |
| 8 | Cline | 27 |
| 9 | Codex | 83 |
| 10 | Cursor (Anysphere) | 78 |
The work of earning awareness, trust and preference for a company over time.
Brand Building held around 1% for most of the year, then fell by almost half in the last 30 days. Peep Laja's August post set the tension: in a Marketing Week survey, half of B2B marketers said brand isn't a priority and 58.3% blamed missing ROI. Ethan Smith's upcoming talk asks how to measure brand inside AI answers.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | Semrush | 48 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 87 |
| 5 | Salesforce | 92 |
| 6 | 6sense | 40 |
| 7 | Buffer | 26 |
| 8 | Clay | 88 |
| 9 | Composio | 29 |
| 10 | Docket | 30 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Forward deployed engineering dipped in March, then jumped to a May high after Dharmesh Shah's April 30 post recast FDEs as forward deployed experts. It stayed elevated through August as the idea spread into GTM, from Greg Isenberg's marketing engineer to Rox pitching Rox Teams as revenue agents with no FDEs required. The last 30 days are down 38%.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | HubSpot | 87 |
| 4 | Salesforce | 92 |
| 5 | Clay | 88 |
| 6 | ElevenLabs | 52 |
| 7 | Lovable | 58 |
| 8 | Attio | 51 |
| 9 | Baseten | 46 |
| 10 | Bland | 19 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
AI Employees has held a steady band near 0.5% since February, with May the high point. No single launch moves it; vendors keep it going, as Viktor hired a CRO in July and launched its live Infinity product in September. The last 30 days are up 11%.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Viktor | 32 |
| 2 | Attio | 51 |
| 3 | Ahrefs | 50 |
| 4 | Clay | 88 |
| 5 | Granola | 48 |
| 6 | HubSpot | 87 |
| 7 | Claude Code | 99 |
| 8 | Lovable | 58 |
| 9 | Midjourney | 36 |
| 10 | AirOps | 38 |
Tracing and monitoring what a model or agent did during a production run.
Observability has held between 0.28% and 0.45% share since February, with May the high. It climbed back in August and is flat to slightly up over the last 30 days. September posts come from vendors shipping agent tooling: Snowflake on seeing agent cost, a Langfuse feature demo, and Arize on teams that have traces but can't read them.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | HubSpot | 87 |
| 5 | OpenClaw | 49 |
| 6 | Grok Bot | 64 |
| 7 |  Kiro | 23 |
| 8 | LangChain | 46 |
| 9 | Salesforce | 92 |
| 10 | Attention | 29 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Sales development has lost share almost every month since February and fell another 28% over the last 30 days. People still talk about the role, but now as one part of a larger system. Jacco van der Kooij folds the SDR into one outcome seller, and XBOW moved its BDRs under RevOps as agent managers. Kyle Poyar's May data complicated the obituary: AI natives doubled SDR headcount.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Gong | 63 |
| 3 | HubSpot | 87 |
| 4 | Nooks | 48 |
| 5 | Claude Code | 99 |
| 6 | Clay | 88 |
| 7 | Outreach | 46 |
| 8 | Salesloft | 41 |
| 9 | Apollo.io | 52 |
| 10 |  BetterContact | 42 |
Deciding what to build, why it matters and which product bets come first.
Product Strategy is small and flat. It has held near 0.45% since July, with almost no change over 90 days. The thread that lasts is selling outcomes instead of software: Emergence Capital's March guide to AI-native services, and Mycroft's repositioning from security platform to CMMC certification service. ClickHouse adds the question of what changes when agents become customers.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Codex | 83 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | Exa.ai | 45 |
| 6 | Supabase | 46 |
| 7 | Clay | 88 |
| 8 | Devin | 37 |
| 9 | Grok Bot | 64 |
| 10 | Hermes Agent | 36 |
Websites and docs structured so AI crawlers and agents can read and use them.
Share climbed from 0.37% in February to a 0.71% April peak, held near 0.65% through June, then fell to about 0.45% in July and August. The last 30 days rose 16.7% to 0.475%, a small rebound well below April. Recent posts cover robots.txt controls for AI bots, schema markup, and which crawlers sites block.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Peec AI | 28 |
| 2 | Ahrefs | 50 |
| 3 | HubSpot | 87 |
| 4 | Semrush | 48 |
| 5 | 6sense | 40 |
| 6 | AirOps | 38 |
| 7 |  Calendly | 38 |
| 8 |  Cloudflare Workers | 17 |
| 9 | Codex | 83 |
| 10 | Docket | 30 |
AI agents that create, launch, buy and optimize advertising.
AI-Driven Advertising fell to 0.11% in April, then rose every month to 0.48% in August. Ads in ChatGPT drove the climb, from StackAdapt offering early access in May to OpenAI reporting a $1 billion run rate on Aug. 31. The last 30 days are down 9%. The 90-day change is up 83%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Codex | 83 |
| 3 | OpenClaw | 49 |
| 4 | Hermes Agent | 36 |
| 5 | Runway | 35 |
| 6 | Salesforce | 92 |
| 7 | 6sense | 40 |
| 8 | CallRail | 22 |
| 9 | Claude Code | 99 |
| 10 | Clay | 88 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Content at scale climbed steadily to a May peak, then fell back to its February level by August. The build stories kept coming: Peter Caputa automated most of his team's content production, and Higgsfield raised $400M at a $5.4B valuation. September brought pushback, with Eli Schwartz citing Google's John Mueller on AI spam hurting a site's reputation.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Ahrefs | 50 |
| 3 | Claude Code | 99 |
| 4 |  Crunchbase | 34 |
| 5 |  OXYGEN | 20 |
| 6 |  OtterlyAI | 21 |
| 7 | Peec AI | 28 |
| 8 | Profound | 51 |
| 9 | Salesforce | 92 |
| 10 | Semrush | 48 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium talk now tracks ChatGPT's free tier. The February high came as ads began serving to free users. The topic then sank to a July low. It has rebuilt since, up 50% over the last 30 days, after OpenAI said ChatGPT ads hit a $1 billion run rate and Andrew Yan noted that 95% of users are on the free plan.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Canva | 49 |
| 2 | Lovable | 58 |
| 3 | Replit | 55 |
| 4 | Salesforce | 92 |
| 5 | HubSpot | 87 |
| 6 | Salesloft | 41 |
| 7 | Ahrefs | 50 |
| 8 | Codex | 83 |
| 9 |  Manus | 30 |
| 10 | Runway | 35 |
The runtime around an agent that provides tools, state, controls and stopping rules.
This curve has zigzagged month to month since March. August's lift came from three launches that made the harness the product: Cloudflare's agent runtime, DeepSeek's open-source Harness v0.1, and Perplexity's fully local Portable Computer. The last 30 days are down 25% as that run of launches cooled.
Posts to understand this · as of Sep 28
 inLocal runtimePerplexity launches Portable Computer, running orchestrator, subagents and harness on NVIDIA DGX SparkD
 XOpen-source launchDeepSeek opens Harness v0.1 to developers in preview under an MIT licenseC
 XInfrastructure launchCloudflare introduces @cloudflare/computer, giving every agent its own isolate or Linux container
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | Cline | 27 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Grok Bot | 64 |
| 7 | LangChain | 46 |
| 8 | AI Ark | 44 |
| 9 | Ahrefs | 50 |
| 10 | AiSDR | 22 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound Systems more than doubled from February to a May peak as builders showed off agent-run outbound, like Hans Dekker's AI go-to-market team modeled on real experts. Share has slid each full month since. The last 30 days are down 52%, and recent voices lean on vendor stories: Rox at XBOW and John Barrows on Apollo's one-system pitch.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 88 |
| 3 | Zapier | 53 |
| 4 | AI Ark | 44 |
| 5 | AirOps | 38 |
| 6 | Apollo.io | 52 |
| 7 | Attio | 51 |
| 8 |  Bombora | 28 |
| 9 | Codex | 83 |
| 10 |  ColdIQ | 28 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-Serve peaked in March at 1.13% share, fell to 0.38% by May, then partly recovered to about 0.54% in July and August. The late-summer posts landed after that rise began: Scott Woody said Metronome went self-serve, and Elena Verna read Airtable's sale as self-serve losing priority. Over the last 30 days, share fell 18%, while Runpod pitched self-serve as the start of an enterprise deal.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 88 |
| 4 | Replit | 55 |
| 5 | Apollo.io | 52 |
| 6 | Chili Piper | 36 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | Lovable | 58 |
| 9 | OpenRouter | 51 |
| 10 |  PandaDoc | 32 |
A shared revenue knowledge layer that people and agents can query and update.
GTM Brain more than tripled its share in June and has held that level since, with the last 30 days flat. August kept it there. ZoomInfo put its GTM context layer into Slackbot through MCP, and Swan AI showed 120+ agents feeding from one shared GTM brain.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | Salesforce | 92 |
| 4 | Apify | 52 |
| 5 | Clay | 88 |
| 6 | Cursor (Anysphere) | 78 |
| 7 | Grok Bot | 64 |
| 8 |  Octave | 31 |
| 9 | Instantly | 61 |
| 10 | Lovable | 58 |
Approval and review steps that keep a person involved in an agent's work.
Human in the loop peaked in May, halved by July, then bounced in August. Scott Brinker's chiefmartec framing, which sorts review steps by expertise and thinking time, anchored the rebound, and operators like Brice Maurln explained why they keep one. The last 30 days are down 40%. ASAPP's HILA flips the usual model, with humans backing up the AI.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | n8n | 59 |
| 3 | Clay | 88 |
| 4 | Codex | 83 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | HubSpot | 87 |
| 7 | OpenClaw | 49 |
| 8 | Ahrefs | 50 |
| 9 | Instantly | 61 |
| 10 | Lovable | 58 |
Advantages that grow stronger as more people, data or participants join a product.
Network effects has shrunk every month, from 1.9% in February to about 0.4%, down 18% over the last 30 days. The moat talk that remains is about data and agent access, not user growth: Rahul Pathak telling SaaS to go headless, Salesforce citing 104 trillion records in Data 360, and Sierra calling interaction history a moat.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Codex | 83 |
| 4 | Devin | 37 |
| 5 | Granola | 48 |
| 6 |  Guru | 21 |
| 7 | Semrush | 48 |
| 8 | Vercel | 59 |
| 9 |  ZoomInfo Chorus AI | 16 |
| 10 | Ahrefs | 50 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
Consolidation talk peaked in February and slid to a low in August. The last 30 days are up 28% on September proof points and field reports: Unify said it has ripped out Outreach deployments of 50-plus seats, and Roman Hipp heard 'too many tools nobody owns' at every GTM World Tour stop.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | HubSpot | 87 |
| 4 | Attio | 51 |
| 5 | Claude Code | 99 |
| 6 | Clarify | 29 |
| 7 | Codex | 83 |
| 8 | Nooks | 48 |
| 9 | Outreach | 46 |
| 10 |  Trigify | 37 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
Events talk fell hard in April, then rebuilt to about 0.55% in July and August. The August posts were practical: Ashley Faus on where Bay Area dinners actually draw, Profound launching a community with meetups and hackathons, and Emily Kramer on keeping event traffic on your own site. The last 30 days are down 33%.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Salesforce | 92 |
| 3 | Codex | 83 |
| 4 | HubSpot | 87 |
| 5 | Lovable | 58 |
| 6 | Replit | 55 |
| 7 | Substack | 53 |
| 8 | ZoomInfo | 49 |
| 9 | ActiveCampaign | 31 |
| 10 | Aurasell | 18 |
Rule-based software that moves business work through predefined steps and systems.
Workflow Automation has slid steadily since February, losing more than half its share. The last 30 days are roughly flat at that lower level. No single event drove the decline. The posts still here recast the term around agents and orchestration: Stevie Case tells sellers to run an agent stack, and Automation Anywhere pitches work across CRM, ERP and billing.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | n8n | 59 |
| 2 | Claude Code | 99 |
| 3 | Clay | 88 |
| 4 | Apollo.io | 52 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | ElevenLabs | 52 |
| 7 | Exa.ai | 45 |
| 8 | Findymail | 40 |
| 9 | Instantly | 61 |
| 10 | Intercom | 44 |
The software stack sales teams use to prospect, engage buyers and manage deals.
February was the high point, when Nektar and a FlashLabs tester framed the stack's problem as bad data and a missing decision layer. Share has drifted down since, falling 18% over the last 30 days. No single event drove it. Recent posts, like Outplay's on stack bloat, argue for fewer tools rather than new ones.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Outreach | 46 |
| 4 | Clay | 88 |
| 5 | Gong | 63 |
| 6 | Nooks | 48 |
| 7 | Attention | 29 |
| 8 | Clarify | 29 |
| 9 | HubSpot | 87 |
| 10 | Instantly | 61 |
Using AI to tailor outreach and marketing to each person at scale.
AI personalization has drifted down since February and dropped 35% over the last 30 days. The posts that land are skeptical. An AI cold email that gets the reader's business wrong does more harm than a generic one, and a spotted fact is not a reason to reply. Kyle Asay used AI to cut 1,000 accounts to 50 instead of blasting all of them.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Clay | 88 |
| 4 | Codex | 83 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | ElevenLabs | 52 |
| 7 |  Klaviyo | 39 |
| 8 | Lightfield | 24 |
| 9 | Outreach | 46 |
| 10 | Apify | 52 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI security held a steady share from March through August. Proof-of-control posts fed it, like Cursor's AIUC-1 certification and Cohere's sovereign AI study on data leakage and compliance. The last 30 days are down 42%, and September so far carries smaller notes, like Wiz's analyst recognition.
Posts to understand this · as of Sep 28
 inCertificationCursor earns AIUC-1 certification after an independent audit and adversarial agent testingC
 inResearchCohere-sponsored IDC study names data leakage, privacy and compliance as top enterprise concernsW
 inAnalyst nodWiz named a technical innovator in Latio's 2026 AI security market report
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Midjourney | 36 |
| 3 | Claude Code | 99 |
| 4 | Codex | 83 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | ElevenLabs | 52 |
| 7 | Grok Bot | 64 |
| 8 | Vercel | 59 |
| 9 | Clarify | 29 |
| 10 | Devin | 37 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
AI-native GTM is a small topic with one clear spike in May, when Kyle Norton's talk with Replit CRO Ghazi Masood argued the most AI-native org still hires salespeople. It has settled near 0.3%, down 11% over 30 days. Recent posts are operational, like Lindsay Rothlisberger's AI-first ops model and Verdigris leaving Salesforce for Lightfield.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | Vector | 38 |
| 4 | Claude Code | 99 |
| 5 | RB2B | 47 |
| 6 | Buffer | 26 |
| 7 | Docket | 30 |
| 8 | Docusign | 36 |
| 9 | Exa.ai | 45 |
| 10 | Firecrawl | 40 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise Marketing hit its low in May at 0.16% share, then rose to about 0.38% in July and held there in August. Uniphore's August pitch came during that high: enterprise teams have data but struggle to turn it into decisions. The last 30 days are down 29%, with September posts on production readiness, compliance checks and approval-heavy workflows.
Posts to understand this · as of Sep 28
 inProduction testStephanie Buscemi says enterprises now ask whether AI survives production, security and complianceG
 inTicket workGradial's new CMO Lynn Girotto says marketing became routing briefs and chasing approvalsU
 inData to decisionsUniphore says enterprise marketing teams have plenty of data but struggle to decide
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | HubSpot | 87 |
| 4 | Aurasell | 18 |
| 5 | CHEQ | 15 |
| 6 | Claude Code | 99 |
| 7 | Codex | 83 |
| 8 | Cursor (Anysphere) | 78 |
| 9 | DemandScience | 24 |
| 10 | Grok Bot | 64 |
Time-limited access that lets a buyer test a product before paying.
Free Trial was at its highest in February, at 0.79%, when Kyle Poyar's funnel benchmarks compared freemium, free trial and card-required trials. It fell to 0.2% by April and has stayed near that level since, showing up mostly as a side angle: Stripe on trial abuse, Josh Braun on early upsells. The 21.6% L30 rise starts from a tiny base.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Ahrefs | 50 |
| 4 | Attio | 51 |
| 5 | Clay | 88 |
| 6 | Gong | 63 |
| 7 | Lovable | 58 |
| 8 | beehiiv | 49 |
| 9 | AthenaHQ | 19 |
| 10 | Calendly | 38 |
How sales teams use AI and how it changes the work of selling.
AI in Sales has slid most months since February, from 1.4% to under 0.4% by August, and is down 31% over the last 30 days. Even the new launches concede the first wave fell short. Yuriy Zaremba says AI SDRs overpromised, and Salesloft says early sales AI made teams faster without changing revenue outcomes.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | Attention | 29 |
| 4 | CallRail | 22 |
| 5 | Clari | 33 |
| 6 | Clarify | 29 |
| 7 | Clay | 88 |
| 8 | Clearskies | 21 |
| 9 | Cursor (Anysphere) | 78 |
| 10 |  GitHub Copilot | 36 |
Writing and structuring the instructions a model follows.
Prompt engineering fell 60% over the last 30 days, after a slow slide since February. September's posts explain why: the problem has moved to context. Liam Dunne says he never had a prompt problem. Laurens Nys argues a rollout can't depend on everyone becoming a prompt engineer, and Lyzr says to fix data access before touching the system prompt.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | Attio | 51 |
| 4 | Clay | 88 |
| 5 | Codex | 83 |
| 6 | HubSpot | 87 |
| 7 | Vercel | 59 |
| 8 | Breeze | 21 |
| 9 | Cursor (Anysphere) | 78 |
| 10 | Fireflies | 34 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
AI App Stores & Connectors hit 0.96% in February, after Clay brought its prospecting research into Claude in late January. It held near 0.6% through the summer as launches like Grok's Figma connector kept coming. The L30 share is down 61.8%, and connector news like Tally joining Claude's directory draws little response.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cargo | 31 |
| 3 |  Enrich | 25 |
| 4 | Prospeo | 51 |
| 5 | Airtable | 48 |
| 6 | Apollo.io | 52 |
| 7 | Clay | 88 |
| 8 | Codex | 83 |
| 9 | Octave | 31 |
| 10 | Salesforce | 92 |
Founders running early sales themselves before handing the motion to a sales team.
Share climbed through spring, nearly vanished in May, then came back in July to roughly match the April high. In July, Scott Leese warned founders against hiring before learning to sell, and Peter Kazanjy opened free copies of Founding Sales to all founders. Share has slid since July and is down about a fifth over the last 30 days.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
Sameness talk peaked in February, rebounded in April, and has faded every month since, down about half over 90 days. Recent posts apply the complaint to specific cases. Melissa Rosenthal lines up the matching AI frameworks at Deloitte, Accenture and PwC, and Josh Braun calls out identical cold email openers. Vendors like ActiveCampaign now pitch against it.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Claude Code | 99 |
| 3 | Codex | 83 |
| 4 | AirOps | 38 |
| 5 | Customer.io | 38 |
| 6 |  Grammarly | 29 |
| 7 | Optimizely | 30 |
| 8 | Semrush | 48 |
| 9 | Vector | 38 |
| 10 | Viktor | 32 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
Lifecycle Marketing peaked in May, then slid for three straight months to an August low. The last 30 days are up 7.5%, a small lift from practitioners and vendors: Supademo's screen-by-screen onboarding breakdown, Customer.io's Lifecycle Underground tour of Europe, and Hightouch's Thumbtack story. It is still 42% below where it was 90 days ago.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | beehiiv | 49 |
| 2 | ActiveCampaign | 31 |
| 3 | Apollo.io | 52 |
| 4 | Claude Code | 99 |
| 5 | Customer.io | 38 |
| 6 |  Explorium | 30 |
| 7 | GrowthLoop | 29 |
| 8 | HubSpot | 87 |
| 9 | Instantly | 61 |
| 10 | MoEngage | 22 |
How AI changes headcount, entry-level work and the jobs people still need to do.
This conversation peaked in March, when Microsoft AI said white-collar tasks would be replaced and marketers felt the FOMO. A smaller rise followed in May. Since then it has cooled, down 28% over the last 30 days. The tone has moved from replacement to partnership. Kai Brandt calls sales the safest job, and leaders from Clay, Lovable and HubSpot talk about AI and humans working together.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | Grok Bot | 64 |
| 3 | Lovable | 58 |
| 4 | Attention | 29 |
| 5 | Clarify | 29 |
| 6 | Claude Code | 99 |
| 7 | Clearskies | 21 |
| 8 | Nooks | 48 |
| 9 | Rox | 31 |
| 10 | Sumble | 32 |
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
Autonomous Business peaked in March and slid to an August low. The last 30 days are up 183% from that floor as revenue-per-employee talk returned, from Swan AI's $10M ARR per employee north star to RB2B's spot on a lean AI-native leaderboard. It remains well below spring levels.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | Grok Bot | 64 |
| 4 | Lovable | 58 |
| 5 | Vercel | 59 |
| 6 | Clay | 88 |
| 7 | Cursor (Anysphere) | 78 |
| 8 | ElevenLabs | 52 |
| 9 | Gamma | 43 |
| 10 | Gong | 63 |
AI-native firms that sell finished work instead of software, delivered by agents and a small human team.
Services-as-Software jumped in March and held between 0.28% and 0.35% through June, then fell to about half that by August. Over the last 30 days it rose 27%, lifting it off the August low. September's posts came from an HFS event on the idea, Gainsight's CEO on selling the work, and a relay of Sequoia's bet on services.
Posts to understand this · as of Sep 29
 XSequoia's betRelays Sequoia's claim that the next $1T company will sell services, not softwareG
 inIncumbent shiftGainsight CEO Chuck Ganapathi explains the shift to AI-native services in a Business Journal cover storyBS
 inEvent recapNewsletter from HFS Research's services-as-software event in New York with Phil Fersht
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | AI Ark | 44 |
| 3 | Apollo.io | 52 |
| 4 | Codex | 83 |
| 5 | Crunchbase | 34 |
| 6 | Findymail | 40 |
| 7 | HeyReach | 51 |
| 8 | HubSpot | 87 |
| 9 | Instantly | 61 |
| 10 | Nooks | 48 |
Pushback against AI from customers, workers and the public, and brands repositioning as pro-human.
AI Backlash comes in short flare-ups, not a steady climb. May peaked as the backlash itself became a debate, and August rose again as Artisan's 'stop hiring humans' campaign drew criticism after its walkback. Anti-AI graffiti on Marty Kausas's company billboard in San Francisco kept it in view, though the last 30 days are down 26%.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 78 |
| 2 | Grok Bot | 64 |
| 3 | HubSpot | 87 |
| 4 | Lovable | 58 |
| 5 | Salesforce | 92 |
| 6 | 6sense | 40 |
| 7 | Airtable | 48 |
| 8 | Bland | 19 |
| 9 |  Browserbase | 32 |
| 10 | Clari | 33 |
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
Open source AI sat low through June, then more than doubled in July before easing back. No single launch explains the jump. Baseten's July note that companies run open models alongside closed ones is the clearest signal. The last 30 days are down 23%, despite Bolt's open-model Forge mode and Christopher Lochhead's attack on Anthropic.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Grok Bot | 64 |
| 5 | Airtable | 48 |
| 6 | Attention | 29 |
| 7 | Baseten | 46 |
| 8 | Canva | 49 |
| 9 | Clarify | 29 |
| 10 | Clay | 88 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
The topic jumped in April when HubSpot priced its Customer and Prospecting agents per result: $0.50 a resolved conversation, $1 a warm lead. Salesforce's pay-per-outcome Help Agent kept it in view into late June, then share slid through August. The last 30 days are up 17% from a low base, and Henry Schuck says GTM has too many steps to price this way.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | Cursor (Anysphere) | 78 |
| 4 | Intercom | 44 |
| 5 | Supabase | 46 |
| 6 | Apify | 52 |
| 7 | Bland | 19 |
| 8 | Canva | 49 |
| 9 | Firecrawl | 40 |
| 10 | Frontier | 24 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory peaked in April, alongside Sangram Vajre's post about fractional CMOs hiding the title because of stigma. It fell by more than half into July, as Gaetano DiNardi argued that advice without hands-on work no longer gets paid. The last 30 days are up 25.8%, led by Neil Weitzman's cost case for a fractional CRO over a full-time hire.
Posts to understand this · as of Sep 28
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent Loops nearly tripled in June, from 0.14% to 0.38%, the month Joe Rhew predicted loops and evals would be LinkedIn GTM's next hot topic. Palantir's Agent Engine and SDK launch at DevCon 6 held it up in July. It has cooled since and is down 47% over the last 30 days, now mostly vendor integration posts like Nimble's.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 88 |
| 3 | Attio | 51 |
| 4 | Codex | 83 |
| 5 | Cursor (Anysphere) | 78 |
| 6 |  Daytona | 23 |
| 7 |  Deepline | 28 |
| 8 |  E2B | 22 |
| 9 | HubSpot | 87 |
| 10 | LangChain | 46 |
The strategy of naming, defining and leading a new market.
Category creation held a steady share through spring, then fell 60% over the last 30 days. In August, Profound and Influencer still launched a new category, creator-first AEO. Then the pushback arrived. Nick Velkovski reached $17M ARR without inventing a category, and Joe Chernov argued that foundation models replaced the experts who used to crown categories.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Adobe Marketo | 25 |
| 4 | DemandScience | 24 |
| 5 | Docusign | 36 |
| 6 | Gainsight | 27 |
| 7 | Grammarly | 29 |
| 8 | MoEngage | 22 |
| 9 | Nooks | 48 |
| 10 | Peec AI | 28 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
Provenance barely registered for six months, then jumped from 0.07% in July to 0.9% in August. Anthropic's watermarking FAQ and the EU AI Act's Article 50 rules gave people a concrete reason to talk about it, and Synthesia pointed to C2PA credentials. The last 30 days are down 86%, so the topic still moves on rule changes, not steady demand.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 83 |
| 2 | Runway | 35 |
| 3 | Claude Code | 99 |
| 4 | Clay | 88 |
| 5 | HeyGen | 31 |
| 6 | Higgsfield | 38 |
| 7 | HubSpot | 87 |
| 8 | Lovable | 58 |
| 9 | Salesforce | 92 |
| 10 | ZoomInfo | 49 |
Interfaces that let agents understand and operate software built for human users.
Agent Interfaces moves in bursts. July and August held up as GTM vendors shipped headless updates, with Clay, Apollo, HubSpot, ZoomInfo and others releasing things an agent can call, and Salesforce teased its Agentforce Experience Layer before Dreamforce. The last 30 days are down 31.3%, with talk moving to design questions like Retell's roundtable on agentic interfaces.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 88 |
| 3 | HubSpot | 87 |
| 4 | Peec AI | 28 |
| 5 | Twilio | 41 |
AI-generated creators, avatars and user-style content used in marketing.
Share peaked in April at 0.363%, then fell by more than half in May and settled near 0.09% in July and August. The last 30 days are up 87.5%, though September is still partial. Recent posts line up with that turn: Alina Vandenberghe tests her own avatar for a website chat, and Walnut and Syllaby pitch avatars as presenters and channel faces.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 |  Ranked AI | 34 |
Brands use human authorship and craft as a reason to trust or value their work.
Human-made started from zero in February and still runs small. Its May spike lines up with Dave Gerhardt's post that people will value what they know a human made. Since July it has held a steadier floor, up 42% over 90 days, as the claim moved into pitches for skills marketplaces and content agencies. The last 30 days dipped 10%.
Posts to understand this · as of Sep 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Attention | 29 |
| 2 | Clarify | 29 |
| 3 | Claude Code | 99 |
| 4 | Clay | 88 |
| 5 | Clearskies | 21 |
| 6 | Nooks | 48 |
| 7 | Rox | 31 |
| 8 | Sumble | 32 |
| 9 | Grok Bot | 64 |
| 10 | Salesforce | 92 |
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing showed up in April, dipped in May, then rose to a July high. Wade Foster used it as a warning about runaway AI bills in June, and Dharmesh Shah called it short-lived and pitched valuemaxxing during the July peak. Share fell in August, when Databricks demoed a valuemaxxing gateway, and is down 64% over the last 30 days.
Posts to understand this · as of Sep 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Apify | 52 |
| 2 | Claude Code | 99 |
| 3 | Clay | 88 |
| 4 | Cursor (Anysphere) | 78 |
| 5 | HubSpot | 87 |
| 6 | Intercom | 44 |
| 7 | Midjourney | 36 |
| 8 |  Pitch | 15 |
| 9 | Profound | 51 |
| 10 |  Retool | 27 |
The argument over requiring a form before someone can access useful content.
The gating debate peaked early in the year and fell to about a quarter of its February share by August. The May and June bump came from rules of thumb, like Amanda Natividad's 'ungate the argument, gate the utility' and Ashley Faus arguing all content should be ungated. Newer posts skip the debate and show replacements, like Clay's interactive lead magnets built with Ploy.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Ploy | 23 |
| 2 | Salesforce | 92 |
The online channel mix used to reach, convert and retain customers.
Digital Marketing is a small, fading label. It rose from a March low to a June high, then slid, and is down 41% over the last 30 days. The late posts treat the term as the old world: Rand Fishkin says zero-click made much of 1999-2021 digital work useless, and Salsify says growth now means winning AI agent recommendations.
Posts to understand this · as of Sep 29
| Brand | GTM Index | |
|---|---|---|
| 1 | AI Ark | 44 |
| 2 | Apollo.io | 52 |
| 3 | Chili Piper | 36 |
| 4 | Clay | 88 |
| 5 |  Default | 30 |
| 6 |  Freckle.io | 35 |
| 7 |  HG Insights | 25 |
| 8 | HeyReach | 51 |
| 9 | HubSpot | 87 |
| 10 | Instantly | 61 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
Trust-Based Marketing is a small topic that held its highest share in June and July, then hit a low in August. The last 30 days are up 39%, with posts about proof over polish: G2 published only 70% of submitted reviews in its Trust & Safety Index, and Unbounce made transparent content its newsletter theme.
Posts to understand this · as of Sep 28
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
AI Detection jumped in July, when a Pangram Labs study found more than 40% of long-form LinkedIn posts were fully AI-generated. The share held through August, and Substack pointed to anti-slop features at LinkedIn, Spotify and Snapchat. The last 30 days are down 73.5%, so the slop debate has cooled for now.
Posts to understand this · as of Sep 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 83 |
| 3 | Grok Bot | 64 |
| 4 | Replit | 55 |
| 5 | Substack | 53 |
Software designed for agents to operate as the primary user.
Agents as Users had no share through May. It appeared in June and rose to its peak in August. Share is down about two thirds over the last 30 days. In July and August, MotherDuck and Netlify argued that products should treat agents as users. In September, Ploy shipped a WebMCP ploybook that lets agents request quotes on Ploy sites.
Posts to understand this · as of Sep 28
| Brand | GTM Index | |
|---|---|---|
| 1 | Vercel | 59 |
| 2 | Ahrefs | 50 |
| 3 | Breeze | 21 |
| 4 | Clay | 88 |
| 5 | Cursor (Anysphere) | 78 |
| 6 | Gamma | 43 |
| 7 | HubSpot | 87 |
| 8 | Intercom | 44 |
| 9 | Lovable | 58 |
| 10 |  Neon | 29 |
Using product activity to identify, time and support sales opportunities.
Product-Led Sales is a small topic, never above 0.09% of the conversation, so small moves look large. Share slid from 0.086% in February to zero by April, the stretch Brendan Short's March post describes as the end of the PLG CRM category, then returned in brief spikes. The last 30 days are up 57% to 0.033%, measured against a quiet August.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 88 |
| 2 | HubSpot | 87 |
| 3 | Attention | 29 |
| 4 | Clarify | 29 |
| 5 | Claude Code | 99 |
| 6 | Clearskies | 21 |
| 7 | Codex | 83 |
| 8 | Hightouch | 34 |
| 9 | Intercom | 44 |
| 10 |  Mixmax | 18 |
How model costs, services and agent work put pressure on software gross margins.
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Claude Code peaked at 11.5% of the conversation in March and has slid every month since, to 5.6% in August. The last 30 days are down another 21%. The posts show the shift: people compare it as one harness among Codex, OpenCode and others, gripe about the terminal, and name it as the tool behind a build rather than the story.
Posts to understand this
Cursor is an AI code editor with agents that write, edit and review code.
A slow slide from 3.3% in February to 2.3% in July, then an August jump to 3.0% when Cursor closed its acquisition by SpaceX and joined the SpaceXAI team. Congratulations from Scott Wu and posts about the $60 billion deal followed. The last 30 days are down 30.4% as the deal news fades.
Posts to understand this · as of Sep 29
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay's share climbed from about 4% in February to a 6.6% peak in May, then fell below 4% by July and has held near there, down 5% over the last 30 days. People kept weighing Claude Code against Clay: Connor Jeffers dismissed a Claude-built "Clay killer" in April, Josh Whitfield weighed switching in July but recommitted, and Tim Yakubson said a Clay investor works fully in Claude Code.
Posts to understand this · as of Sep 29
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n's May and June peak lines up with its SAP deal, which embeds n8n inside Joule Studio. The lift faded by July, and the last 30 days are down 26.4%. Recent posts treat it as replaceable, like Josh Whitfield saying Clay workflows built from Codex will replace n8n, Make and Zapier for him.
Posts to understand this · as of Sep 29
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable's share peaked in March, when it made the product free for International Women's Day and hosted SheBuilds build days where new builders shipped first apps. It slid through July, then firmed in August and September so far, while Slack named Lovable among its partners for AI agents in channels. The last 30 days are up slightly, but share sits well below the spring level.
Posts to understand this · as of Sep 24
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit held above 1% through May, then fell to about 0.75% in June and has stayed near that level. August's small bump came from Free Mode, powered by OpenAI's GPT-5.6 Luna and announced by both companies. The last 30 days are down 27%, and the loudest recent mention retells the SaaStr production-database deletion as a safety warning.
Posts to understand this · as of Sep 28
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
OpenClaw stood at 3.7% in February, when Peter Steinberger joined OpenAI and the project became an open-source foundation. Share has fallen every month since, and the L30 is down 25.4%. It now shows up mostly as a reference point: Lenny Rachitsky called Grok Bot an easier OpenClaw, and Aurelien Aubert listed it as one harness among several.
Posts to understand this · as of Sep 26
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
Codex stepped up to about 3% in May and has held there since. Dan Shipper's claim, shared by Lenny Rachitsky, that work will happen inside Codex or Claude Code marked the jump. Plugins like Exa and OpenAI's agents API on the Codex harness kept it steady. The last 30 days are down 8%.
Posts to understand this · as of Sep 26
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Hermes Agent went from zero in March to 0.52% in April, the month Cody Schneider posted a guide to building GTM agents on it. It peaked at 0.60% in May, when xAI added X Premium and X search, then fell every full month since. Nous Research shipped bot mode in August, but share is down 45% over the last 30 days.
Posts to understand this · as of Sep 26
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce's share slid from 5.6% in February to about 4% through the summer. It is up 26% over the last 30 days on Dreamforce-season news: Informatica announced its upcoming debut there as part of the Salesforce family, Legora announced a CRM integration, and Typeface recapped the event. September is incomplete, so the 30-day rise shows the current direction, not a finished month.
Posts to understand this · as of Sep 28
 inDreamforce debutInformatica announces its upcoming Dreamforce debut as part of the Salesforce familyL
 inLegal integrationLegora and Salesforce will integrate to pull CRM deal data into contract draftingT
 inPost-event recapTypeface named one of CRN's Salesforce ecosystem partners to watch after Dreamforce 2026
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
HubSpot peaked in May at 6.0%. It slid for three months to 3.3% in August, despite the Revenue Hub launch and the Warmly acquisition in June. The last 30 days are up 9%, a small lift, with Trigify's team joining HubSpot on September 23.
Posts to understand this · as of Sep 24
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Gong's share peaked near 1.9% in February and April, then slid to 1.13% in August. The last 30 days are up 5.6%, a small lift off that low. The biggest recent post cites Gong's talk-ratio research, and Gong unveiled new products at Celebrate on Sept. 30.
Posts to understand this
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
Vercel sits near 1% most months, with an August bump from Vercel Ship 2026 and Slack Code, which launched with Vercel among its agent partners. Much of its airtime arrives through other companies' news. In September, Cognition hired v0 creator Jared Palmer as VP of engineering, and the last 30 days are down 34%.
Posts to understand this · as of Sep 26
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Claude Cowork peaked in March at 3.2% and has fallen every month since, down 58% over 90 days and 30% over the last 30. No single event explains the slide; it is a steady monthly fade. September's clearest news came from partners, as Docusign joined Anthropic's Claude for Small Business relaunch and brought agreement tools into Cowork.
Posts to understand this · as of Sep 24
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly climbed steadily from February to a June high, then roughly halved in July. The lift came less from Instantly's own news than from builders naming it as the send step in Claude-built outbound stacks, like Jan Rasmussen's hooks and Hans Dekker's agent team. The last 30 days are flat, up 6%, with Dima Bilous running about 200 mailboxes through it.
Posts to understand this · as of Sep 25
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter spiked in August, when Stripe agreed to acquire it to help businesses route and pay for tokens. That deal spike has faded, and share is down 62% over the last 30 days. What remains is OpenRouter as a scoreboard: its data showed users spending more on OpenAI than Anthropic for the first time in over 2.5 years.
Posts to understand this · as of Sep 27
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
Substack talk has drifted lower since spring, with a June dip and a July bounce. The bounce lines up with Substack partnering with Pangram to scan posts and comments for AI writing. Share is down 17% over the last 30 days, and recent posts are more about where creators build, like Adam Schoenfeld's move to beehiiv, than about the platform itself.
Posts to understand this · as of Sep 26
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Semrush's share held near 0.56% through March, dipped in April, then climbed to a June high of 1.1% while it hosted an AI search villa at Cannes. It fell back through July to a low of 0.37% in August. September so far runs a bit above August, with posts on Google redirects and MCP, but the last 30 days are down about 7%.
Posts to understand this · as of Sep 25
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva peaked in April and has drifted down since. The last 30 days are off 42%. The recent conversation is about cost more than design. Melissa Rosenthal ties a $7.1 billion valuation cut by Blackbird and AirTree to the cost of AI features and a growth forecast cut from 30% to 20%. Meanwhile, Canva shipped 100 upgrades to its visual suite.
Posts to understand this · as of Sep 28
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Ahrefs roughly tripled its share in May, held it in June, then gave back about half by August. No post here explains the spring jump. The last 30 days are up 42%, led by Ahrefs' own update on Google's /goto redirects disrupting its data, plus CMO Tim Soulo's growth-channel ranking in an Instantly video.
Posts to understand this · as of Sep 28
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier's share has fallen by more than half since February, from 1.4% to about 0.6%, and the last 30 days are down another 32%. The steadiest pattern is operators writing their own glue. Joe Rhew's 'bare metal GTM' and Jan Rasmussen's Claude Code hooks both name Zapier as the layer they skip, while Zapier's own push centers on its ZapConnect build-off.
Posts to understand this · as of Sep 24
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
ZoomInfo peaked at 1.5% in March and has slid since, down 45% over 90 days and 13% in the last 30. Much of the talk is about replacing it: Ava 2.0 claims to, and Moltsets pitches $27 a month for unlimited contact data. ZoomInfo's own story, MCP access through Slackbot, hasn't lifted the curve.
Posts to understand this
Profound measures and improves how brands appear in AI answers.
Profound's share bounces month to month, with an April bump when it named the marketing engineer role and Ross Simmonds ran with it. The last 30 days are up 37% on a $180M Series D at a unicorn valuation, seven months after its prior round. Profound then marked the news at the NYSE.
Posts to understand this · as of Sep 26
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
ElevenLabs held about 0.76% share in February and March, rose to about 0.9% in April and May, dropped to 0.56% in June and reached 0.5% by August. Over the last 30 days its share rose 52% to 0.76%. September posts covered the sales machine behind its $600m-plus ARR, its 59 open enterprise seller roles and a webinar pipeline that grew to over $8m.
Posts to understand this
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio's share more than doubled from February to a May peak, helped by Intercom's Fin x Attio sales story in April and Attio's GTM Atlas launch in May. It has faded since, down 35% over 90 days and 16% over the last 30. Recent posts are user reviews praising the flexible data model, not new launches.
Posts to understand this · as of Sep 27
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo.io's share climbed from March to a May peak of 0.93%, then settled near 0.65% to 0.71% from June through August. Raouf Lemouchi's April post described running Apollo through Claude as a prospecting data layer, and in late August Replit listed Apollo as a partner in its growth kit. Over the last 30 days, share is down about 16%.
Posts to understand this
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify's rise came through Claude users. From May through July it sat near 0.9% as guides showed Claude running Apify actors for social analysis and content agents. That wave is fading, down 22% in the last 30 days, and Apify now shows up as one custom scraper inside Claude Code GTM stacks.
Posts to understand this
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Granola peaked near 1% in May, fell to 0.44% in July, and has held around 0.57% since. The L30 share is flat at +2.1%. Recent mentions put it inside other tools' stories: a connector for Grok Bot's sales bots, and Henry Hund replacing it with Muesli, an offline, open-source app.
Posts to understand this · as of Sep 26
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
HeyReach went from no share in February to about 0.9% by June. It first surfaced in March, when reports of LinkedIn banning automation tools put it on the list. Since July it has settled lower and shows up mostly in stack lists and outbound critiques. The last 30 days are down 28.9%.
Posts to understand this · as of Sep 25
 inSkeptic viewGhazi Masood recalls an SDR's HeyReach-and-agents stack that looked like spamDB
 inStack keepDima Bilous keeps HeyReach while his team rebuilds Clay, n8n and more in-houseB
 inPlatform crackdownBrendan Short lists HeyReach among LinkedIn automation bans; HeyReach says customers are unaffected
RB2B identifies the people and companies visiting a website so sales can follow up.
RB2B rose every month from February to a June high, with Sam Dunning's post on its $9.1M ARR, bootstrapped, landing just before the peak. It then fell by more than half into August and is flat over the last 30 days. Mentions mostly place it as the website-visitor signal inside bigger stacks, from Unify's Listen Labs playbook to Bill Stathopoulos's tool list.
Posts to understand this · as of Sep 25
Intercom is a customer messaging platform built around Fin, its AI support agent.
Intercom's June bump lines up with Salesforce signing a deal to acquire Fin. In July, share fell by more than three quarters and stayed low through August. The last 30 days are up 47%, with Fin now used as a reference point. Jason Lemkin cites the exit, and Charles Tenot says his outbound agent is pulling in support questions.
Posts to understand this · as of Sep 28
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
LangChain's share jumped in March, fell in April, then climbed back and held near 0.4% from June through August. It is up 25% over the last 30 days. Recent posts show LangChain testing a new way to evaluate agents, a sponsor preparing for Interrupt26 in NYC, and Emily Kramer trying LangChain for production-grade agents.
Posts to understand this · as of Sep 28
Baseten deploys and runs custom AI models in production.
Baseten went from no share in February to 0.32% in April, when it was a day-zero launch partner for Kimi K2.6. It rose again to 0.46% in August, when it made its Inference Engineering book free. The last 30 days are down 15%. Harvey's post-training work with Baseten keeps it in view.
Posts to understand this
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Nooks moves in bursts. Its February high matched the AI sequencer launch, pitched against Outreach and Salesloft, and a climb to July included a Nooks-backed SDR leader council. August dipped even as Peter Mollins' farewell post drew wide response. The last 30 days are up 58%, with no single event behind it in the evidence.
Posts to understand this
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Common Room rose steadily from 0.26% in February to 0.66% in July, topping out with Zoom's acquisition on July 2. Once the deal news passed, it fell to 0.21% in August, and the last 30 days are down another 52%. Recent mentions treat it as one example in a wave of GTM platform exits, alongside Pocus and Warmly.
Posts to understand this
Exa.ai is a web search API designed for models and AI agents.
Exa went from almost nothing in February to a steady band since May. Its $250 million Series C at a $2.2 billion valuation marked the May step up. Use is what keeps it there. Operators like Sean Wilson now map TAM with Exa inside their outbound workflows. The last 30 days are up 19%.
Posts to understand this · as of Sep 28
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly climbed from about 0.27% in early spring to a July peak of 0.54%, when HubSpot bought it and Zoom bought Common Room the same week. Posts read both deals as a rollup of intent-signal tools. August fell back to 0.14%. The last 30 days are down 12%, and Warmly now shows up mostly as an example of consolidation.
Posts to understand this
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode fell away after February, then climbed every month from March to an August high. Grok's short plug for Grok 4.6 in OpenCode landed in that peak. September brought platform mentions, with Databricks and Together AI both naming OpenCode as a supported harness. The last 30 days are down 37% from August's level.
Posts to understand this · as of Sep 28
Gamma turns prompts into presentations, documents, websites and images.
Gamma has drifted down from a March high, and the last 30 days are off 28.4%. September posts center on where Gamma shows up: Atlassian announced a two-way integration with Jira and Confluence, Leslie Venetz builds decks by tagging Gamma from inside Claude, and Zain Kahn cited 50 million users and $100 million ARR with about 50 people.
Posts to understand this · as of Sep 29
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps share peaked in May at about 1%, the month Ross Simmonds shared a study his team ran with AirOps on 5.1 million AI responses. Share fell below 0.2% by July and has held near 0.24% since. In September, Diandra Escobar cited AirOps data on YouTube's rising share of AI citations, but the last 30 days are still down 19%.
Posts to understand this · as of Sep 24
1mind provides AI sales agents for websites, demos, live calls and customer success.
1mind peaked in February, when Amanda Kahlow's $30M raise and Jacco van der Kooij's post on a year of running Jack on his homepage landed within a week. Share has drifted down since, with a small June bump. August's story of $1M in webinar pipeline through Sequel.io didn't lift it, and the last 30 days are down 53%.
Posts to understand this · as of Sep 24
Firecrawl turns websites into clean, structured data for models and agents.
Firecrawl went from no share in February to a July high, lifted by GTM builders more than launches. In May, Christian Oland pitched Firecrawl plus Claude Code as a way to scrape data Clay can't reach. In July, Corey Haines praised its free-credits onboarding. The last 30 days are down 38%.
Posts to understand this · as of Sep 27
Higgsfield generates video and images for ads and social content.
Higgsfield bottomed in April. Its MCP launch on April 28 put Seedance 2.0 and GPT Images 2.0 inside agents and started a rebound, and creator giveaways like PJ Ace's Pokémon trailer images kept it there through July. It fell back in August and is down 5% over 30 days, with the news turning to infrastructure as Together AI hosts its video models.
Posts to understand this · as of Sep 25
Grok Bot is an always-on agent that learns routines and completes work across existing software.
Grok Bot went from zero to 1.25% share in August, its first month in the conversation. Early users described it doing real work on its own, like canceling a service, and Stripe let bots buy anywhere with a Link card. The L30 share is up 82%, with GTM builders like Eric Nowoslawski running a bot per customer.
Posts to understand this · as of Sep 26
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce did not exist in this data before August. What is carrying it is argument, not announcement: Jason Lemkin saying he has run Salesforce headless with a Claude agent for six months, Janis Zech reading the deal as Salesforce conceding the CRM is not where users should sit, Justin Norris calling it a dopey name and a smart bet.
Posts to understand this · as of Sep 25
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
GPT-6 barely registered until August. It now stands at 4.8% of the conversation, with September posts centered on Astra. Supabase offered unlimited Astra tokens, and Peter Walker reported OpenAI taking 31% of OpenRouter spend over 48 hours. On September 22, Notion added the GPT-6 Luna and Sol models to its picker.
Posts to understand this · as of Sep 24
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Fable went from nothing to 3.6% in June when Anthropic launched Fable 5, then rose to 4.3% in July before falling to 1.3% in August. Fable 5.1 restarted it: Cursor shipped it on Sept. 1 with a 73.4% CursorBench score, and Claude ran build days from Sept. 11 to 25. The last 30 days roughly doubled.
Posts to understand this
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
GPT-5 share rose in March and peaked in April, then fell back sharply in May and has stayed low since. Over the last 30 days it slipped further. The posts track cost: an April post from the peak compares tracking costs by model, a July talk swaps in GPT-5 mini to cut costs, and a September post says frontier prices are rising.
Posts to understand this · as of Sep 24
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Claude Opus talk comes in bursts and fades between them. July jumped to 1.0% of the conversation as Opus 5 launched and landed in Perplexity, then fell to 0.3% in August. September is running near 1.0% so far, up 116% over 30 days. Early in the month, a cheaper open model was pitched as matching Opus 5 on slides.
Posts to understand this · as of Sep 24
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Grok 4 sat near zero through June, then jumped more than tenfold in July when Grok 4.5 took the top spot on AutomationBench-AA, ahead of Claude Fable 5. Grok 4.6 topping CursorBench in August kept it high. The last 30 days are down 22%, though Grok 4.7 is already shipping inside tools like Genspark.
Posts to understand this · as of Sep 29
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Claude Sonnet faded to almost nothing by May, then spiked in June with the Sonnet 5 launch, which more than doubled its score on Zapier's automation benchmark. Talk cooled through August, even after Anthropic made the $2 and $10 per million token pricing permanent. The last 30 days are up 178% as Sonnet 5.5 reaches platforms like Netlify.
Posts to understand this
Muse Spark is Meta's AI model for running coding and other agents.
Muse Spark has climbed since July as Meta ships new versions. Cline tested version 1.2 against Meta's agent harness in August. In early September Meta launched Muse, a personal agent on version 1.3, and Genspark made 1.3 live in its chat and code agent. The last 30 days are up 42%.
Posts to understand this · as of Sep 29
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Gemini Flash moves in release steps. It sat near zero until Gemini 3.5 Flash landed in May, with Databricks among the first to offer it. Gemini 3.6 Flash brought the July bump, with Harvey reporting gains on legal drafting. September is holding steady as Wiz and Google DeepMind launch Scan for Good on a Gemini 3.8 Flash cyber model.
Posts to understand this · as of Sep 28
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
Kimi K3 made July the peak. It took #1 on the frontend code arena, David Sacks called that concerning, and Vercel's benchmark showed half the top score at a fifth of the cost. Share halved in August but stayed high as builders used it, including Harvey's Tenet legal model. The last 30 days are down 54%.
Posts to understand this · as of Sep 28
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen climbed from 0.07% in February to 0.65% in August, carried by builders running it on their own hardware. August's high came with debate over whether Qwen 27B can handle production code. The last 30 days are down 59%, though homelab setups and the open-weight Qwen-Image-2.1 release kept it in view.
Posts to understand this
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM barely registered until June, then held between 0.6% and 0.7% for three months. GLM 5.2 gave it a benchmark story as the first open model to lead an APEX-SWE category. The last 30 days are down 34%, but the talk has moved to distribution: GLM 5.3 Flash took 54% of open-model use on Bolt, and Notion added both 5.3 models.
Posts to understand this
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos spiked to 1.65% in April, when Anthropic held back Claude Mythos Preview and shared it with 40 partners for defensive security work. A second high in June faded, and share has held near 0.25% since July. The Sept. 1 launch of Mythos 5.1 hasn't lifted it. The last 30 days are down 16%.
Posts to understand this
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney's share peaked at 0.72% in February and slid to 0.34% by April. It jumped back to 0.67% in June, around its June 18 presentation, then fell to 0.22% in July. The last 30 days are down 35%, to 0.16%.
Posts to understand this · as of Sep 23
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Devin's share swings month to month. It peaked in April, when Windsurf 2.0 shipped cloud delegation to Devin, then fell to a low in June. Share climbed back in July and August without a clear trigger, and the last 30 days are down 31% while posts cite Devin as one of several parallel cloud agents and a GPU experiment runner.
Posts to understand this · as of Sep 26
Runway is an AI platform for generating and editing video and images.
Runway drifted down from February to a low of 0.11% in August, even as its July tease of Seedance 2.5 drew strong attention on its own post. Share has more than doubled over the last 30 days. The September evidence is thin: Runway shows up as a guest at MiniMax's Japan IP conference, alongside Higgsfield, Krea and HeyGen.
Posts to understand this · as of Sep 29
Jev is TypeSafe AI's decision model, which returns typed answers such as choices, probabilities and scores instead of text.
Jev did not exist in this conversation before September. It arrived with proof points within two days: LangChain tested it against LLM judges, and Vercel said it was adopted faster than any model in AI Gateway history, reaching about 13% of teams on day one. Andrew Chen argued its low cost could make free, ad-supported AI apps work.
Posts to understand this · as of Sep 25
Muse is Meta's personal AI agent, which connects to a person's email, calendar and payments to shop, book and schedule for them.
Muse barely registered before Meta launched it on September 8, and the last 30 days are up more than tenfold. Launch partners carried it: Shopify announced agentic checkout, with Spotify, Walmart, Sephora and OpenTable joining. The talk has since turned practical, with Granola shipping inside the app and Austin Armstrong sharing prompts for landing a hard dinner reservation.
Posts to understand this · as of Sep 28
Instinct is a personal AI agent with its own email address that creates accounts, contacts businesses and handles support requests for its user.
Instinct had no mentions before August and now holds 0.78% share, up 532% in the last 30 days. The fuel is its valuation ramp: a $500m Series A on Aug. 1, a $2.5b Series B on Aug. 26, and a raise at $10b. Much of the talk lives on X, and one poster says LinkedIn hasn't caught on yet.
Posts to understand this
Join 19,372+ GTM leaders and practitioners. Free, unsub anytime.
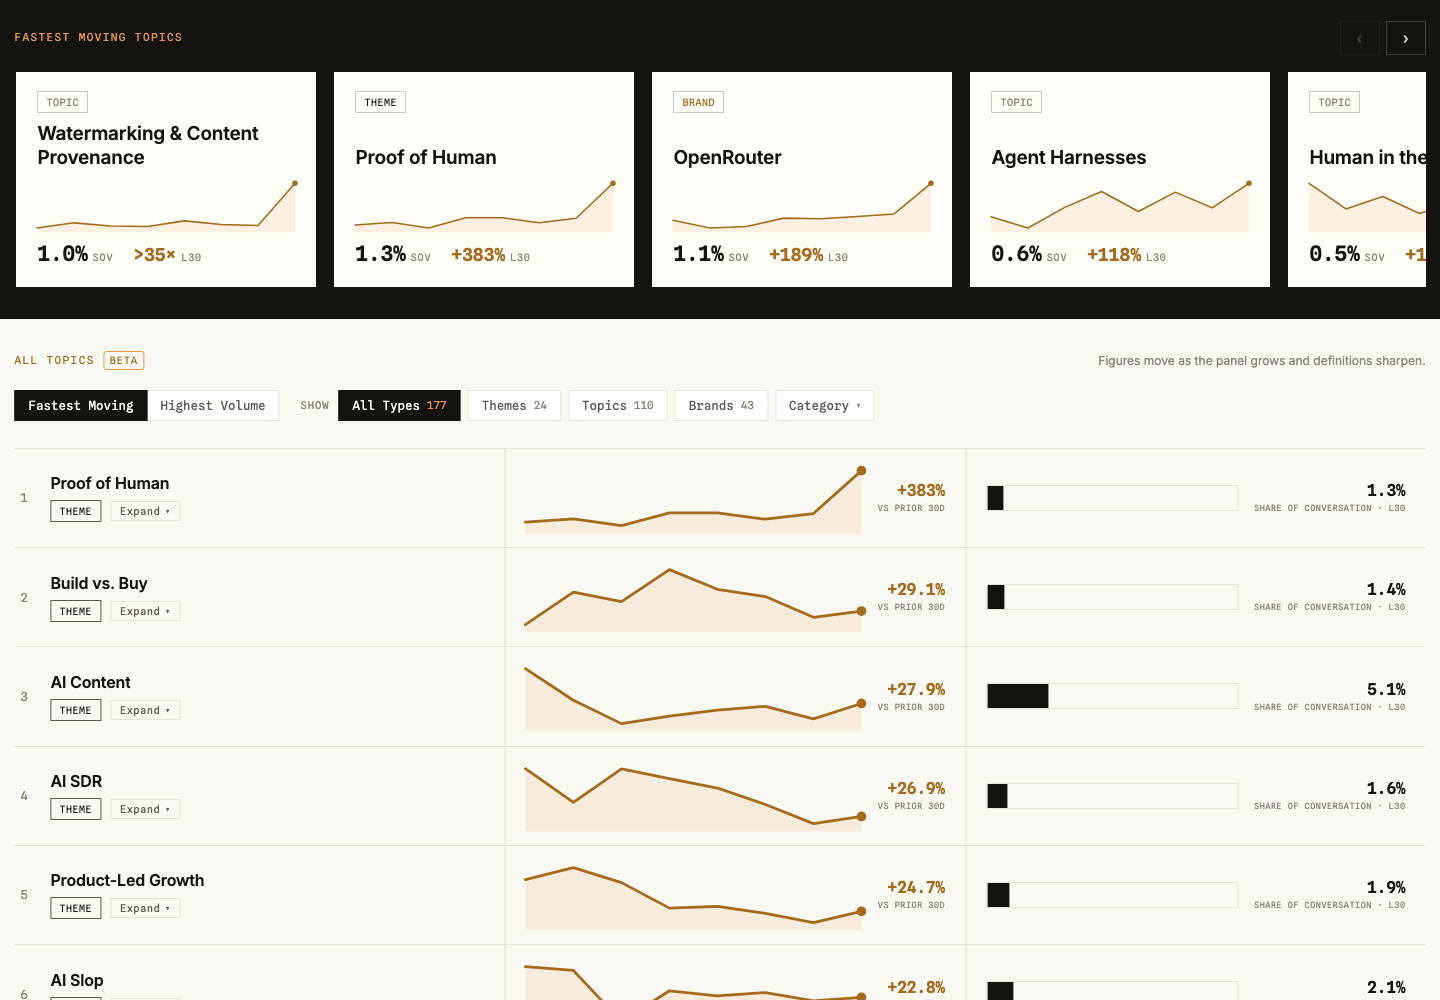
Loading people…
join 19,372+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-09-30.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,372+ gtm leaders, unsub anytime.