What’s moving now
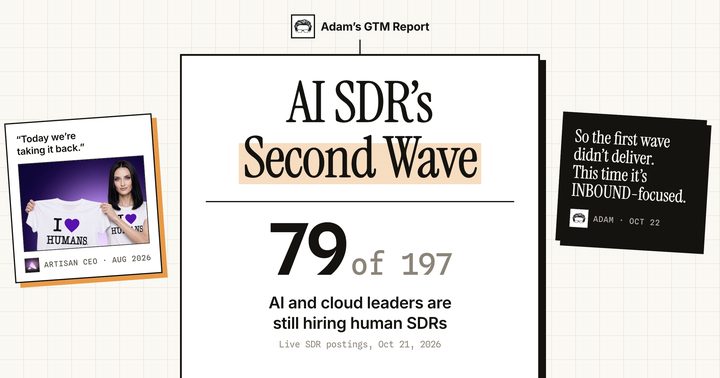 AI SDR's Second WaveOct 22 · Outbound didn't stick. The inbound bet. Clay's move. Agent
 16.2× the usual response · 372 engagements
 15.3× the usual response · 6,903 engagements
 14.2× the usual response · 559 engagements
 5.1× the usual response · 833 engagements4.4× the usual response · 1,337 engagements
 MongoDBFirst seen Oct 24Featured roleSr. Manager, GTM Engineering
 6senseFirst seen Oct 23Featured roleDirector, Marketing Operations
 Temporal Technologies$209K-$330K · 50% above the medianFeatured roleSenior Content Marketing Manager
 Iterable$175K-$188K · 5% below the medianFeatured roleAI Growth Manager Ads
 LemlistFirst seen Oct 25Featured roleCustomer Community Manager
 AvePointFirst seen Oct 23Trending Creator
 Ashley KramerAnnounces expanded APAC hiring and investment, citing customer plans for voice AI travel assistants, banking services, and support for super-app users.
 783 interactions · 2d agoTrending Creator
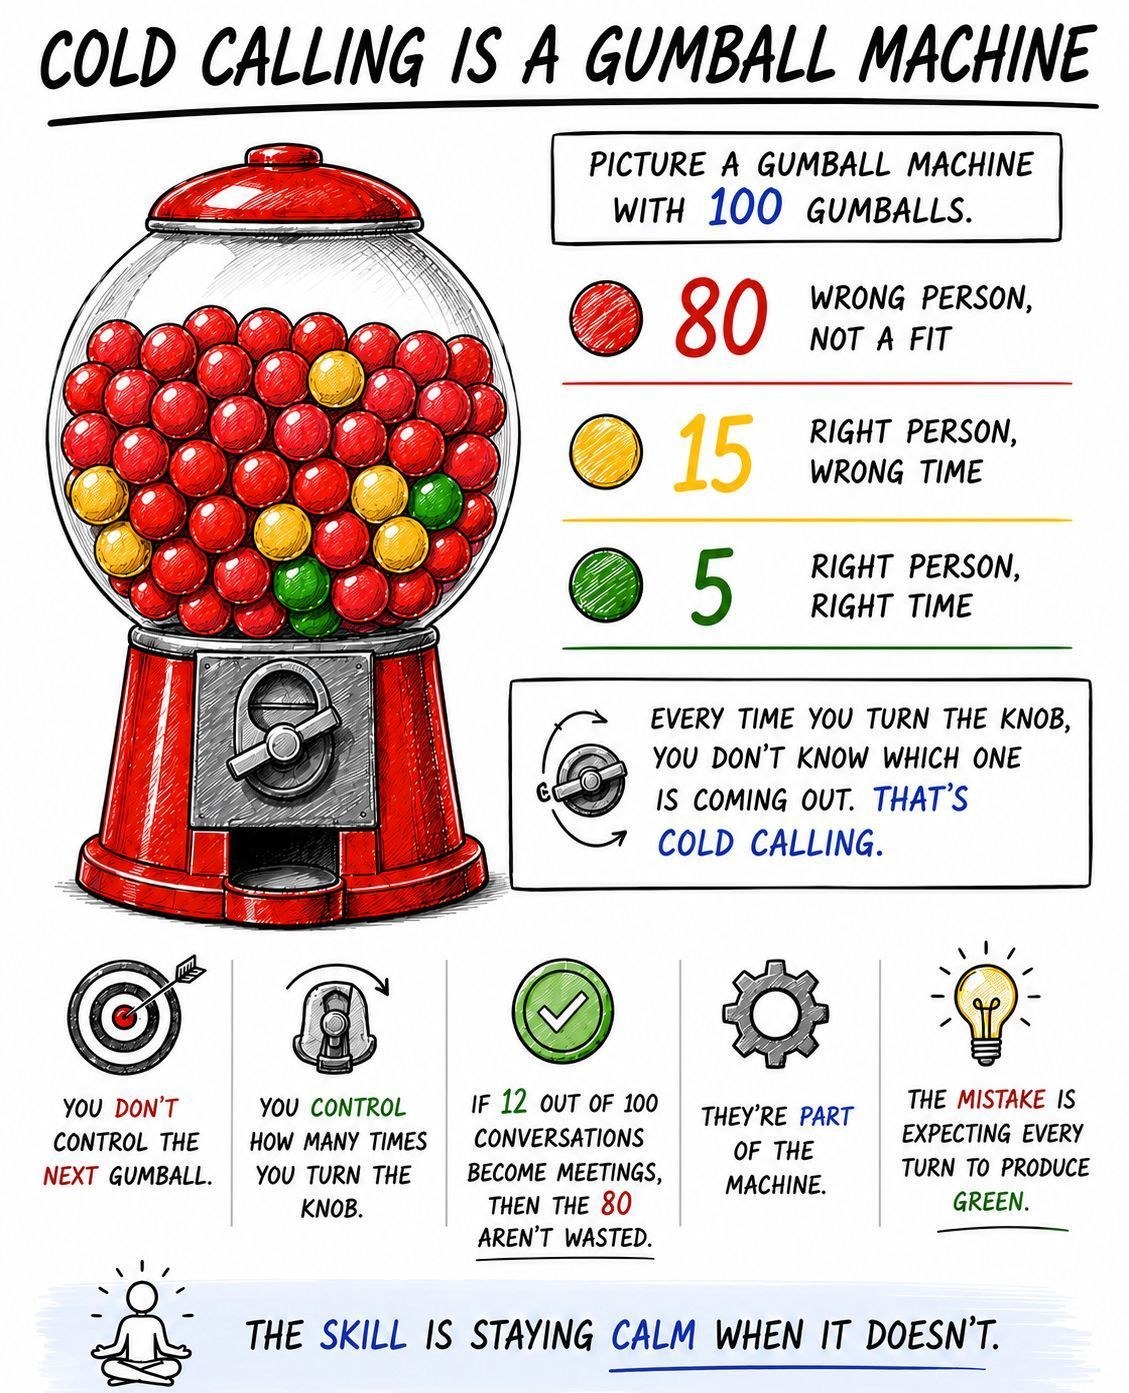
 Josh BraunCompares cold calling to a gumball machine, arguing that rejection and delayed interest are expected, while callers control outreach volume rather than individual outcomes.
 664 interactions · 2d agoTrending Creator
 Ryan WalshArgues sellers should focus on deals rather than collections, recommending a collections team, deal desk, or clear clawback policy.
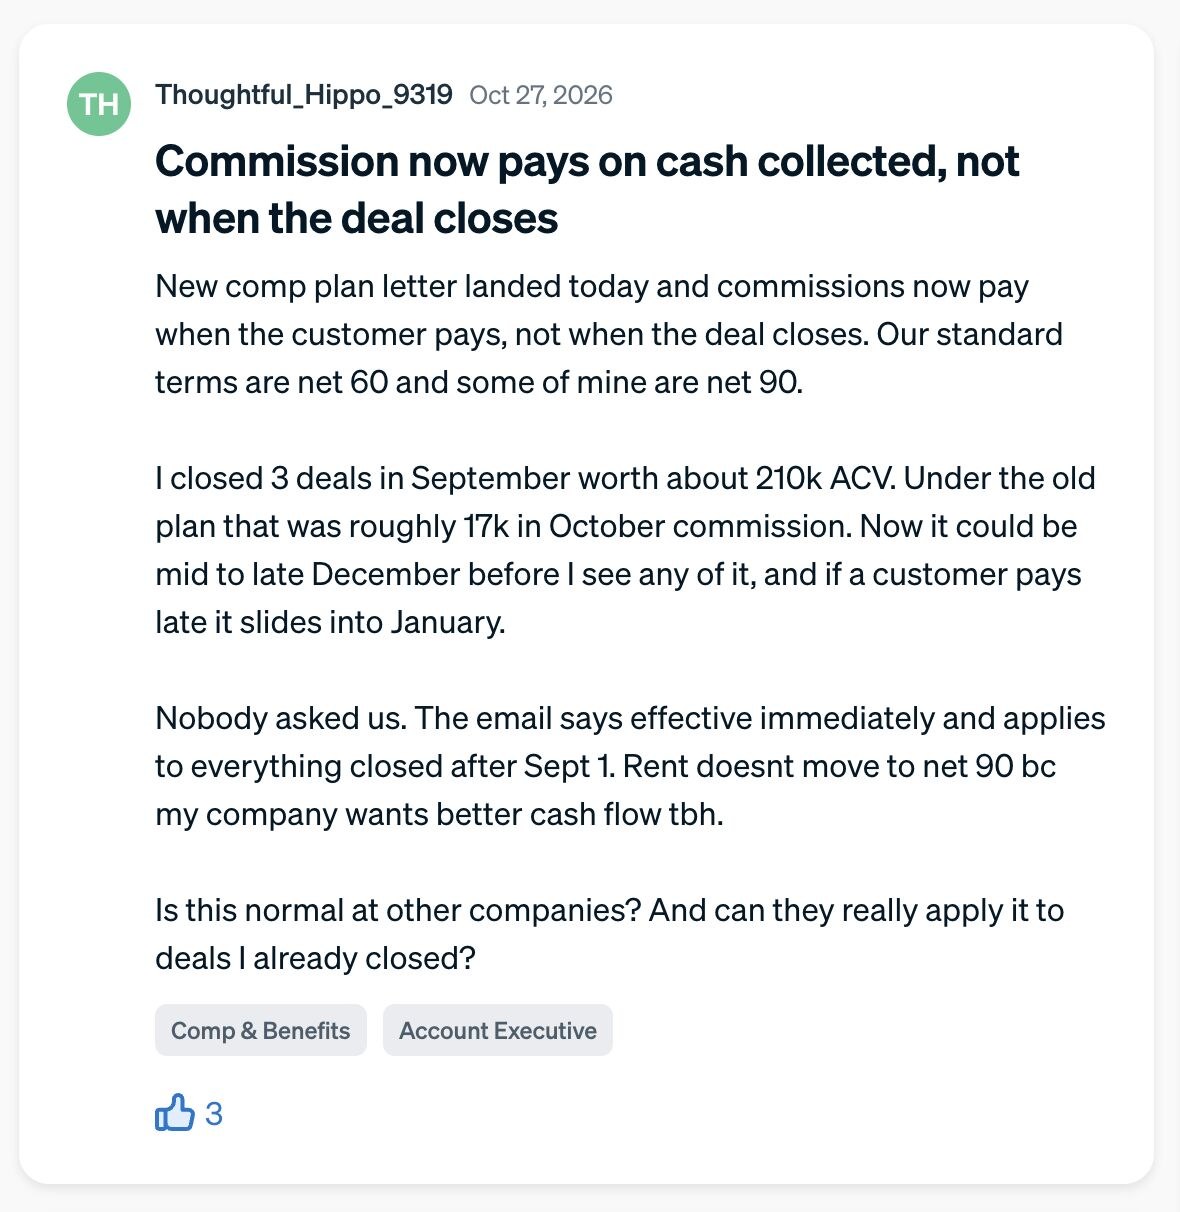 662 interactions · 21h agoTrending Creator
 Amanda NatividadAnnounces Zero Click Marketing’s release and argues AI reinforces its advice to reach audiences where they already spend time.
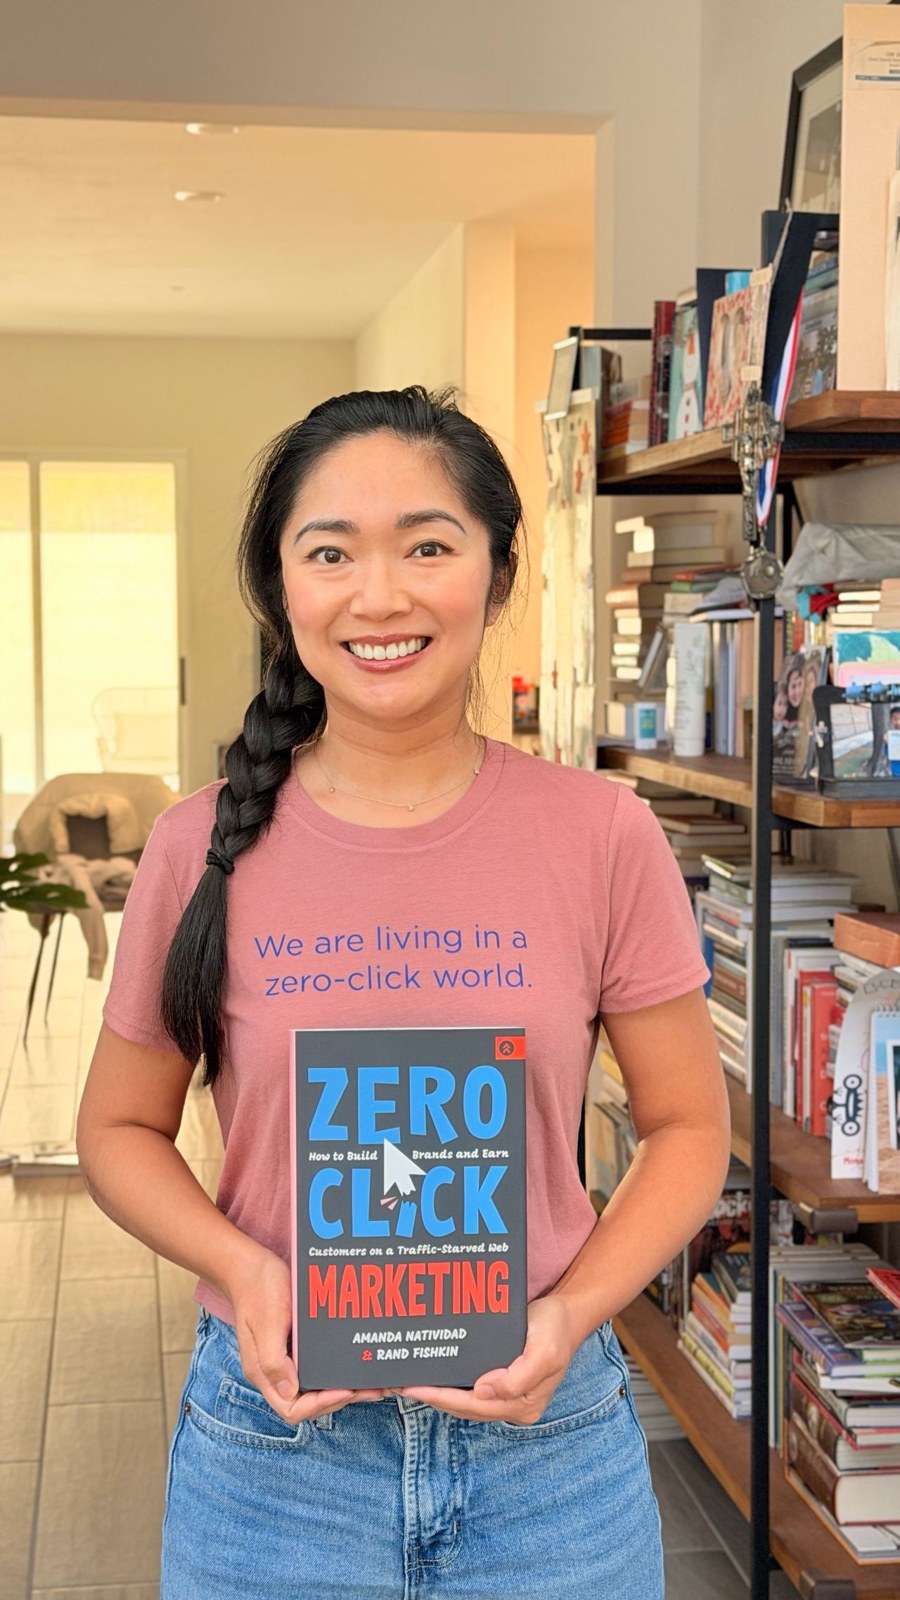 647 interactions · 1d agoTrending Creator
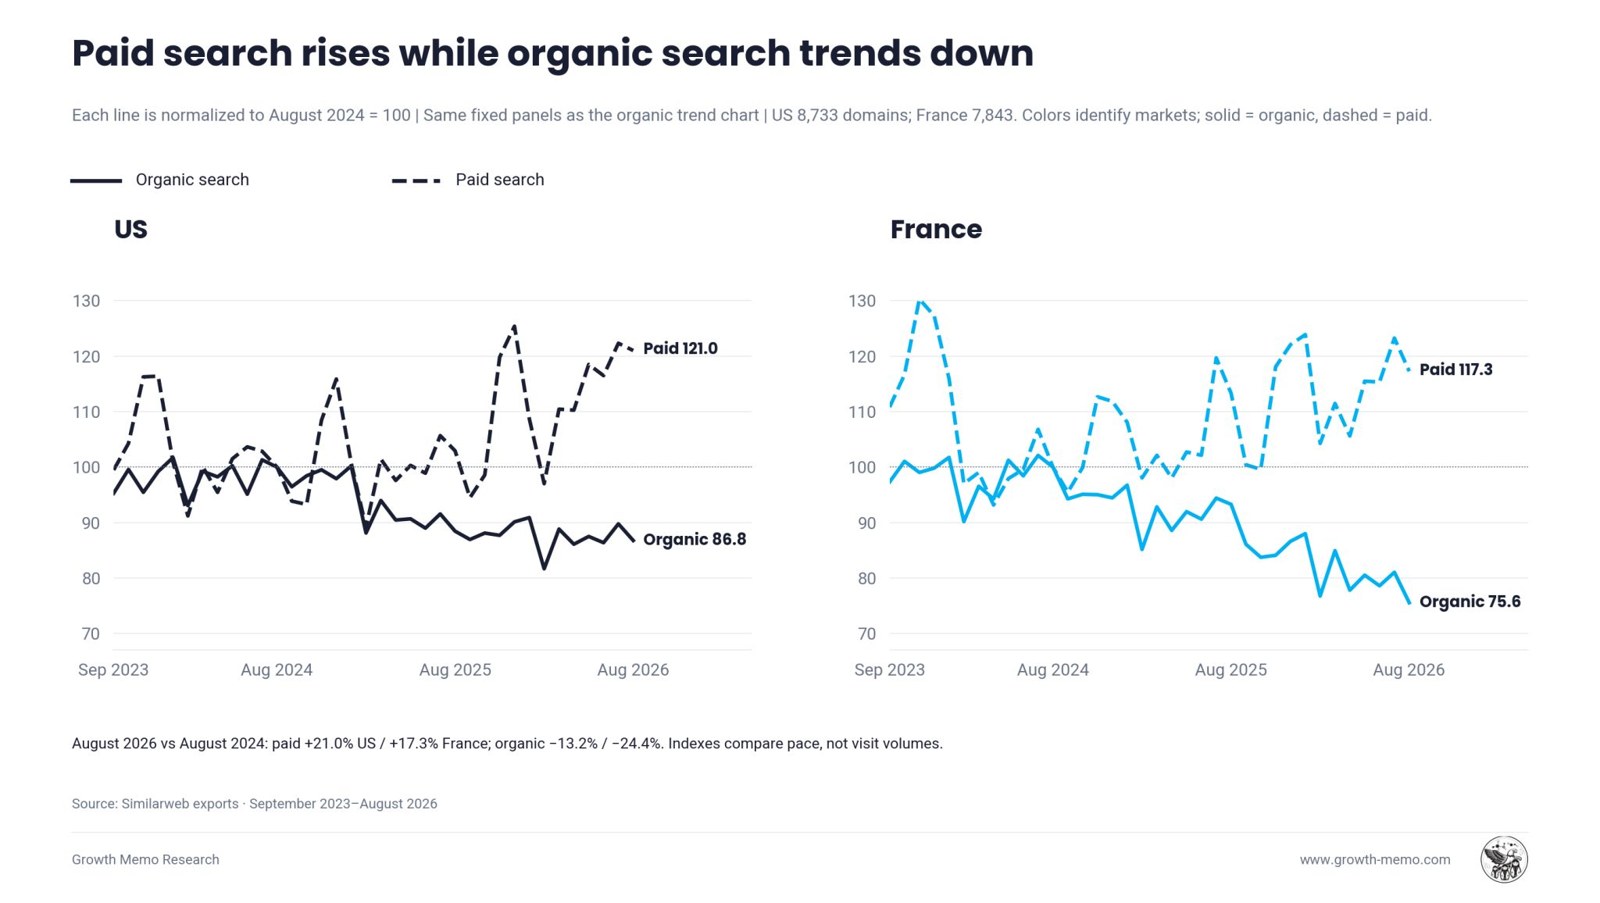
 Kevin IndigReports organic search declines across 10,000 domains, arguing AI alone cannot explain losses because paid search growth, industry differences, and Google updates also contribute.
 604 interactions · 2d agoTrending Creator
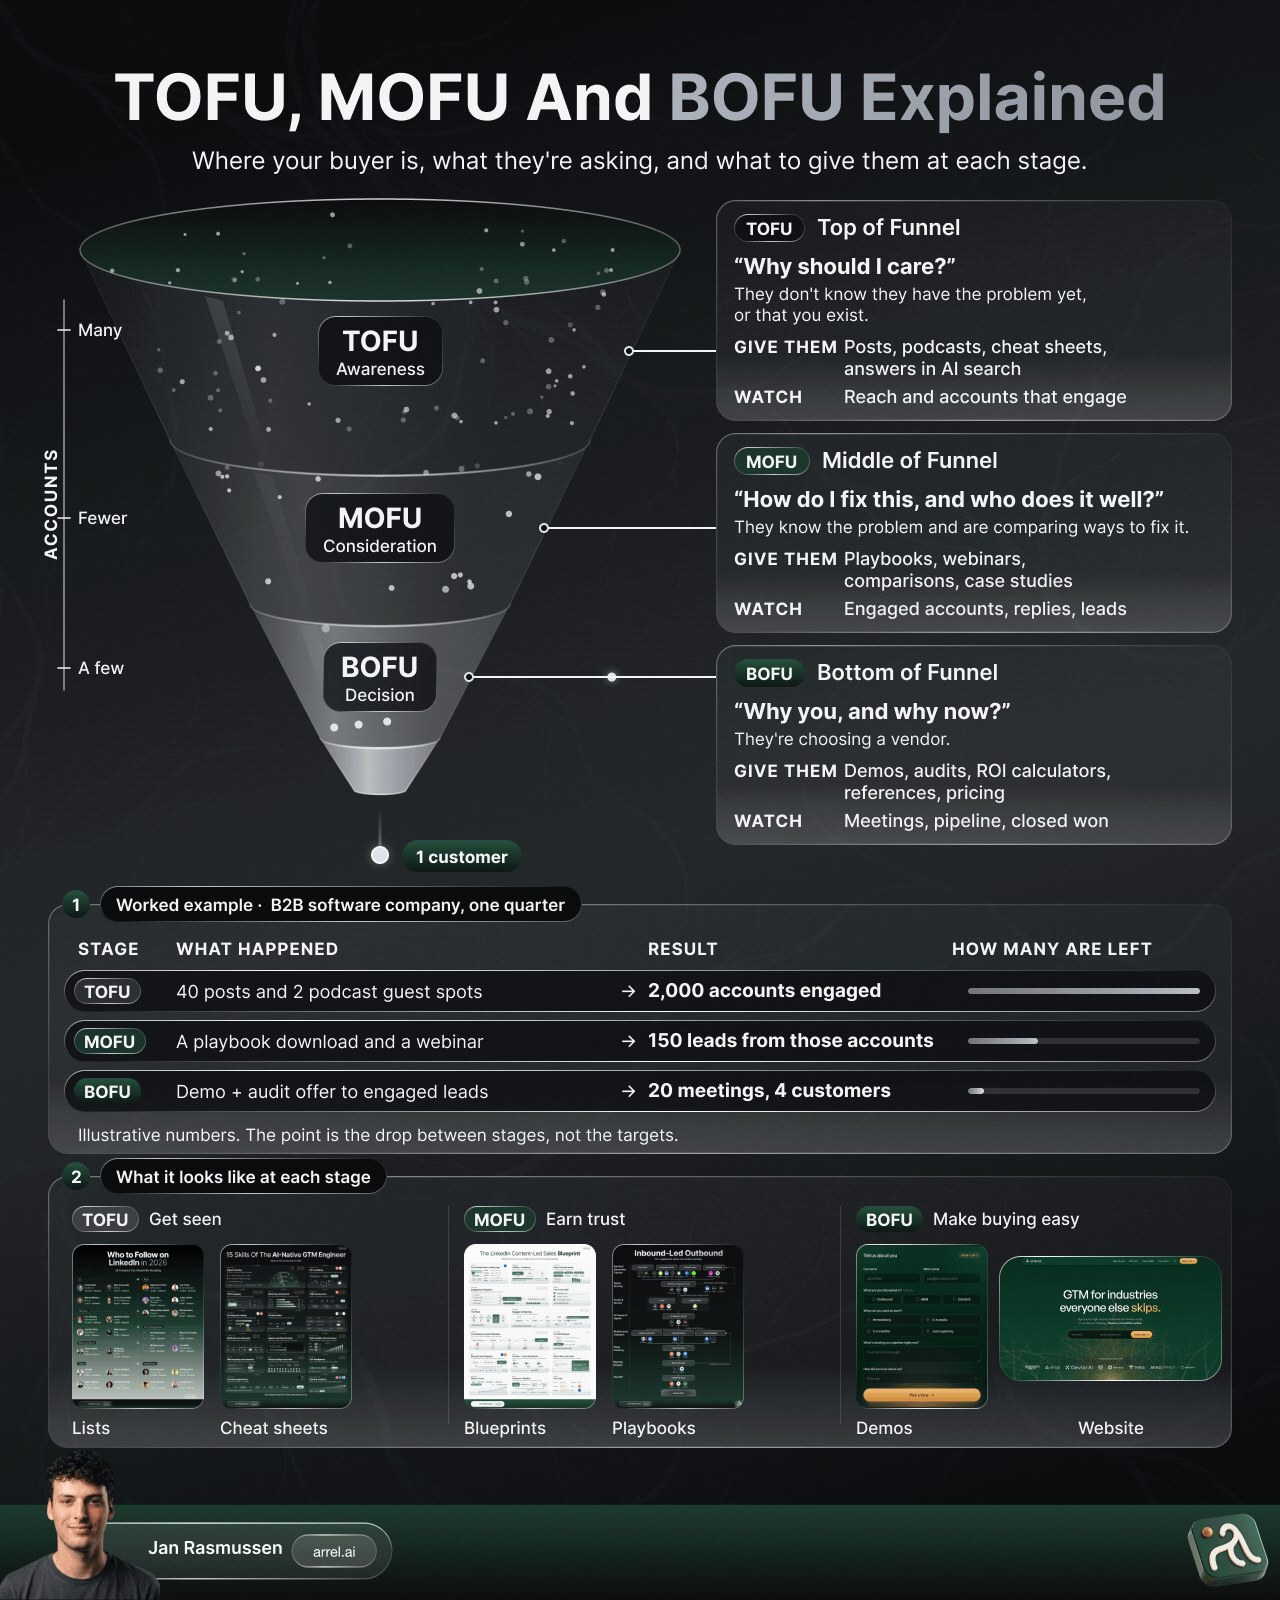
 Jan RasmussenRecommends matching content and metrics to three B2B buying stages: building awareness, earning trust, and making purchasing easy.
 564 interactions · 2d agoTrending Creator
 Lenny RachitskyShares Rob Snyder’s sales advice: investigate buying conditions, make outreach interesting, identify individual demand, and treat requests to proceed as stronger signals than enthusiasm.
 465 interactions · 2d agoTrending Creator
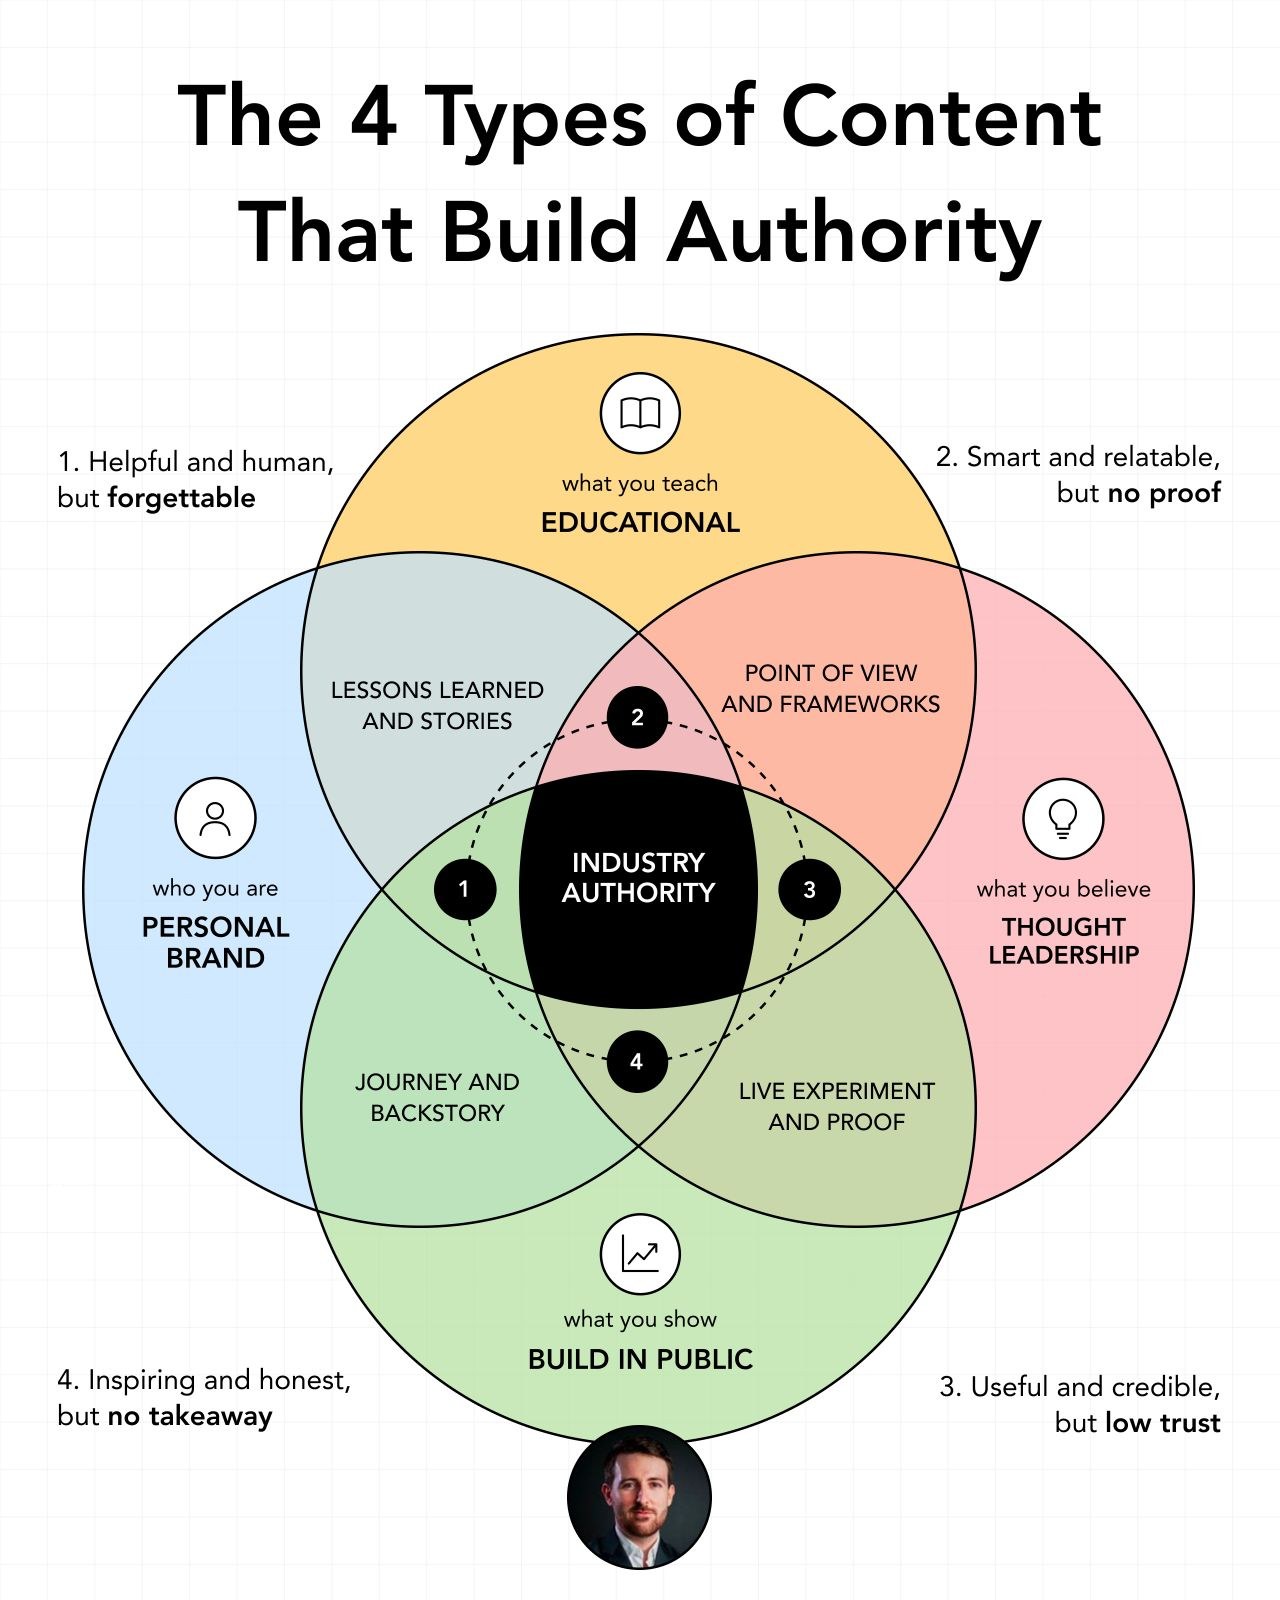
 Pierre HerubelArgues B2B founders build authority by consistently combining educational content, personal branding, building in public, and thought leadership, rather than selecting only some.
 356 interactions · 2d agoTrending topicForward Deployed Engineering+87.8% vs prior 30d · 0.9% of the conversationTrending topicCanva+77.7% vs prior 30d · 0.6% of the conversationTrending topicInfluencer Marketing & Creator Partnerships+70.0% vs prior 30d · 1.0% of the conversationTrending topicAI-Driven Advertising+60.7% vs prior 30d · 0.7% of the conversationTrending topicIn-Person Events & Field Marketing+50.3% vs prior 30d · 0.5% of the conversation
 Braze↑53 places in GTM Developer Tools
 Grok Bot↑3 places in Coding Agents & Harnesses for GTM
 Ploy↑26 places in AI-Native GTM Challengers
 Tavily↑36 places in GTM Developer Tools
 Lightfield↑19 places in AI-Native GTM Challengers
Trending Topics
 Brand+91.0%vs prior 30d0.3%share
Market Moves
 35,468 engagements · 2.1× usualPost ↗
 21 engagements · 0.3× usualPost ↗
 9 engagements · 1.1× usualPost ↗
 386 engagements · 3.5× usualPost ↗
 110 engagements · 3.7× usualPost ↗
 38 engagements · 1.1× usualPost ↗372 engagements · 16.2× usualPost ↗
GTM Tech Index
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
Featured trends
All topics
BetaFigures move as the panel grows and definitions sharpen.
+3.7%vs prior 30d+22.0%vs prior 30d-15.9%vs prior 30d+8.9%vs prior 30d-10.6%vs prior 30d+30.2%vs prior 30d -60.9%vs prior 30d-19.9%vs prior 30d+7.2%vs prior 30d
 +62.5%vs prior 30d+10.0%vs prior 30d+54.7%vs prior 30d+27.9%vs prior 30d-5.3%vs prior 30d+16.2%vs prior 30d+30.7%vs prior 30d+27.7%vs prior 30d-2.7%vs prior 30d±0%vs prior 30d+64.5%vs prior 30d
 +17.8%vs prior 30d
 -35.0%vs prior 30d+45.2%vs prior 30d+75.5%vs prior 30d+77.7%vs prior 30dNEWvs prior 30d+14.8%vs prior 30d+1.2%vs prior 30d-78.5%vs prior 30d+33.5%vs prior 30d+4.9%vs prior 30d+28.6%vs prior 30d-27.3%vs prior 30d-28.6%vs prior 30d+26.7%vs prior 30d-23.4%vs prior 30d-29.7%vs prior 30d
 -18.6%vs prior 30d+18.3%vs prior 30d-10.6%vs prior 30d
 -31.8%vs prior 30d+91.0%vs prior 30d
 +49.0%vs prior 30d+23.5%vs prior 30d
 -43.7%vs prior 30d
 -63.5%vs prior 30d
 -32.6%vs prior 30d
 +115%vs prior 30d+7.2%vs prior 30d
 -18.8%vs prior 30d
 -59.9%vs prior 30d
 -37.5%vs prior 30d
 +92.3%vs prior 30d
 +41.1%vs prior 30d
 -10.8%vs prior 30d
 -24.7%vs prior 30d-30.2%vs prior 30d
 -5.9%vs prior 30d
 +2.6%vs prior 30d
 -28.6%vs prior 30d-79.8%vs prior 30d-32.7%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
Building GTM Agents lost conversation share from April through September, apart from a small August bounce, and is down another 11.8% over the last 30 days. The posts offer no single cause for that decline; they show concrete work on deal timelines, business context and Zapier automations that run independently, even as the broader topic takes less space.
Posts to understand this
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 75 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Clay | 93 |
| 6 | HubSpot | 89 |
| 7 | Lovable | 61 |
| 8 | Salesforce | 94 |
| 9 | Replit | 56 |
| 10 | Instantly | 65 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO reached its high in June, alongside HubSpot’s concrete pitch: use AEO to get Loverboy into AI cocktail recommendations. Share then declined through September, but the last 30 days are up 13.1%; Kyle Poyar’s survey now puts AEO first for adoption growth, suggesting a shift from experimentation toward channel investment.
Posts to understand this · as of Oct 22
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Ahrefs | 51 |
| 3 | Semrush | 47 |
| 4 | HubSpot | 89 |
| 5 | Clay | 93 |
| 6 | Salesforce | 94 |
| 7 | Claude Code | 99 |
| 8 | AirOps | 41 |
| 9 | Grok Bot | 75 |
| 10 | Lovable | 61 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click discussion stayed large through July, eased in August and September, and is up 13.7% over the last 30 days. October’s posts reopen practical debates about LinkedIn links and gated-content incentives, while Wil Reynolds ties AI recommendations to accumulated brand authority. The pattern is a durable argument about how buyers discover brands, with renewed scrutiny of blanket channel rules.
Posts to understand this · as of Oct 26
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Semrush | 47 |
| 3 | Ahrefs | 51 |
| 4 | HubSpot | 89 |
| 5 | Clay | 93 |
| 6 | Claude Code | 99 |
| 7 | Salesforce | 94 |
| 8 | AirOps | 41 |
| 9 | Lovable | 61 |
| 10 | Grok Bot | 75 |
The people, tools and operating model behind custom go-to-market systems.
GTM Engineering climbed through May, then lost share each month through September; the last 30 days are down another 4.3%. Clay’s $115 million round did not interrupt that slide. The posts show a persistent build-your-own pattern beneath the decline: Clay’s internal pricing and rep tools, plus an agency run through GitHub repositories and Claude skills.
Posts to understand this · as of Oct 25
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 65 |
| 5 | Codex | 84 |
| 6 | Prospeo | 54 |
| 7 | Salesforce | 94 |
| 8 | HeyReach | 54 |
| 9 |  FullEnrich | 44 |
| 10 | AI Ark | 48 |
How software exposes its data and actions so agents can use it directly.
Headless and agent interfaces jumped in April and May, then held a higher baseline through September despite a gradual retreat. Cloudflare’s monetization gateway, Notion’s developer tools and Templafy’s MCP illustrate recurring product activity rather than one defining event; the latest 15% decline over 30 days shows that activity has not sustained the earlier share.
Posts to understand this · as of Oct 23
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Clay | 93 |
| 5 | Codex | 84 |
| 6 | Grok Bot | 75 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Instantly | 65 |
| 9 | Exa.ai | 49 |
| 10 | Lovable | 61 |
How teams use buyer signals to decide who to target, when and why.
Signal-based sales lost share through August, recovered in September, and is up 19.4% over the last 30 days while still down over 90 days. No single event explains the turn; the recurring thread is connecting signals to action, from April’s Claude Code and Trigify outbound workflows to Zoom’s October pitch for conversation intelligence and deal context.
Posts to understand this · as of Oct 27
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 65 |
| 6 | HeyReach | 54 |
| 7 | n8n | 59 |
| 8 | AI Ark | 48 |
| 9 | Codex | 84 |
| 10 | Nooks | 48 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
The July high coincided with Hugging Face amplifying a letter Nvidia signed in support of open models, followed by lower share in August and September. Mistral Large 4 and Kimi K3.1 Pro now give the debate fresh product evidence around sovereignty and claimed proprietary-model parity. Yet share is down 16.6% over the last 30 days despite those announcements.
Posts to understand this · as of Oct 24
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Grok Bot | 75 |
| 5 |  Together AI | 34 |
| 6 | OpenRouter | 52 |
| 7 | ElevenLabs | 56 |
| 8 | HubSpot | 89 |
| 9 | Salesforce | 94 |
| 10 | Vercel | 62 |
How companies prove AI delivers enough value to move beyond a pilot.
AI ROI held roughly 7–8% share from April through July, then fell in August and September; the last 30 days extend that decline by 13.6%. The evidence moves from OpenAI’s steep price cuts and cheaper model choices toward Decagon’s rollout discipline, with no single event explaining the drop: cost savings and operational proof remain recurring questions.
Posts to understand this · as of Oct 27
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Grok Bot | 75 |
| 5 | HubSpot | 89 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Nooks | 48 |
| 9 | Zapier | 54 |
| 10 | Gong | 64 |
How large companies move AI from small pilots into secure, useful production work.
Enterprise AI Adoption held around 6–7% through July, then declined through September; the last 30 days are down 7.2%. The posts move from Vanta’s AI-linked growth story and examples of AI supporting outbound teams to the difficulty of documenting processes before automation. That gives the conversation a concrete implementation thread, though it does not establish what caused attention to fade.
Posts to understand this · as of Oct 26
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | HubSpot | 89 |
| 5 | Grok Bot | 75 |
| 6 | Nooks | 48 |
| 7 | Zapier | 54 |
| 8 | Midjourney | 35 |
| 9 | Vercel | 62 |
| 10 | 1mind | 38 |
How teams create, distribute and judge marketing content made with AI.
AI Content’s August high gave way to a September drop, and share is down 14.7% over the last 30 days. Profound’s $180 million round and Higgsfield’s ChatGPT expansion did not sustain the August level. The posts frame a recurring tension rather than one clear cause: easier production and distribution meet teams’ limited capacity to review and use the output.
Posts to understand this · as of Oct 25
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Claude Code | 99 |
| 3 | Runway | 36 |
| 4 | Grok Bot | 75 |
| 5 | Clay | 93 |
| 6 | ElevenLabs | 56 |
| 7 |  HeyGen | 33 |
| 8 | HubSpot | 89 |
| 9 | Lovable | 61 |
| 10 | Codex | 84 |
How companies keep agents secure, accountable and under control as they take on real work.
Agent governance rose from 3.9% of conversation in March to 6.4% in July, then fell through September; its share dropped another 14.8% over the last 30 days. The selected posts frame the discussion around compromised evaluations, checking whether agents complete tasks correctly, and human approval before AI-built experiments go live.
Posts to understand this
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 75 |
| 4 | Salesforce | 94 |
| 5 | Clay | 93 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | HubSpot | 89 |
| 8 | ElevenLabs | 56 |
| 9 | OpenRouter | 52 |
| 10 | Vercel | 62 |
How AI changes what software companies build, charge for and deliver.
Conversation share peaked in May and declined through September, with another 5.9% decline over the last 30 days. ElevenLabs’ May price cuts supplied a concrete example of changing software economics, while Salesforce’s August results challenged the replacement thesis. The evidence shows competing arguments about pricing, incumbent durability and delivery models, rather than one event that explains the fade.
Posts to understand this · as of Oct 27
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Gong | 64 |
| 6 | Vercel | 62 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Nooks | 48 |
| 9 | Lovable | 61 |
| 10 | Codex | 84 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal Agents more than doubled their share from August to September, and the latest 30 days are up 115.4%. The posts show a shift from individual experiments, like Brian Halligan’s Hal, toward shared infrastructure: Meta and Sierra announced Personal Agent Protocol, while Stripe hosted a discussion of agents replacing web forms. That broader commercial scope gives the rise fresh material.
Posts to understand this · as of Oct 23
 XShared standardMeta and Sierra announce a standard for personal agents interacting with businessesS
 inCommerce discussionStripe hosts Zuckerberg and Wang for a discussion including agentic commerceBH
 inPersonal deploymentBrian Halligan’s Hal handles email, projects and participation in Zoom meetings
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 75 |
| 2 | Codex | 84 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | HubSpot | 89 |
| 6 | OpenClaw | 47 |
| 7 | Clay | 93 |
| 8 | Granola | 53 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Higgsfield | 38 |
How companies build trust and stand out when AI makes content cheap and abundant.
Brand & Authenticity held a broad conversation share through summer before a September drop; the latest 30 days are down 13.6%. The posts show a recurring concern rather than one launch: Handley challenged authenticity policing, Clay published an AI writing policy, and Herubel advocated visual frameworks and sales follow-ups as responses to crowded feeds.
Posts to understand this · as of Oct 21
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | Vercel | 62 |
| 6 | Codex | 84 |
| 7 |  Customer.io | 39 |
| 8 | Lovable | 61 |
| 9 | Gong | 64 |
| 10 | Grok Bot | 75 |
How AI changes software pricing, usage costs and gross margins.
Conversation share climbed through June, then declined through September; the last 30 days are down another 14%. No single post explains the retreat: OpenAI’s token price cuts, Peter Walker’s account of model competition, and Factory’s routing savings show a sustained cost-efficiency story even as the topic takes a smaller share of conversation.
Posts to understand this · as of Oct 23
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Codex | 84 |
| 5 | HubSpot | 89 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Grok Bot | 75 |
| 8 | Gong | 64 |
| 9 | Devin | 38 |
| 10 | Exa.ai | 49 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
Human experience held near 2.4–2.5% through the summer before a September drop; the last 30 days show a 7.8% recovery, still below the longer-term level. The pattern is a recurring argument for identifiable people behind marketing, rather than one launch. Wispr Flow’s founder content and Chris Donnelly’s account of winning Bugatti and Aston Martin give that argument concrete examples.
Posts to understand this · as of Oct 22
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Lovable | 61 |
| 5 | Apify | 52 |
| 6 | Customer.io | 39 |
| 7 | Instantly | 65 |
| 8 | Nooks | 48 |
| 9 |  Optimizely | 33 |
| 10 | Profound | 53 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR attention declined from March through July, rebounded in August, and remains below its spring levels despite a 6.5% lift over the last 30 days. The posts offer no single explanation for those swings, but show a more concrete recent conversation: ElevenLabs uses a voice SDR for inbound, while Clay introduced an agent that builds campaigns for human review.
Posts to understand this · as of Oct 24
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | Vercel | 62 |
| 6 | Exa.ai | 49 |
| 7 | Lovable | 61 |
| 8 |  Monaco | 28 |
| 9 |  Sumble | 34 |
| 10 | ElevenLabs | 56 |
How people and agents share work, hand off tasks and make decisions together.
After a May peak, conversation share settled near 2.1–2.2% from July through September, then fell 23.1% over the last 30 days. September posts featured shared team bots and Notion’s sub-agent handoffs; Seth London’s October proposal describes a personal assistant coordinating an agent bench as the broader conversation loses share.
Posts to understand this · as of Oct 24
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Attio | 51 |
| 6 | Grok Bot | 75 |
| 7 | Codex | 84 |
| 8 | Instantly | 65 |
| 9 | Vercel | 62 |
| 10 | Gong | 64 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context Engineering rose steadily through June, then declined through September; the last 30 days are down 9.9%. No single event explains the slide, but the posts move from a broad framework debate to specific plumbing. Charlie Hills argues for harness engineering, while Muesli routes transcripts into local context and ZoomInfo’s Exa integration adds company identity and buying signals.
Posts to understand this · as of Oct 25
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | Grok Bot | 75 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | ZoomInfo | 51 |
| 7 | Salesforce | 94 |
| 8 |  Clearskies | 23 |
| 9 | Gong | 64 |
| 10 | HubSpot | 89 |
Growth driven by people using the product before they talk to sales.
PLG’s share fell from 3.05% in March to 1.21% in July, then held near 1.4% in August and September. The last 30 days rose 19.4%, though the 90-day move remains negative. Clay’s combined product-led and sales-led approach, Metronome’s self-serve launch, and PostHog’s free plan illustrate the themes, but these posts do not establish what drove the recent gain.
Posts to understand this · as of Oct 22
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Claude Code | 99 |
| 5 | Codex | 84 |
| 6 | Cursor (Anysphere) | 77 |
| 7 |  Primer | 30 |
| 8 | Ahrefs | 51 |
| 9 | Intercom | 43 |
| 10 | Lovable | 61 |
How teams track and control the cost of models, tokens and agent work.
Token Spend & Cost Controls climbed from March through July, then declined through September; the latest 30 days are down 40%. The posts do not identify a single cause for the retreat: Rippling’s spend console, cheaper open-weight models and Rob Litterst’s account of Harvey’s margin problems all keep the discussion focused on measuring usage and choosing models by cost.
Posts to understand this
 inMargin pressureRob Litterst reports Harvey’s margin deterioration and move toward open-weight AIPW
 inModel economicsPeter Walker connects rising token usage with model diversity and cheaper open weightsR
 inSpend visibilityRippling introduces AI Spend Console with usage data from OpenAI, Anthropic and Cursor
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 75 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Salesforce | 94 |
| 6 | Clay | 93 |
| 7 | HubSpot | 89 |
| 8 | ElevenLabs | 56 |
| 9 | Intercom | 43 |
| 10 | Baseten | 44 |
Low-quality AI content and the fight to make automated work worth reading.
AI slop held near 2% of conversation from April through August, a durable plateau rather than a single-event spike. The posts show repeated friction over empty content, authorship policing and the work required to get useful output from Claude. September broke below that range, and share is down another 11.4% over the last 30 days as practical setup advice joins the complaints.
Posts to understand this · as of Oct 27
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 75 |
| 3 | Codex | 84 |
| 4 | Apify | 52 |
| 5 | Exa.ai | 49 |
| 6 | HubSpot | 89 |
| 7 | Instantly | 65 |
| 8 | Substack | 51 |
| 9 | Clay | 93 |
| 10 | Customer.io | 39 |
The argument that agents and custom software will break the classic SaaS model.
SaaSpocalypse attention roughly halved from March to August, barely moved in September, and is down another 44.3% over the last 30 days. The posts show rebuttal rather than a fresh collapse thesis: Salesforce cites revenue growth, growing seats and low attrition, while Dave Kellogg calls it a “renaisaas.” That pattern fits a debate losing momentum, without proving why it faded.
Posts to understand this · as of Oct 26
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Monaco | 28 |
| 5 | Vercel | 62 |
| 6 | Gong | 64 |
| 7 | Apify | 52 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Nooks | 48 |
| 10 | ZoomInfo | 51 |
The choice between building software internally and buying another product.
Build vs. Buy lost share through July, then held roughly level in August and September; the latest 30 days are down 28.7%. The posts move from Vercel’s broad claim that companies buy less software to Replit’s concrete example of a salesperson building tools. Intercom’s renewed help desk investment supplies the counterweight: internal builds and purchased workflows still coexist.
Posts to understand this · as of Oct 23
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Monaco | 28 |
| 5 | Vercel | 62 |
| 6 | Apify | 52 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Nooks | 48 |
| 9 | Profound | 53 |
| 10 |  Qualified | 27 |
Ways to verify whether digital content or online activity came from a person or AI.
Proof of Human spiked to 1.1% in August as Anthropic explained its watermarking plans and marketers debated disclosure. September’s retreat and a 28.4% decline over the last 30 days fit a concentrated controversy rather than a sustained climb. The follow-up discussion centers on what watermarks actually establish and whether AI detection says anything useful about content quality.
Posts to understand this · as of Oct 26
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 75 |
| 2 | Codex | 84 |
| 3 | Claude Code | 99 |
| 4 | HeyGen | 33 |
| 5 | Instantly | 65 |
| 6 | Apify | 52 |
| 7 | Exa.ai | 49 |
| 8 | Higgsfield | 38 |
| 9 | HubSpot | 89 |
| 10 |  People Data Labs | 24 |
AI tools that write, edit, test and operate software alongside a human builder.
Coding agents lost share from March through July, briefly recovered in August, then slipped again in September; the last 30 days are down 15.1%. The evidence spans ColdIQ’s ad operations and Notion’s workspace-as-code beta, alongside Tyler Denk’s costly custom software experience. Practical applications coexist with maintenance costs, without one event that explains the decline.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 75 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Clay | 93 |
| 6 | HubSpot | 89 |
| 7 | Lovable | 61 |
| 8 | Replit | 56 |
| 9 | Salesforce | 94 |
| 10 | Instantly | 65 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO held near its May high through July before losing share in August and September; the last 30 days show a 9.5% recovery. The posts offer no single explanation for that arc, but show a practical debate over citation evidence, SEO fundamentals and attribution, with Ethan Smith’s reported ChatGPT tracking bug adding a fresh measurement problem.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Semrush | 47 |
| 3 | Ahrefs | 51 |
| 4 | HubSpot | 89 |
| 5 | Clay | 93 |
| 6 | AirOps | 41 |
| 7 | Claude Code | 99 |
| 8 | Salesforce | 94 |
| 9 | Lovable | 61 |
| 10 | Grok Bot | 75 |
The frontier models and labs that provide the base layer for AI products.
Foundation models moved in waves, with July and September highs followed by a 47.3% decline over the last 30 days. The posts show several sources of attention: Anthropic’s Project Glasswing, permanent Sonnet 5 pricing, and OpenAI’s Google Cloud expansion. That mix supports a recurring product and distribution cycle, but does not explain September’s high on its own.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 75 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Midjourney | 35 |
| 6 | Salesforce | 94 |
| 7 | OpenRouter | 52 |
| 8 | Granola | 53 |
| 9 | HubSpot | 89 |
| 10 | OpenClaw | 47 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP nearly doubled its share from March to May, with Salesforce’s Agent Fabric pitch placing agent discovery, cost controls and governance in the spring conversation. Later ElevenLabs and Databox releases supplied specific uses, but share settled below May’s high and is down 10% over the last 30 days: continued product delivery without renewed acceleration.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | Codex | 84 |
| 5 | Clay | 93 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Grok Bot | 75 |
| 8 | Instantly | 65 |
| 9 | Lovable | 61 |
| 10 | Gong | 64 |
Measuring whether AI answers mention, cite and recommend a brand.
AI Visibility climbed to a June high, held near that level through August, then dropped in September; the last 30 days are up 23.4%. No single event explains that rebound: the posts show a recurring tension between demand to shape AI brand descriptions and doubts that prompt tracking reliably measures or improves visibility.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Semrush | 47 |
| 3 | AirOps | 41 |
| 4 | Vercel | 62 |
| 5 | Ahrefs | 51 |
| 6 | Clay | 93 |
| 7 | Peec AI | 30 |
| 8 | HubSpot | 89 |
| 9 |  Similarweb | 31 |
| 10 | Claude Code | 99 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid Media’s August lift gave way to a September dip, but its latest 30-day share is up 38.6%. The October posts pair cost pressure with practical controls: Northbeam reports Meta CPMs up 25% year over year, while Ira Bodnar describes Claude workflows for creative, audits and budgets. Clay’s August customer results add an earlier thread around better audiences and lower acquisition costs.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 65 |
| 6 | Codex | 84 |
| 7 | RB2B | 47 |
| 8 | Gong | 64 |
| 9 | Lovable | 61 |
| 10 | Primer | 30 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
Enterprise AI’s April high coincided with Mistral’s Workflows preview, backed by named users including ASML and ABANCA. Share declined through September and is now roughly flat over the last 30 days, down 0.3%; the recurring thread is the work between model capability and business value, from reliable production processes to trusted data and adoption.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Grok Bot | 75 |
| 5 | HubSpot | 89 |
| 6 | Nooks | 48 |
| 7 | Zapier | 54 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Gong | 64 |
| 10 | 1mind | 38 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps lost share from March through August, then held nearly flat in September; the last 30 days show a modest 3.9% lift. The posts offer no single cause for the decline, but a consistent debate about who should do systems work. Apollo’s Pocus acquisition, warnings about homemade SaaS replacements, and Claude-based Salesforce forecasting all address the cost of operational friction.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 65 |
| 6 | n8n | 59 |
| 7 | Gong | 64 |
| 8 | Nooks | 48 |
| 9 | Codex | 84 |
| 10 | HeyReach | 54 |
Email sent to people with no prior relationship to start a sales conversation.
Cold email peaked in May, when Jason Bay reported a jump from roughly 1% replies through a sequencer to 15%+ positive replies from his inbox. Share settled near 3.2–3.4% from July through September and is down 16% over the last 30 days. The recurring thread is practical troubleshooting: delivery, relevance and giving someone a reason to reply.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | Instantly | 65 |
| 4 | HubSpot | 89 |
| 5 | Smartlead | 47 |
| 6 | Prospeo | 54 |
| 7 | Salesforce | 94 |
| 8 | Codex | 84 |
| 9 | Grok Bot | 75 |
| 10 | HeyReach | 54 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Prospecting rose through May, settled into a lower summer plateau, then slipped in September; the last 30 days show a modest 4.1% recovery. No single post explains the full curve. Nooks and Clay established the broader workflow theme before this window, while October’s Moltsets announcement puts a concrete price challenge into the conversation: unlimited B2B contacts for $27 a month.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 65 |
| 5 | Salesforce | 94 |
| 6 | AI Ark | 48 |
| 7 | HeyReach | 54 |
| 8 |  Findymail | 43 |
| 9 | Prospeo | 54 |
| 10 | Nooks | 48 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer success declined from March through July, briefly recovered in August and slipped again in September; the last 30 days are up 10.3%. The evidence spans Rox’s automated renewals launch, a Salesforce support complaint and Higgsfield’s hands-on expansion model. Higgsfield’s October account of a $99 user becoming a $6 million annual customer gives the current rebound a concrete example, without proving its cause.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Claude Code | 99 |
| 5 | Gong | 64 |
| 6 | Lovable | 61 |
| 7 | Vercel | 62 |
| 8 | Grok Bot | 75 |
| 9 | Monaco | 28 |
| 10 | Replit | 56 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold outbound’s share fell in April, rebounded in May, then declined each month through September; the last 30 days show a modest 2.8% lift. The posts span Nooks expanding into sequencing, Origami automating lead generation, and Jaleh Rezaei sharing why buyers dismiss cold calls, showing both automation launches and practical call advice within a shrinking conversation.
Posts to understand this · as of Oct 22
 inOutbound sequencingNooks launches AI Sequencing for list building, account research, and emailsJR
 inBuyer attentionJaleh Rezaei shares Kyle Norton’s approach to overcoming automatic cold-call dismissalFM
 inLead generationOrigami launches AI lead generation with prompting, list feedback, and messaging
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 65 |
| 6 |  BetterContact | 43 |
| 7 | HeyReach | 54 |
| 8 | Prospeo | 54 |
| 9 | Lemlist | 49 |
| 10 | Findymail | 43 |
Voice and chat software that talks with buyers and customers.
Conversational AI rose gradually through August, held near 2% in September, and is up 25.6% over the last 30 days. Mistral’s Voxtral 3 and ElevenLabs’ Eleven Realtime launches give the latest lift concrete product news. The earlier Salesloft handoff from Drift to 1mind adds a buyer-facing adoption story to the speech-model releases.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 75 |
| 2 | HubSpot | 89 |
| 3 | ElevenLabs | 56 |
| 4 | Salesforce | 94 |
| 5 | Clay | 93 |
| 6 |  Docket | 32 |
| 7 |  Vector | 35 |
| 8 | Attio | 51 |
| 9 |  Twilio | 42 |
| 10 |  11x | 24 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand Generation’s share roughly halved between March and September, with an August bounce that did not hold; the last 30 days are down another 3.9%. No single event explains the decline. The posts share a practical concern: AI changes how buyers find information, while Inflection.io and Webflow Campaigns address limits in marketing platforms and campaign production.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Codex | 84 |
| 6 | Gong | 64 |
| 7 | Docket | 32 |
| 8 | Instantly | 65 |
| 9 | Smartlead | 47 |
| 10 | ZoomInfo | 51 |
The work of connecting marketing activity to pipeline and revenue.
Attribution settled into a lower August and September plateau, but attention is up 42.1% over the last 30 days. The recurring thread is measurement losing sight of buyer behavior: n8n’s zero-click conversions, Adam Holmgren’s case for correlation over credit, and October scrutiny of Google’s AI-sharing plans. Those plans give an existing debate a fresh trigger.
Posts to understand this · as of Oct 26
 inMeasurement argumentAdam Holmgren argues attribution should connect buyer engagement with later pipelineES
 inAttribution gapn8n case study uses self-reported attribution to capture zero-click AI discoveryES
 inSearch shiftGoogle job description prompts questions about attribution for shared AI answers
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | Gong | 64 |
| 5 | Semrush | 47 |
| 6 | Docket | 32 |
| 7 | Claude Code | 99 |
| 8 | Grok Bot | 75 |
| 9 | Instantly | 65 |
| 10 | Similarweb | 31 |
Sales and marketing coordinating around a defined set of target accounts.
ABM settled near 2% of conversation in April–June, dipped in July, then held around 1.8% in August–September; the last 30 days are up 19.4%. Vector’s September launch gives the recent discussion a concrete focus on contact-level signals and measurable deal influence, while Clay’s earlier ads beta reflects the same push toward audiences sellers can act on.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Instantly | 65 |
| 5 | Claude Code | 99 |
| 6 | 6sense | 42 |
| 7 | HeyReach | 54 |
| 8 | Nooks | 48 |
| 9 | Findymail | 43 |
| 10 | AI Ark | 48 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Data enrichment lost share from March through September, apart from a May bounce; the last 30 days show a 10.9% recovery. Clay’s March data price cuts and October’s Gong Enrich launch frame a shift toward enrichment inside broader GTM workflows. Gong’s earlier RightBound acquisition supplies background to that pattern, rather than an explanation for this period’s decline.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 65 |
| 5 | HeyReach | 54 |
| 6 | RB2B | 47 |
| 7 | Prospeo | 54 |
| 8 | n8n | 59 |
| 9 | AI Ark | 48 |
| 10 | Findymail | 43 |
Mapping and winning the committee of people involved in a business purchase.
Buying-group discussion drifted lower after March, with a May rebound and a lower August–September plateau; the last 30 days are up 23.5%, despite a 20.4% decline over 90 days. The evidence shows a recurring operational concern, not one catalyst: Clay’s executive outreach, Gal Aga’s emphasis on internal consensus, and Jon Miller’s critique of automation built around individual leads.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 65 |
| 6 | HeyReach | 54 |
| 7 | Nooks | 48 |
| 8 | RB2B | 47 |
| 9 | Exa.ai | 49 |
| 10 | Vector | 35 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability climbed to a May high, then fluctuated below it; no single post explains that spike. The recurring pattern is infrastructure investment alongside skepticism about how deliverability gets sold, from Infobip’s SocketLabs acquisition to criticism of fear-based pitches. Resend’s Forge launch adds a concrete announcement as share rises 10.3% over the last 30 days.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Instantly | 65 |
| 4 | Claude Code | 99 |
| 5 | Prospeo | 54 |
| 6 | Lemlist | 49 |
| 7 | Salesforce | 94 |
| 8 | Smartlead | 47 |
| 9 | AI Ark | 48 |
| 10 | Codex | 84 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Evals and benchmarks climbed to a July high, settled near 2.1% in August and September, and are down 15.8% over the last 30 days. The posts do not identify a single cause for the retreat. They show a varied testing agenda: Anthropic’s compromised benchmark example, Optimizely’s marketing benchmark and a coordinate-based geography test.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 75 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | OpenRouter | 52 |
| 6 |  Cline | 31 |
| 7 | Devin | 38 |
| 8 | Salesforce | 94 |
| 9 | Clay | 93 |
| 10 | ElevenLabs | 56 |
Programmable tools used to build custom go-to-market systems, agents and automations.
GTM Developer Tools climbed from 0.84% in March to a May high of 2.54%, alongside posts about reusable Claude skills and Claude Code integrations across the GTM stack. Share then retreated through August; the last 30 days are nearly flat at +0.6%. October’s detailed stack playbook continues the practical systems theme, but offers no evidence of a fresh breakout.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Instantly | 65 |
| 3 | Prospeo | 54 |
| 4 | HubSpot | 89 |
| 5 | Claude Code | 99 |
| 6 | FullEnrich | 44 |
| 7 | HeyReach | 54 |
| 8 | Findymail | 43 |
| 9 | AI Ark | 48 |
| 10 | RB2B | 47 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
AI video jumped in August and held that higher share in September, alongside fal’s live generation launch and HeyGen’s research on business owners’ reluctance to publish video. That plateau spans both technical capability and a practical customer problem. Higgsfield’s OpenAI marketplace entry adds a purchasing route, though the last 30 days are down 9.1%.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Runway | 36 |
| 3 | ElevenLabs | 56 |
| 4 | HeyGen | 33 |
| 5 | Claude Code | 99 |
| 6 | Grok Bot | 75 |
| 7 | Replit | 56 |
| 8 | Canva | 50 |
| 9 | Clay | 93 |
| 10 | Exa.ai | 49 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
GTM Data Infrastructure nearly regained its March share in June, then declined through September and another 11.1% over the last 30 days. March’s evidence pairs Pocus joining Apollo with a Databricks report on unified data architecture. The later Mobi Solutions acquisition brings the discussion down to implementation and cleanup, but the posts do not explain June’s bounce.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 65 |
| 6 | n8n | 59 |
| 7 |  GrowthLoop | 29 |
| 8 | Nooks | 48 |
| 9 | HeyReach | 54 |
| 10 | Attio | 51 |
People asking AI assistants for answers instead of using a traditional search engine.
AI search conversation climbed to a June high, then declined through September and remains down 3.4% over the last 30 days. The posts trace a debate from AutoRFP’s reported ChatGPT lead gains to AI citations surviving Google de-indexing and concerns about lost organic clicks. That gives the curve a recurring discovery-and-measurement theme, without a single documented catalyst.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 47 |
| 2 | Clay | 93 |
| 3 | Profound | 53 |
| 4 | Salesforce | 94 |
| 5 | Ahrefs | 51 |
| 6 |  SparkToro | 28 |
| 7 | 6sense | 42 |
| 8 |  CallRail | 24 |
| 9 | Claude Code | 99 |
| 10 | Exa.ai | 49 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise sales has generally lost share since March, with intermittent rebounds rather than a steady recovery; the last 30 days are up 17.2%. Late-September posts supply concrete expansion stories: Clay’s million-dollar enterprise sellers and Higgsfield’s account of moving from consumer adoption into business workflows. Those examples give the current lift substance, though they do not establish a single cause.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | HubSpot | 89 |
| 5 | Gong | 64 |
| 6 | 6sense | 42 |
| 7 |  Klaviyo | 39 |
| 8 | Lemlist | 49 |
| 9 | Nooks | 48 |
| 10 | Profound | 53 |
The choice of go-to-market motion and the plan for making it work.
GTM strategy reached similar highs in March and May before a broad retreat through September; the last 30 days show a modest 8% recovery against a 35.8% 90-day decline. The posts offer successive operating questions rather than one sustained catalyst: Swan AI’s agent-run motion, Notion’s builder-led account ownership, and May Petry’s discussion of buyers who delegate research to agents.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Nooks | 48 |
| 5 | Gong | 64 |
| 6 | AI Ark | 48 |
| 7 |  Demandbase | 34 |
| 8 | Findymail | 43 |
| 9 | BetterContact | 43 |
| 10 | Instantly | 65 |
The debate over AI risk, alignment, regulation and responsible development.
AI Safety’s September spike coincided with a concentrated burst of corporate positions: Microsoft on superintelligence serving humanity, Databricks’ Ali Ghodsi downplaying existential risk, and Mercor committing $5 million to safety research. That mix of disagreement and funding gives the spike a concrete focus. Share is down 25.2% over the last 30 days, though still up 92.6% over 90 days.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 75 |
| 4 | Midjourney | 35 |
| 5 | Granola | 53 |
| 6 | beehiiv | 51 |
| 7 | Attio | 51 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | ElevenLabs | 56 |
| 10 | HubSpot | 89 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product marketing fell sharply after March, held roughly steady in May–June and then drifted lower; the last-30-day move is down 7.9%. April’s concrete news concerned the marketing engineer role at Profound and Google, with agents taking on competitive tracking and sales materials. The later defense of PMM’s launch work shows a recurring debate over who owns the work, not a single event behind the decline.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
| 5 | Gong | 64 |
| 6 | Ploy | 31 |
| 7 | Codex | 84 |
| 8 | FullEnrich | 44 |
| 9 | Primer | 30 |
| 10 | Profound | 53 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search strategy nearly doubled from April to June, then declined through September; the last 30 days remain down 6.1%. The posts show a shift in emphasis rather than a single catalyst: Ryan Law’s AI-native content workflow, scrutiny of citation metrics, and Austin Armstrong’s combined SEO and AEO plan. The common problem is how to connect discovery work to useful outcomes.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Semrush | 47 |
| 3 | Ahrefs | 51 |
| 4 | AirOps | 41 |
| 5 | Codex | 84 |
| 6 | HubSpot | 89 |
| 7 | Instantly | 65 |
| 8 |  Ranked AI | 33 |
| 9 | Similarweb | 31 |
| 10 | SparkToro | 28 |
The training, fine-tuning and modeling work underneath AI products.
Machine Learning rose steadily from June through September and remains up 2.5% over the last 30 days, with a 28.6% gain over 90 days. The evidence spans several sources of attention: Skild AI’s one-example robot model, World Labs’ announcement that it would join AMD, and Meta’s training infrastructure. That breadth fits a sustained rise better than a single launch spike.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 75 |
| 4 | Baseten | 44 |
| 5 | Cline | 31 |
| 6 | HubSpot | 89 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Midjourney | 35 |
| 9 |  Modal | 39 |
| 10 | Clay | 93 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence has struggled to hold its rebounds: July's recovery gave way to lower share in August and September. The last 30 days are up 28.2%, but the 90-day move remains negative. No single post explains that bounce; Outreach's orchestration pitch, Claude discovery audits and a transcript-fed RevOps copilot share a pattern of putting call analysis into broader revenue work.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Clay | 93 |
| 5 | Claude Code | 99 |
| 6 | Vercel | 62 |
| 7 | n8n | 59 |
| 8 | Instantly | 65 |
| 9 |  Salesloft | 40 |
| 10 | Zapier | 54 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Revenue Agents reached their highest share in April, alongside Fin’s sales-role launch, then declined through August. September brought a small lift, and the last 30 days are up 4.4%, against a 36.7% decline over 90 days. Ami’s launch critiques earlier AI SDR failures, while Nooks emphasizes rep collaboration and reported pipeline gains: a more specific case for adoption.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | Nooks | 48 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 89 |
| 6 | Exa.ai | 49 |
| 7 | Lovable | 61 |
| 8 | Sumble | 34 |
| 9 |  Attention | 28 |
| 10 | Clearskies | 23 |
How companies create demand, build trust and reach buyers at other businesses.
B2B marketing fell from its March high, briefly recovered in June, then declined through September; the last 30 days show a modest 4.1% lift. No single event accounts for the curve. The recurring thread is distribution through people: Salesforce’s reported MrBeast partnership, Kieran Flanagan’s creator and employee playbook, and October’s argument for spreading visibility beyond the founder.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Salesforce | 94 |
| 4 | Customer.io | 39 |
| 5 | Ahrefs | 51 |
| 6 | Claude Code | 99 |
| 7 | Demandbase | 34 |
| 8 | Gong | 64 |
| 9 | Optimizely | 33 |
| 10 | Primer | 30 |
The durable knowledge and memory an agent can use across tasks and sessions.
Conversation share rose to a June peak, then fell through September. It is up 10.9% over the last 30 days, but remains down 32% over 90 days. The selected posts focus on making internal knowledge usable: meeting transcripts stored as context, warehouses grounding agents in business logic, and the Workbounce acquisition as a recent example.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Grok Bot | 75 |
| 3 | ZoomInfo | 51 |
| 4 | Claude Code | 99 |
| 5 | Salesforce | 94 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Clearskies | 23 |
| 8 | Gong | 64 |
| 9 |  Octave | 31 |
| 10 | Codex | 84 |
How companies sell to other companies and how business buyers make decisions.
B2B Sales lost share from May through September apart from a small August bounce, but the latest 30 days are up 33.5%. No single launch explains the rebound; the posts share a focus on buyer needs, from researched outreach and Aligned’s deal workspaces to Morgan J Ingram’s September account of sellers returning to events, personal notes and face-to-face meetings.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
| 5 | 6sense | 42 |
| 6 |  DemandScience | 27 |
| 7 | Hermes Agent | 36 |
| 8 | OpenClaw | 47 |
| 9 | Primer | 30 |
| 10 | Webflow | 47 |
B2B brands paying creators and independent voices to reach trusted audiences.
Conversation share seesawed through spring and summer, dipped in September, then rebounded 70% over the last 30 days, leaving the 90-day change at just 3.5%. Recent posts put concrete results behind that rebound: Limelight reports $3 million paid to B2B creators, one sales creator reached six figures in brand deals, and beehiiv credits its creator program as a major growth lever.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | ElevenLabs | 56 |
| 4 | Lovable | 61 |
| 5 | Primer | 30 |
| 6 | Replit | 56 |
| 7 | AirOps | 41 |
| 8 | Claude Code | 99 |
| 9 | Gamma | 45 |
| 10 | Ploy | 31 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales leadership reached its highest share in April and May, with Replit’s Ghazi Masood arguing that leaders must recruit, coach, prospect and close. Attention dropped sharply in June and softened through September, though the last 30 days are up 10.4%. The continuing thread is talent development: spotting potential early and keeping reps long enough to build expertise.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Gong | 64 |
| 5 | Claude Code | 99 |
| 6 | Codex | 84 |
| 7 | Attio | 51 |
| 8 | Demandbase | 34 |
| 9 | ElevenLabs | 56 |
| 10 | Grok Bot | 75 |
Starting and running a business, including the economics and experience of the founder path.
Entrepreneurship’s August bounce coincided with YouSpot’s solo CRM launch and Alex Lieberman’s bootstrapped hiring update, but September gave back ground and the last 30 days are down 22.3%. No single event explains the decline; the recurring thread is business economics, from tools for one-person operators to Tally’s $6 million ARR with ten people.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Smartlead | 47 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 51 |
| 6 | Grok Bot | 75 |
| 7 | HeyReach | 54 |
| 8 | Instantly | 65 |
| 9 | OpenClaw | 47 |
| 10 | Zapier | 54 |
Scoring leads and accounts to decide who deserves attention first.
Lead scoring peaked in March and May, then declined through September; its 48% rise over the last 30 days is a rebound within a broader retreat, with the last 90 days still down 43.9%. The selected posts connect scoring to concrete choices: which conference attendees to contact, which accounts to prioritize, and how to connect account scores to research and outreach.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Salesforce | 94 |
| 4 | Instantly | 65 |
| 5 | Claude Code | 99 |
| 6 | Gong | 64 |
| 7 | RB2B | 47 |
| 8 | Codex | 84 |
| 9 | HeyReach | 54 |
| 10 | Lemlist | 49 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth Marketing fell sharply after March, then settled around 1% or less from June through September; the last 30 days are down another 5.2%. No single event explains the drop: the posts trace a shift toward specific operating methods, from Clay Ads’ automated audiences to GTM engineering and focused executive LinkedIn programs.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Primer | 30 |
| 5 | Codex | 84 |
| 6 | Ploy | 31 |
| 7 | Grok Bot | 75 |
| 8 | Salesforce | 94 |
| 9 | Ahrefs | 51 |
| 10 | Vercel | 62 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Conversation share climbed through May, then declined through September; the last 30 days show a 79.7% rebound. The recurring tension is whether forward deployed engineering means real integration work or renamed services: Halligan questions the label, while StackAI describes engineers who connect legacy systems and deliver three production use cases over three to six months.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Braze | 37 |
| 4 | Nooks | 48 |
| 5 | Clay | 93 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Gong | 64 |
| 9 | AirOps | 41 |
| 10 |  Consensus | 27 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement’s uneven decline included a July bounce before further losses in August and September; the last 30 days are up 5%. No single event explains those turns. The posts share a demand for practical rep development, from Vanta’s reported Hyperbound ramp-time gains to Todd Busler’s October critique of unread playbooks; Jen Allen-Knuth’s earlier account supplies context on neglected fundamentals.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 |  Highspot | 29 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Clay | 93 |
| 6 |  Seismic | 29 |
| 7 | Customer.io | 39 |
| 8 |  Mutiny | 31 |
| 9 | Salesforce | 94 |
| 10 | Salesloft | 40 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing held near its May high in June, when GrowthX announced GrowthOS, then weakened unevenly before a sharp September drop; the last 30 days are down 5.8%. The posts suggest a shift in debate, not a single cause for the decline: June’s workflow automation pitch gives way to criticism of content quotas and arguments for original ideas and creator programs.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 47 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Customer.io | 39 |
| 5 | HubSpot | 89 |
| 6 | Ahrefs | 51 |
| 7 | Codex | 84 |
| 8 | Grok Bot | 75 |
| 9 | Optimizely | 33 |
| 10 | AirOps | 41 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Executive and employee social held near a steady share from April through August, then dropped in September; the last 30 days show a 38.2% recovery, with the 90-day move still negative. The recurring thread is distribution through people: Clay reported 4,756 livestream registrations from one post, while October posts pair Wispr Flow's founder approach with a case for broader employee participation.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Apify | 52 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 65 |
| 5 | Lovable | 61 |
| 6 | HeyReach | 54 |
| 7 | AirOps | 41 |
| 8 |  Chili Piper | 36 |
| 9 | Claude Code | 99 |
| 10 | Docket | 32 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Partner Marketing stepped up in August and held nearly that share in September; the last 30 days are up 18.5%. The pattern is repeated investment in partner distribution, rather than one announcement. Lovable formalized certification, referrals and revenue share, Sierra introduced its ecosystem, and Will Taylor argued that predictable partner pipeline requires ongoing demand generation.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Instantly | 65 |
| 5 | Gong | 64 |
| 6 | HeyReach | 54 |
| 7 | Lovable | 61 |
| 8 | Webflow | 47 |
| 9 | Claude Code | 99 |
| 10 | Grok Bot | 75 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting peaked in May, then lost share unevenly through September; the last 30 days are down another 28.1%. No single event explains that retreat: the posts pair ROX and HockeyStack’s revenue-agent announcements with Chris Orlob’s practical warning about a $40,000 deal. The recurring issue is whether automated forecasts or buyer commitments can be trusted.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Gong | 64 |
| 5 | n8n | 59 |
| 6 | Claude Code | 99 |
| 7 | Instantly | 65 |
| 8 | Intercom | 43 |
| 9 | Chili Piper | 36 |
| 10 |  Fireflies | 39 |
A go-to-market operating model where agents execute work across the revenue motion.
Agentic GTM’s uneven spring gave way to a higher August and September baseline, with share up 32.1% over the last 30 days. The posts trace a concrete progression from redesigned marketing teams to Clay’s $115 million funding round and Hightouch’s message-delivery launch. The common thread is agents taking responsibility for more steps across a revenue or marketing workflow.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Attio | 51 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
| 5 | Claude Code | 99 |
| 6 | ZoomInfo | 51 |
| 7 | 6sense | 42 |
| 8 | Apollo.io | 50 |
| 9 | Codex | 84 |
| 10 | RB2B | 47 |
The point where a product solves a real need for a market that will buy it.
Conversation peaked in April, fell through July, and then stayed below its spring level, with an 8.8% lift over the last 30 days. The selected posts focus on how companies prove fit through repeat usage, retention, and revenue, and why changing AI expectations can force them to prove it again.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Gamma | 45 |
| 5 | Lemlist | 49 |
| 6 | Nooks | 48 |
| 7 | Profound | 53 |
| 8 | Salesforce | 94 |
| 9 | AI Ark | 48 |
| 10 | Ahrefs | 51 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent skills peaked in May, when one practitioner described Claude Code skills supporting more than $300,000 in monthly ad spend, then faded through September. Share is now up 12.1% over the last 30 days, within a broader 90-day decline. Vercel’s plugin standard and an October OKR skill show a recurring pattern of infrastructure releases and reusable work routines.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | Codex | 84 |
| 4 | HubSpot | 89 |
| 5 | Salesforce | 94 |
| 6 | Firecrawl | 41 |
| 7 | HeyReach | 54 |
| 8 | Vercel | 62 |
| 9 | n8n | 59 |
| 10 | Apify | 52 |
AI agents that discover, compare and buy products on a person's behalf.
After an uneven summer, Agents as Buyers recovered in September and is up 23.4% over the last 30 days. The evidence spans checkout infrastructure and retailer use: Shopify announced a Muse partnership for agentic checkout with Shop Pay, while JD Sports and Lampenwelt described AI product discovery. October commentary adds the marketing question: how do brands sell to agents?
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 |  Browserbase | 34 |
| 3 | Claude Code | 99 |
| 4 | Exa.ai | 49 |
| 5 | Grok Bot | 75 |
| 6 | 1mind | 38 |
| 7 | Cline | 31 |
| 8 | OpenRouter | 52 |
| 9 | Semrush | 47 |
| 10 | Substack | 51 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting's share climbed from March to a June peak, then fell through September. The last 30 days show a 30.3% rebound, with October examples focused on concrete copy tasks: personalizing email messages by audience, comparing copywriting frameworks using predicted performance, and drafting branded ad headlines and copy.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Instantly | 65 |
| 5 | n8n | 59 |
| 6 | AI Ark | 48 |
| 7 | HeyReach | 54 |
| 8 | RB2B | 47 |
| 9 | Smartlead | 47 |
| 10 | BetterContact | 43 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
May’s high coincided with concrete pricing launches: ElevenLabs cut API prices and added pay as you go, while monday.com introduced credits after 18 months of customer usage data. Share settled lower through September, but the last 30 days are up 24.8%; AiSDR’s $1.50-per-prospect beta adds a new example of the same pattern: smaller commitments, with spend tied to use.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Gong | 64 |
| 4 | Clay | 93 |
| 5 | HubSpot | 89 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Lovable | 61 |
| 8 | Replit | 56 |
| 9 | Codex | 84 |
| 10 | Exa.ai | 49 |
The software stack marketers use to plan, run, measure and improve their work.
Martech held near 1.5% of conversation through May, fell into July, and briefly rebounded in August before another September decline; the last 30 days are down 16.1%. No single event explains those turns. The posts sustain an architecture debate: Brinker proposes a unified data foundation, Chernov questions agent sprawl, and Adobe describes Metro’s replacement of a 14-year-old system landscape.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Braze | 37 |
| 4 | GrowthLoop | 29 |
| 5 | Docket | 32 |
| 6 |  Influ2 | 26 |
| 7 | Salesloft | 40 |
| 8 |  allGood | 19 |
| 9 | Hightouch | 32 |
| 10 |  Hootsuite | 22 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing Operations lost share from March through July, briefly recovered in August, then fell again in September; the latest 30 days show an 18.6% lift. No single event explains that long decline, but the posts expose a recurring tension: Conversion promises agent-led campaign execution, Nvidia seeks operations leadership, and Jon Miller challenges the old marketing automation playbook.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | GrowthLoop | 29 |
| 5 |  Conversion | 28 |
| 6 | Docket | 32 |
| 7 | Grok Bot | 75 |
| 8 | Salesloft | 40 |
| 9 | allGood | 19 |
| 10 | Claude Code | 99 |
AI agents that create, launch, buy and optimize advertising.
A steady May–August climb held near its summer level in September, and conversation share is now up 70.2% over the last 30 days. The evidence points to successive practical advances rather than one spike: self-serve ChatGPT ads and AirOps support, demos of one-person paid media teams, and Roadway agents that manage campaigns and adjust budgets across platforms.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Grok Bot | 75 |
| 3 | Lovable | 61 |
| 4 | Claude Code | 99 |
| 5 | Salesforce | 94 |
| 6 | Clay | 93 |
| 7 | Codex | 84 |
| 8 | Granola | 53 |
| 9 | Similarweb | 31 |
| 10 |  Tealium | 21 |
How marketing teams use AI, where it helps and how it changes the job.
AI in marketing fell from March through May, then recovered unevenly to an August–September plateau; conversation share is up 14.2% over 90 days but down 15.4% over 30. The posts trace a recurring gap between access and execution: Google’s marketing engineer hire, Inflection’s agent-platform pitch, and Tejas Manohar’s account of pilots that left marketing processes largely unchanged.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | ElevenLabs | 56 |
| 4 | Granola | 53 |
| 5 | Grok Bot | 75 |
| 6 | Lovable | 61 |
| 7 | Midjourney | 35 |
| 8 | Profound | 53 |
| 9 | Salesforce | 94 |
| 10 | Salesloft | 40 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
The climb from March to July tracks concrete examples of GTM work moving into terminals: Vacca’s ad operations in Claude Code, then Clay’s CLI and API alongside reusable outbound skills. Share eased in August and September and is down 45.6% over the last 30 days. September’s discussion centers on fitting Clay into coding-agent workflows after the summer releases.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | Codex | 84 |
| 4 | HubSpot | 89 |
| 5 | Instantly | 65 |
| 6 | n8n | 59 |
| 7 | Grok Bot | 75 |
| 8 | AI Ark | 48 |
| 9 | Findymail | 43 |
| 10 | HeyReach | 54 |
Websites and docs structured so AI crawlers and agents can read and use them.
Machine-readable sites held a fairly steady spring baseline, faded through September, and are up 28.3% over the last 30 days, though still down over 90 days. The recurring debate is what actually helps models use a site: Webflow’s earlier growth account, disputed Google guidance, and rising searches for agent optimization tactics. Soulo’s October post adds renewed interest, with effectiveness still an open question.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Semrush | 47 |
| 3 | Vercel | 62 |
| 4 | Ahrefs | 51 |
| 5 | Gamma | 45 |
| 6 | Peec AI | 30 |
| 7 | Claude Code | 99 |
| 8 | Codex | 84 |
| 9 | Grok Bot | 75 |
| 10 | HubSpot | 89 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing automation declined through June, then recovered steadily through September; share is up 42.8% over the last 30 days. The posts show a broader discussion of what workflows should do: HubSpot launched Agent Hub and Agent Builder, Jev illustrated ad-analysis tasks, and Tom Fishburne challenged automated funnels that ignore customer intent. That mix supports a recurring conversation beyond one launch.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Braze | 37 |
| 4 | Apollo.io | 50 |
| 5 | Clay | 93 |
| 6 | Conversion | 28 |
| 7 | n8n | 59 |
| 8 | Claude Code | 99 |
| 9 | Grok Bot | 75 |
| 10 | Instantly | 65 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales Ops reached 1% in May, then broadly lost share through September; the last 30 days are down 9.3%. No single event accounts for the decline, but compensation remains a recurring thread: posts challenge meeting-based SDR incentives, describe seven-figure earnings at private companies and question recruiting promises that quota attainment cannot support.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Codex | 84 |
| 5 | Vercel | 62 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Exa.ai | 49 |
| 8 | Gong | 64 |
| 9 | Nooks | 48 |
| 10 | n8n | 59 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Sales development's share declined each month from May through September, and a 32.7% lift over the last 30 days still leaves it down 47.2% over 90 days. The posts frame a debate over the function's design, from failed AI replacement efforts to broader seller accountability. October's Clay and Notion AMA offers a practical hook: signals, automation, and more pipeline per rep.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Gong | 64 |
| 3 |  Outreach | 44 |
| 4 | Clay | 93 |
| 5 | FullEnrich | 44 |
| 6 | HubSpot | 89 |
| 7 | Monaco | 28 |
| 8 |  Unify | 31 |
| 9 | Claude Code | 99 |
| 10 | Exa.ai | 49 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce shows a concentrated conference cycle: attention built in August, surged to 3.7% in September and is down 82.1% over the last 30 days. Informatica’s Salesforce-family debut and Crossbeam’s AgentExchange launch partnership supplied event news, while criticism of conference ROI added debate around the same September window.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | ZoomInfo | 51 |
| 5 | Lightfield | 27 |
| 6 | Apify | 52 |
| 7 |  Aurasell | 18 |
| 8 | Common Room | 34 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Firecrawl | 41 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
After March’s high, attention moved unevenly through September; a 73.5% lift over the last 30 days sits alongside an almost flat 90-day comparison. No single event explains that pattern: the posts repeatedly connect face-to-face sales with trust and relevant context, while Ashley Faus shows how the wrong event location can undermine attendance.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | Lovable | 61 |
| 4 | HubSpot | 89 |
| 5 | Ahrefs | 51 |
| 6 | Apify | 52 |
| 7 | Aurasell | 18 |
| 8 | Customer.io | 39 |
| 9 | Gong | 64 |
| 10 | HeyReach | 54 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Salesforce’s Headless 360 announcement gives April’s sharp spike a clear event: access to Salesforce, Agentforce, and Slack through APIs, MCP, and CLI. Share faded through July, then recovered through September without a clear catalyst in these posts. The last 30 days are down 46.8%, even as Glean offers a concrete example of agent development inside existing coding tools.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Replit | 56 |
| 7 | Apify | 52 |
| 8 | Braze | 37 |
| 9 | ElevenLabs | 56 |
| 10 | Exa.ai | 49 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
The conversation crested in April, held near a lower level through summer, and is now down 33.1% over the last 30 days. No single event explains the fade; the posts trace a shift from redesigning processes around growth metrics to finding CMOs who automate work and helping teams keep their skills current.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Codex | 84 |
| 5 | Granola | 53 |
| 6 | Lovable | 61 |
| 7 | Vercel | 62 |
| 8 | Claude Code | 99 |
| 9 | ElevenLabs | 56 |
| 10 | Nooks | 48 |
The work of earning awareness, trust and preference for a company over time.
Brand building stayed near 1% of conversation through June, then weakened unevenly before September’s sharp drop; the latest 33.6% decline extends that direction. No single event explains the fall. The posts expose a recurring budget problem: Fin celebrates awareness gains, while Peep Laja and Ramp’s attribution example show why those gains can struggle to earn financial credit.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Optimizely | 33 |
| 2 | Salesforce | 94 |
| 3 | Customer.io | 39 |
| 4 | HubSpot | 89 |
| 5 | Semrush | 47 |
| 6 | Supabase | 50 |
| 7 | Vercel | 62 |
| 8 | 6sense | 42 |
| 9 | Braze | 37 |
| 10 | Claude Code | 99 |
Deciding what to build, why it matters and which product bets come first.
Product Strategy settled into a narrow band after its spring swings, with conversation share down 4.5% over the last 30 days. No single event explains the plateau; the recurring question is what companies should actually sell, from Mycroft’s shift to CMMC certification services to Automation Anywhere’s agreement to acquire boost.ai for customer-facing conversational and voice AI.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Vercel | 62 |
| 5 | Clay | 93 |
| 6 | ElevenLabs | 56 |
| 7 | OpenRouter | 52 |
| 8 | 11x | 24 |
| 9 | 1mind | 38 |
| 10 | Ahrefs | 51 |
Systems where several agents divide a job, coordinate their work and combine the result.
Conversation share peaked in May and declined through September, with another 30.3% decline over the last 30 days. Workato’s Airo expansion, Mercor’s 100-plus-subagent run and ZoomInfo’s DoubleO.ai acquisition supplied concrete milestones without sustaining broader attention; their shared theme is reliable execution, evaluation and context, rather than agent count alone.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | HubSpot | 89 |
| 5 | n8n | 59 |
| 6 | Grok Bot | 75 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Findymail | 43 |
| 9 | Firecrawl | 41 |
| 10 | HeyReach | 54 |
Tracing and monitoring what a model or agent did during a production run.
After a nearly flat June and July, observability’s share rose through September; the last 30 days remain up 7.1%. No single launch explains the climb: Intercom’s Fin suite, Databricks’ Unity Gateway, and CrewAI’s account of a bank sales conversation all point to the same demand for visibility inside the agent platform, without another vendor contract.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Salesforce | 94 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | LangChain | 45 |
| 6 | Browserbase | 34 |
| 7 | Clay | 93 |
| 8 | Exa.ai | 49 |
| 9 | Grok Bot | 75 |
| 10 |  Kiro | 23 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI Security held a fairly steady share from March through August before a sharp September drop. The last 30 days are up 25.8%, but the 90-day move remains negative. No single event explains that recovery; the posts share an operational focus, from Vanta’s continuous compliance tools to Oracle’s data-layer protections and Forrester’s call to govern agent objectives.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Midjourney | 35 |
| 3 | Grok Bot | 75 |
| 4 | Salesforce | 94 |
| 5 | Attio | 51 |
| 6 | Codex | 84 |
| 7 |  E2B | 21 |
| 8 | ElevenLabs | 56 |
| 9 | Firecrawl | 41 |
| 10 |  Ghost | 18 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing rose from March through August, then held nearly flat in September as cost and infrastructure stories kept supplying reasons to discuss it. Devin Fusion promised lower costs, OpenRouter announced it was joining Stripe, and Harvey's reported margin troubles sharpened the economics argument. The last 30 days are down 59.7%, despite a positive 90-day move.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Grok Bot | 75 |
| 3 | Salesforce | 94 |
| 4 | HubSpot | 89 |
| 5 | Lovable | 61 |
| 6 | Nooks | 48 |
| 7 | OpenRouter | 52 |
| 8 | Profound | 53 |
| 9 | Airtable | 48 |
| 10 | Apify | 52 |
Multi-step work planned and executed by agents instead of fixed automation rules.
The curve shows bursts rather than a sustained climb: May and September gains each followed quieter months, and the last 30 days are down 14.3%. October’s posts cluster around Clay’s Global Agent launch and Aurasell’s reported results with 67 agents supporting four reps. They show a recurring mix of product launches and operating claims, without explaining the earlier spikes.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Codex | 84 |
| 5 | Gong | 64 |
| 6 | Instantly | 65 |
| 7 | Nooks | 48 |
| 8 | 6sense | 42 |
| 9 | AI Ark | 48 |
| 10 | Demandbase | 34 |
Teams building internal software with AI instead of buying another SaaS product.
Replacing SaaS lost ground after March and April, then held a lower summer baseline; share is down 43.3% over the last 30 days. No single event explains the decline, but the posts repeatedly challenge the economics of rebuilding purchased tools, from Slack to Granola. Voje’s survey preview adds a narrower use case: startups below $1 million ARR building their own tooling.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Vercel | 62 |
| 5 | Monaco | 28 |
| 6 | Apify | 52 |
| 7 | ElevenLabs | 56 |
| 8 | Nooks | 48 |
| 9 | Qualified | 27 |
| 10 | Replit | 56 |
A shared revenue knowledge layer that people and agents can query and update.
June established a higher conversation baseline that held through September, although no single post here explains the initial jump. The evidence spans ownership debates, Swan AI’s shared context for 120-plus agents, and ZoomInfo’s Workbounce acquisition. That repeated focus on reusable company knowledge fits the elevated plateau; the last 30 days are down 9.3%, despite a 20.3% gain over 90 days.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | Codex | 84 |
| 4 | Fireflies | 39 |
| 5 | HubSpot | 89 |
| 6 | Instantly | 65 |
| 7 | ZoomInfo | 51 |
| 8 | Apify | 52 |
| 9 | Attio | 51 |
| 10 | Cursor (Anysphere) | 77 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales tech’s June rebound gave way to successive declines through September, with share down another 25.3% over the last 30 days. The posts show a move from tool abundance, including Europe’s outbound stack and Airscale’s APIs, toward a practical gap: an AI dialer can accelerate calls without knowing when a rep should skip one.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Gong | 64 |
| 3 |  Backstory | 18 |
| 4 | Braze | 37 |
| 5 | Clay | 93 |
| 6 | Common Room | 34 |
| 7 | Nooks | 48 |
| 8 | Seismic | 29 |
| 9 | Apify | 52 |
| 10 | Apollo.io | 50 |
Using AI to tailor outreach and marketing to each person at scale.
AI personalization’s spring high gave way to a steady decline through September, with another 20.3% drop over the last 30 days. The posts show a consistent critique rather than one triggering event: Kyle Asay narrows account lists with AI, Nick Palasz distinguishes relevance from observations, and John Barrows favors researched substance over formulaic outreach.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Braze | 37 |
| 5 | Claude Code | 99 |
| 6 | Exa.ai | 49 |
| 7 | Lemlist | 49 |
| 8 | Prospeo | 54 |
| 9 | Replit | 56 |
| 10 | Sumble | 34 |
Approval and review steps that keep a person involved in an agent's work.
Human in the Loop rebounded in August, fell in September, and is now nearly flat, up 2.7% over the latest 30 days. The meaningful pattern is specificity: Healey discusses autonomy and accountability, Brinker separates review by expertise and time, and Tenex packages permissions, approvals, and audit trails into its agent launch.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 89 |
| 3 | Instantly | 65 |
| 4 | Clay | 93 |
| 5 | HeyReach | 54 |
| 6 | Nooks | 48 |
| 7 | Salesforce | 94 |
| 8 | AI Ark | 48 |
| 9 | Apollo.io | 50 |
| 10 | Attio | 51 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Content at scale peaked in May, declined through summer and barely moved in September; the last 30 days show a further 34.7% drop. No single event explains the retreat: Higgsfield and Figma offer more production capabilities, while Eli Schwartz warns about AI spam, so the posts pair faster output with questions about its consequences.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 51 |
| 2 | AirOps | 41 |
| 3 | Apify | 52 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 49 |
| 6 | Granola | 53 |
| 7 | Lovable | 61 |
| 8 | Substack | 51 |
| 9 | Airtable | 48 |
| 10 | Apollo.io | 50 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-serve discussion fell sharply from March to May, recovered into a July–August plateau, then softened; the last 30 days are down 18.6%. That plateau contained a concrete launch and a warning: Metronome opened self-serve access, while Elena Verna used the reported Airtable deal to question enterprise expansion at self-serve’s expense. The recurring tension is buyer independence versus company priorities.
Posts to understand this
 inEnterprise tensionElena Verna questions enterprise priorities after reported Airtable acquisition agreement1
 inBuyer control1up describes answer engines and self-service demos that reduce buyer waitsSW
 inAccess launchMetronome opens self-serve access and reports fivefold quarterly new revenue growth
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | Klaviyo | 39 |
| 5 | Replit | 56 |
| 6 | Granola | 53 |
| 7 | Lovable | 61 |
| 8 | Outreach | 44 |
| 9 | Vercel | 62 |
| 10 | 6sense | 42 |
Founders running early sales themselves before handing the motion to a sales team.
Founder-led sales rebounded sharply from May’s low to July, when Kazanjy opened free access to Founding Sales and Leese described a costly premature sales handoff. Share softened through September, but the last 30 days are up 33.2%. The recurring thread is practical: learn the motion before delegating it, then hire someone you would trust to sell your own product.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 |  Passionfroot | 23 |
| 5 | Ploy | 31 |
| 6 | Primer | 30 |
| 7 | Salesforce | 94 |
| 8 | Sumble | 34 |
| 9 | 6sense | 42 |
| 10 | Codex | 84 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
May’s high had a concrete proof point: Gong reported growth above 55% and said customers were consolidating point solutions onto its platform. Conversation share then retreated, with the last 30 days down 24.7% despite Apollo’s AI GTM system reveal. The evidence shows a recurring platform expansion story, from Nooks’ sequencer to Apollo, but no single event explains the decline.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | Gong | 64 |
| 4 | Claude Code | 99 |
| 5 | Common Room | 34 |
| 6 | Braze | 37 |
| 7 |  Clari | 32 |
| 8 | Codex | 84 |
| 9 |  Fathom | 32 |
| 10 | Granola | 53 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound systems rose from March to a May peak, then declined through September, with share down another 35.2% over the last 30 days. April’s signal-driven BDR workflow and August’s downloadable outbound skills show the systems pitch; October’s manual café prospecting offers a concrete counterpoint.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Instantly | 65 |
| 4 | Salesforce | 94 |
| 5 | Smartlead | 47 |
| 6 | Attio | 51 |
| 7 | 6sense | 42 |
| 8 |  Amplemarket | 17 |
| 9 |  Calendly | 39 |
| 10 |  Clarify | 29 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise Marketing rose through July and August, stepped down in September, and is now essentially flat, up 1.2% over the last 30 days. The posts share a practical thread: pipeline ownership, production readiness, and measurable visibility in AI answers. That plateau reflects a continuing operational conversation, with no single launch or deal to explain the curve.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Aurasell | 18 |
| 4 | Clay | 93 |
| 5 | Grok Bot | 75 |
| 6 | Lightfield | 27 |
| 7 | Lovable | 61 |
| 8 | OpenRouter | 52 |
| 9 | Replit | 56 |
| 10 | AirOps | 41 |
Writing and structuring the instructions a model follows.
Prompt engineering lost share from March through September, apart from a June rebound; the last 30 days now show a 16% lift against a 43.6% decline over 90 days. No single event explains that path. The posts share a critique: better prompts alone cannot fix missing context, unreliable rollouts, or recognizable AI writing patterns.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Clay | 93 |
| 5 | Codex | 84 |
| 6 |  Viktor | 33 |
| 7 | Zapier | 54 |
| 8 | Apify | 52 |
| 9 | Attio | 51 |
| 10 |  Breeze | 23 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
AI sameness spiked in April and faded each month through September; the latest 94.1% bounce still sits within a 39.2% decline over 90 days. The posts suggest a shift from criticism toward practical fixes: Santiago Faus calls out formulaic ChatGPT posts, while Diandra Escobar offers a Claude skill with explicit rules and examples for LinkedIn hooks.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | HubSpot | 89 |
| 3 | Substack | 51 |
| 4 | Apify | 52 |
| 5 | Claude Code | 99 |
| 6 | Clay | 93 |
| 7 | Exa.ai | 49 |
| 8 |  Grammarly | 29 |
| 9 | Monaco | 28 |
| 10 | Primer | 30 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium rebounded from July’s low through September, alongside OpenAI’s reported $1 billion ChatGPT ads run rate and renewed attention to PostHog’s generous free tier. Those posts give the recovery a shared theme: how companies fund free access and turn it into business. Share is now down 43.7% over the last 30 days, despite remaining up over 90 days.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Grok Bot | 75 |
| 5 | HubSpot | 89 |
| 6 | Ahrefs | 51 |
| 7 | Claude Code | 99 |
| 8 | Clay | 93 |
| 9 | Devin | 38 |
| 10 | Exa.ai | 49 |
Time-limited access that lets a buyer test a product before paying.
Free-trial conversation recovered through July after April’s drop, then lost ground in August; the last 30 days are up 43.9%, against a 36.8% decline over 90 days. The evidence points to recurring conversion problems rather than one catalyst: funnel benchmarks, BDR credit rules that delayed follow-up, and Sunsama’s offer to restart an underused trial.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Gong | 64 |
| 4 | Ahrefs | 51 |
| 5 |  AthenaHQ | 21 |
| 6 | Calendly | 39 |
| 7 | Canva | 50 |
| 8 | Claude Code | 99 |
| 9 | Clay | 93 |
| 10 |  ColdIQ | 30 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
AI employees held a fairly steady share through summer after a May high, but conversation share is down 48.5% over the last 30 days. The evidence shows recurring product and distribution moves rather than one defining event: Viktor expanded from Slack to Teams after reporting $20 million in annualized revenue, and September brought an open-source company brain.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Viktor | 33 |
| 5 | Granola | 53 |
| 6 | Grok Bot | 75 |
| 7 | Primer | 30 |
| 8 | beehiiv | 51 |
| 9 | Apify | 52 |
| 10 | Attio | 51 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
May’s high point aligns with a concrete Replit example: custom GTM apps alongside Salesforce, Nooks and continued sales hiring. Share fell sharply in June and stayed below May through September; the latest 30 days are down 11.9%. Zendesk’s dedicated GTM AI leadership role adds evidence of organizational commitment, but the posts offer no single event that explains the broader decline.
Posts to understand this · as of Oct 24
 inLeadership appointmentJustin Norris joins Zendesk to lead GTM AI and automation globallyKN
 inOperating exampleReplit builds custom GTM workflows while retaining Salesforce and hiring salespeopleJC
 inRole evolutionJeff Canada describes marketing operations shifting from system operators to strategic builders
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Lovable | 61 |
| 4 | Profound | 53 |
| 5 |  Rox | 31 |
| 6 | Substack | 51 |
| 7 | Sumble | 34 |
| 8 | Vector | 35 |
| 9 | 1mind | 38 |
| 10 | 6sense | 42 |
The online channel mix used to reach, convert and retain customers.
Digital marketing climbed through June, then fell through September; its 144.8% lift over the last 30 days still sits alongside a 39.5% decline over 90 days. No single launch explains the curve: Ahrefs’ Agent A supplied a spring product hook, while posts on SEO accountability and workflows.io’s multichannel funnel connect tools and channel choices to pipeline outcomes.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Nooks | 48 |
| 3 | Semrush | 47 |
| 4 | AI Ark | 48 |
| 5 | Ahrefs | 51 |
| 6 | Apollo.io | 50 |
| 7 | Baseten | 44 |
| 8 | Chili Piper | 36 |
| 9 | Claude Code | 99 |
| 10 | Codex | 84 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
Conversation share peaked in May, fell through August, and is recovering: up 34.8% over the last 30 days, though still down 29.4% over 90 days. October discussion spans Gupta’s comments on Braze and stack integration, Miro’s experiments with synthetic customers for campaign testing, and Optimove’s addition of Messenger to existing customer journeys.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Gong | 64 |
| 4 | GrowthLoop | 29 |
| 5 | Braze | 37 |
| 6 | Calendly | 39 |
| 7 |  Centralize | 24 |
| 8 | Claude Code | 99 |
| 9 | Customer.io | 39 |
| 10 |  Default | 27 |
The runtime around an agent that provides tools, state, controls and stopping rules.
Conversation share has swung up and down, peaking in June and rebounding in August before easing in September. It is down 23.9% over the last 30 days, while September explainers described how harnesses give models tools and October brought Retool’s announcement of shared infrastructure and access controls.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Clay | 93 |
| 5 |  GitHub Copilot | 35 |
| 6 | Hermes Agent | 36 |
| 7 | Kiro | 23 |
| 8 | LangChain | 45 |
| 9 | Salesforce | 94 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
Outcome-Based Pricing rose through May, faded through August, then recovered some share in September; the last 30 days still show a 6% decline. The evidence moves from pricing announcements toward operating details: HubSpot introduced per-result agent charges, Salesforce agreed to acquire m3ter for flexible billing, and Intercom addressed spend forecasts. That pattern suggests practical follow-through after the spring attention.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | HubSpot | 89 |
| 5 | Intercom | 43 |
| 6 | Lovable | 61 |
| 7 |  Metronome | 25 |
| 8 |  UiPath | 26 |
| 9 | Vercel | 62 |
| 10 | 1mind | 38 |
How AI changes headcount, entry-level work and the jobs people still need to do.
Conversation share has contracted substantially since March, with a May rebound and a further 9.3% decline over the last 30 days. No single event in these posts explains the slide; the recurring tension is between lean-team revenue claims and evidence that human roles persist. OpenAI’s SDR hiring and Kyle Lacy’s account of marketers’ anxiety keep that tension concrete.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Vercel | 62 |
| 3 | 11x | 24 |
| 4 | 1mind | 38 |
| 5 | Conversion | 28 |
| 6 | Docket | 32 |
| 7 |  Framer | 30 |
| 8 | Grok Bot | 75 |
| 9 | HubSpot | 89 |
| 10 | Lovable | 61 |
The strategy of naming, defining and leading a new market.
Category creation held nearly flat from April through June, then lost ground despite an August bounce; conversation share is down another 10% over the last 30 days. The posts point to a recurring challenge rather than one decisive event: Kaminski puts buyer jobs before category names, Chernov questions AI-era category gatekeepers, and Laja sets strict conditions for an AI pivot.
Posts to understand this · as of Oct 25
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Braze | 37 |
| 4 | Gong | 64 |
| 5 | Granola | 53 |
| 6 | Primer | 30 |
| 7 | Ahrefs | 51 |
| 8 |  AppsFlyer | 18 |
| 9 | Attio | 51 |
| 10 |  Bland | 19 |
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
Conversation share fell from March to an August low despite Polsia’s reported $10 million run rate with one employee, then recovered in September; the last 30 days are up 11.9%. The recent evidence centers on operating detail: Swan describes one person running 126 GTM workflows, and AssemblyAI reports nearing $1 million ARR per employee, though share remains down 51.2% over 90 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Lovable | 61 |
| 3 |  Base44 | 24 |
| 4 | Canva | 50 |
| 5 |  Lusha | 29 |
| 6 | Salesforce | 94 |
| 7 | Twilio | 42 |
| 8 | beehiiv | 51 |
Advantages that grow stronger as more people, data or participants join a product.
Network effects lost conversation share every month from March through September, and the last 30 days show a further 38.6% decline. No single event explains the slide; the posts move from ChatGPT trust loops and Snapchat’s ecosystems to Martin Casado’s challenge to loose definitions, so the recent evidence centers on what qualifies as a network effect.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | ElevenLabs | 56 |
| 5 | Granola | 53 |
| 6 | Grok Bot | 75 |
| 7 | Replit | 56 |
| 8 | Attio | 51 |
| 9 | Chili Piper | 36 |
| 10 | Clarify | 29 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
HubSpot’s April announcement that INBOUND would become UNBOUND explains the first spike; September’s Boston event supplied the much larger second wave. Partner Day drew over 1,300 partners, and Dave Gerhardt described roughly 13,000 attendees at the conference. The 86.8% decline over the last 30 days fits an event-driven conversation after the gathering ended.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Firecrawl | 41 |
| 4 | Lightfield | 27 |
| 5 | Profound | 53 |
| 6 | Salesforce | 94 |
| 7 | Apify | 52 |
| 8 | Breeze | 23 |
| 9 | Grok Bot | 75 |
| 10 | Higgsfield | 38 |
How sales teams use AI and how it changes the work of selling.
AI in Sales rebounded in May, then lost share through September, with a further 45.5% decline over the last 30 days. Recent posts examine the gap between promises and practice: rep workflows went largely unchanged, faster work did not improve revenue outcomes, and announced capabilities need separating from released features.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Mutiny | 31 |
| 2 | Clarify | 29 |
| 3 | Clay | 93 |
| 4 | Clearskies | 23 |
| 5 | Codex | 84 |
| 6 | Gong | 64 |
| 7 | Grok Bot | 75 |
| 8 | HubSpot | 89 |
| 9 | Salesforce | 94 |
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
July’s spike coincided with Together AI’s RAISE Summit case for open inference and its criticism of closed-model costs. Share receded through September, and the last 30 days are down 23.5%. Bolt Forge’s open-model usage offer and Christopher Lochhead’s criticism of OpenAI and Anthropic show the recurring pattern: cost arguments and competitive disputes, without sustained conversation growth.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Cline | 31 |
| 2 | Cursor (Anysphere) | 77 |
| 3 |  Groq | 25 |
| 4 | Baseten | 44 |
| 5 | ElevenLabs | 56 |
| 6 |  Manus | 30 |
| 7 |  Parallel | 34 |
| 8 | Salesforce | 94 |
| 9 | Substack | 51 |
| 10 | Vercel | 62 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
August’s sharp spike has a clear common thread: Anthropic’s watermarking FAQ, Synthesia’s marking update, and commentary on generation and detection tools all centered on transparency requirements. Share dropped back in September, which fits a concentrated compliance discussion rather than sustained expansion. The last 30 days are nearly flat at plus 1.5%, despite the much larger 90-day gain.
Posts to understand this · as of Oct 23
 XCompliance explanationAnthropic says watermarking implementation is intended to comply with EU rulesMR
 inIndustry commentaryMelissa Rosenthal examines companies that offer both AI generation and detectionS
 inProduct implementationSynthesia describes automatic machine-readable marking and C2PA credentials for relevant videos
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Grok Bot | 75 |
| 3 | Claude Code | 99 |
| 4 | Docket | 32 |
| 5 | Ghost | 18 |
| 6 | Granola | 53 |
| 7 | HeyGen | 33 |
| 8 | Higgsfield | 38 |
| 9 | HubSpot | 89 |
| 10 | Manus | 30 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
Conversation share rose in April, dipped in May, then held near 0.6% from June through August before falling in September; the latest 30 days are down 55.2%. Zapier's September expansion in Claude and October's fal and LocalFalcon connectors show releases continuing across business tools, media generation, and local business tasks as conversation share falls.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Codex | 84 |
| 3 | Claude Code | 99 |
| 4 | HeyGen | 33 |
| 5 |  Lambda | 27 |
| 6 | Lovable | 61 |
| 7 | Replit | 56 |
| 8 | Salesforce | 94 |
| 9 | Semrush | 47 |
| 10 | Zapier | 54 |
AI-native firms that sell finished work instead of software, delivered by agents and a small human team.
Services-as-software held roughly steady through June before dropping to a lower range in July; the last 30 days are down 21.7%. Emergence Capital’s outcome-based services thesis and Daydream’s $15 million Series A gave the spring conversation concrete substance. September’s post about Sequoia revisited the investment thesis, but the curve shows no sustained return to spring levels.
Posts to understand this · as of Oct 24
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Findymail | 43 |
| 3 | HeyReach | 54 |
| 4 | HubSpot | 89 |
| 5 |  Pinecone | 32 |
| 6 | Supabase | 50 |
| 7 | n8n | 59 |
| 8 | AI Ark | 48 |
| 9 | Airtable | 48 |
| 10 | Apify | 52 |
Rule-based software that moves business work through predefined steps and systems.
Conversation share peaked in April, then generally declined through September; the latest 30 days are down 65%. These posts cover automating sales busywork, adding AI steps to connected workflows, and processing purchase orders. They show concrete uses for automation, but do not establish why its share of conversation fell.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | n8n | 59 |
| 3 | AI Ark | 48 |
| 4 | Clay | 93 |
| 5 | Salesforce | 94 |
| 6 | Claude Code | 99 |
| 7 | Codex | 84 |
| 8 | Findymail | 43 |
| 9 | HeyReach | 54 |
| 10 | Instantly | 65 |
AI-generated creators, avatars and user-style content used in marketing.
An April spike faded through August before September’s rebound; conversation share is now down 27.6% over the last 30 days. The posts do not explain April’s jump, but September paired HeyGen’s small-business video survey with a firsthand avatar trial. The recurring question is practical: can avatars help people publish, and do they feel convincing enough?
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 75 |
| 2 | Instantly | 65 |
| 3 | Apify | 52 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 49 |
| 6 | HeyGen | 33 |
| 7 | People Data Labs | 24 |
| 8 | Gamma | 45 |
| 9 | Higgsfield | 38 |
| 10 | HubSpot | 89 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory reached its high in April, when Matt Heinz argued that fractional CMOs could be permanent leadership for $5m–$50m B2B companies. Share settled lower through summer; the last 30 days are up 7.7%. The posts show a practical thread rather than one catalyst: senior judgment, packaged marketing plans, and HubSpot diagnosis before more ad spend.
Posts to understand this · as of Oct 22
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | AirOps | 41 |
| 3 | Consensus | 27 |
| 4 |  Factors.ai | 20 |
| 5 | Gamma | 45 |
| 6 | Gong | 64 |
| 7 | HubSpot | 89 |
| 8 | Lovable | 61 |
| 9 | Profound | 53 |
| 10 | Webflow | 47 |
The argument over requiring a form before someone can access useful content.
After May’s rebound, gated-content discussion thinned to an August–September plateau; the last 30 days are up 85.7%, but the 90-day move remains down 41.3%. The recurring argument is about when gates serve buyers: Amanda Natividad separates ideas from utility, Ashley Lewin reconsiders a blanket ban, and Andrei Zinkevich challenges gates used to manufacture marketing credit.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Apify | 52 |
| 3 | Clay | 93 |
| 4 | AI Ark | 48 |
| 5 | Attio | 51 |
| 6 |  BuiltWith | 32 |
| 7 | Claude Code | 99 |
| 8 | Firecrawl | 41 |
| 9 | Instantly | 65 |
| 10 |  Ocean.io | 39 |
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing rose to a July high, then contracted through September before a 20.2% lift over the last 30 days. The renewed attention comes with criticism of token consumption: Sierra argues for outcome pricing, Databricks demonstrates budget controls, and Dennis Sevilla collects executives’ complaints about costs without results. That pattern suggests the debate has shifted toward value, rather than renewed enthusiasm for spending.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Devin | 38 |
| 2 | Gamma | 45 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
Software designed for agents to operate as the primary user.
Agents as users grew from almost nothing in June, dipped in September, and is now up 447.4% over the last 30 days from a small base. Concrete traffic reports and product responses give the jump context: Lorikeet launches agent detection, CHEQ reports a surge after consumer-agent launches, and Melissa Rosenthal examines why ad-supported businesses restrict agent access.
Posts to understand this · as of Oct 22
 inProduct launchLorikeet launches detection to identify and manage inbound AI agent trafficMRinAccess economicsMelissa Rosenthal connects agent restrictions with advertising economics at Amazon and CloudflareC
 inTraffic signalCHEQ reports a hundredfold agentic traffic surge after consumer AI agent launches
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 75 |
| 2 | Attio | 51 |
| 3 | Claude Code | 99 |
| 4 | Midjourney | 35 |
| 5 | Canva | 50 |
| 6 |  Cartesia | 29 |
| 7 | Vercel | 62 |
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent loops surged in June and held near that level in July, as discussion paired practical limits on autonomy with Palantir’s Agent Engine and Agent SDK launch. Joe Rhew’s human-review framework captures the implementation questions behind that stretch. Share has since faded, down 40.8% over the last 30 days, despite Alex Lindahl’s renewed pitch for self-learning GTM systems.
Posts to understand this · as of Oct 27
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Replit | 56 |
| 3 | Attio | 51 |
| 4 | Claude Code | 99 |
| 5 | Clay | 93 |
| 6 | Codex | 84 |
| 7 |  Deepline | 35 |
| 8 | HubSpot | 89 |
| 9 | OpenClaw | 47 |
| 10 | Salesforce | 94 |
Pushback against AI from customers, workers and the public, and brands repositioning as pro-human.
AI backlash moves in bursts rather than a sustained climb: May’s high coincides with Rand Fishkin’s consumer-versus-business adoption argument, while the posts do not explain August’s rebound. September’s billboard vandalism account adds a concrete example of public hostility, but attention is down 57% over the last 30 days and nearly flat over 90 days.
Posts to understand this · as of Oct 23
| Brand | GTM Index | |
|---|---|---|
| 1 | Primer | 30 |
| 2 | 11x | 24 |
| 3 | 1mind | 38 |
| 4 |  AiSDR | 20 |
| 5 | Apify | 52 |
| 6 | Braze | 37 |
| 7 | Claude Code | 99 |
| 8 | Clay | 93 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Docket | 32 |
Interfaces that let agents understand and operate software built for human users.
Agent interfaces spiked in May, dropped in June, then rebounded in July before easing through September; conversation share is down 48.4% over the last 30 days. July’s rebound coincided with a batch of agent-callable releases from Clay, HubSpot, Webflow and others. Salesforce’s experience-layer tease and Hightouch’s shopping connector extended that product thread without sustaining July’s share.
Posts to understand this · as of Oct 26
| Brand | GTM Index | |
|---|---|---|
| 1 | Browserbase | 34 |
| 2 | Claude Code | 99 |
| 3 | Exa.ai | 49 |
| 4 |  Resend | 29 |
| 5 | Salesforce | 94 |
| 6 |  StackAdapt | 23 |
| 7 | Vercel | 62 |
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
AI Detection’s July spike held through August, when posts debated LinkedIn’s new “seems like AI slop” feature and whether detection works on social posts. That controversy provides a concrete focus for the summer plateau, distinct from Semrush’s earlier search-ranking analysis; share dropped sharply in September and is down 64.8% over the latest 30 days.
Posts to understand this · as of Oct 21
| Brand | GTM Index | |
|---|---|---|
| 1 | Substack | 51 |
| 2 | Fathom | 32 |
| 3 | Grammarly | 29 |
| 4 | Lightfield | 27 |
| 5 | Replit | 56 |
Brands use human authorship and craft as a reason to trust or value their work.
Human-made claims show intermittent bursts, with a May high and another build through July and August, rather than a sustained climb; the last 30 days are down 67.3%. The examples span Dave Gerhardt’s case for human craft, GTM Skills’ launch with 200-plus human-crafted skills, and Contentful’s human-made, agent-ready message alongside Mercedes-Benz and Deloitte Digital.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clearskies | 23 |
| 2 | Attention | 28 |
| 3 | Clarify | 29 |
| 4 | Clay | 93 |
| 5 | Nooks | 48 |
| 6 | Rox | 31 |
| 7 | Sumble | 34 |
| 8 | Codex | 84 |
| 9 | Grok Bot | 75 |
| 10 | Salesforce | 94 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
Trust-based marketing held nearly level in June and July, dropped in August, and recovered some ground in September; the last 30 days are down 49.2%. No single event explains the curve. The recurring thread is credibility before conversion: familiar voices in buyers’ feeds, consistent company behavior, and Acquia’s call to keep people in charge of creativity.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Twilio | 42 |
Using product activity to identify, time and support sales opportunities.
Product-led sales remains a tiny, intermittent conversation, despite a 46.2% lift over the last 30 days. The posts suggest why the low baseline matters: Pocus joining Apollo marked the absorption of a standalone tooling category, while an August HubSpot build showed the underlying practice still at work, with product signals supporting enterprise sales and 60,000-plus records updated daily.
Posts to understand this · as of Oct 24
How model costs, services and agent work put pressure on software gross margins.
This is a sparse conversation, with a brief April high of 0.031% and zero-share months in May and July. The current L30 move is down 60%, and the evidence remains split between lower AI gross margins and a services model where smaller engagements can unlock a larger market.
Posts to understand this · as of Oct 9
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Claude Code’s share fell steadily from 11.6% in March to 4.6% in September; the last 30 days show a modest 5.1% relative lift. Recent posts feature Vercel support for agents that resume after failures, a team running outbound through Claude Code, and a Blender integration. These document uses and integrations, without establishing what drove either move.
Posts to understand this · as of Oct 27
Cursor is an AI code editor with agents that write, edit and review code.
Cursor’s share declined from March through July, rebounded in August, then fell in September; the L30 move is down 27.7%. August announcements covered SpaceX’s acquisition of Cursor closing and Vercel’s agent plugins collaboration with Cursor. A September post highlighted Nvidia’s use of Cursor, but the selected evidence does not establish what caused the August rebound.
Posts to understand this · as of Oct 23
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay’s share peaked in May, declined through September, and is now recovering: L30 is up 13.8%, though L90 remains down 23.2%. October posts cover Clay’s place in a growing GTM stack, Eric Nowoslawski’s return and the revenue-agent mission, and hands-on testing of the new agent. These show what people are discussing, without establishing what caused the rebound.
Posts to understand this · as of Oct 21
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n’s May jump coincided with its SAP partnership announcement, after Gamma added a native integration in April; elevated share held through June before declining through September. The last 30 days are up 16.2%, though still below spring levels. October’s practitioner example offers a concrete use case for renewed discussion: Claude Code builds and debugs n8n workflows for trigger-based automation.
Posts to understand this
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable’s March high had a concrete community hook: a free build day with Anthropic and a firsthand account of a 14-year-old launching an app after a sponsored event. Share declined through July, then recovered to roughly 1% in August–September. MotherDuck’s web analysis adds a broader adoption reference, but the last-30-day move is down 6.4%.
Posts to understand this · as of Oct 27
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit’s May high gave way to a lower summer baseline; share is down 16.3% over 90 days but up 4.8% over the last 30. The posts show a steady stream of distribution moves rather than one breakout event: OpenAI powering Free Mode, a London office for European expansion, and Runway assets inside Replit projects.
Posts to understand this · as of Oct 27
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
OpenClaw’s high March–April share followed news of creator Peter Steinberger joining OpenAI and included DeepSeek’s April integration update and API discount. Share then declined every completed month through September, with no single setback identified in the posts. The last-30-day decline is now just 5.9%, while Salesforce’s October reference treats OpenClaw as an origin point for personal agents.
Posts to understand this · as of Oct 27
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
Codex rose through spring, then held near 3% of conversation from May through September; its latest 30-day share is down 10.6%. April posts paired fast demo creation with Salesforce’s Headless 360 support, consistent with interest across individual builders and enterprise tools. Vercel’s October durable-harness launch extends that tooling pattern, but has not prevented the recent loss of share.
Posts to understand this
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Hermes Agent appeared in April and reached its highest completed-month share in May, with Higgsfield's April MCP announcement supplying an early integration hook. Share then faded through September. The last 30 days are up 92.3%, alongside Microsoft Store availability and Tavily search integration, although the 90-day move remains down 57.9%.
Posts to understand this
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce’s share peaked near 4.8% in April, settled around 4% through summer, then returned to 4.8% in September. The posts span Fin’s June acquisition agreement, Informatica’s September Dreamforce debut within Salesforce, and Braze’s October acquisition agreement. Those announcements provide a recurring acquisition and integration thread, but the latest direction is down: share fell 17.2% over the last 30 days.
Posts to understand this · as of Oct 27
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
HubSpot’s share peaked in May alongside Vector’s HubSpot Ventures funding announcement, then fell through August despite June’s Warmly acquisition news. The last 30 days are up 8.9%, but share remains down 20.8% over 90 days. October’s visible conversation includes Halligan helping people affected by HubSpot layoffs find their next role.
Posts to understand this
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Gong’s share eased after April, despite May’s announcement of $500 million in ARR and 55%+ annual growth. The posts trace a gap between broad platform positioning and concrete uses: August brought criticism of its “Revenue AI OS” language, while October highlighted churn analysis from calls. The last 30 days show a modest 5.2% lift within a longer decline.
Posts to understand this · as of Oct 23
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
Vercel’s share has oscillated rather than sustained a climb, with August’s high followed by a September drop and a nearly flat last 30 days at +0.4%. The posts show recurring exposure through Grok’s connector, Rillet’s agent workflow, and developer stack recommendations. That pattern fits ongoing visibility across use cases, though it does not identify a cause for August’s spike.
Posts to understand this · as of Oct 21
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Claude Cowork lost share every completed month from March through September, and the last 30 days extend the decline by 26.2%. Practical examples have not interrupted that slide: April’s buying-committee content demo and September’s Docusign integration added use cases, while Tom Wentworth’s earlier preference for Claude Code offers a competing workflow rather than proof of why Cowork declined.
Posts to understand this · as of Oct 27
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly climbed through June, roughly halved in July and then settled into a lower range; the last 30 days are essentially flat at +0.9%. The posts do not explain June’s peak, but they show the practical use behind continued conversation: campaign results, outbound hiring and Dima Bilous’s roughly 200-mailbox setup connected to Slack and Attio.
Posts to understand this · as of Oct 27
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter’s conversation share climbed unevenly into an August peak, fell sharply in September, and is up 14.1% over the last 30 days. Recent posts highlight OpenAI overtaking Anthropic in weekly user spending, DeepSeek’s earlier token-volume gains, and a founder podcast following Stripe’s acquisition. These show the discussion continuing, but do not establish what caused August’s spike.
Posts to understand this · as of Oct 21
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
Substack’s uneven spring gave way to lower share, with a brief July lift before declines in August and September; the last 30 days are down 30.4%. The posts suggest a split in creator needs rather than one decisive event. Elena Verna values newsletter ownership, Adam Schoenfeld explains his move to beehiiv for customization, and Karlie Kloss launches on Substack.
Posts to understand this · as of Oct 25
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Semrush’s June high faded through August before a modest September recovery; share is up 28.6% over the latest 30 days but down 48.7% over 90 days. No supplied post explains June’s spike directly. The continuing thread is search visibility: Lovable’s May integration, September reassurance about Google redirects, and October’s Spotlight discussion of buyer questions versus visibility scores.
Posts to understand this
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva’s April high gave way to a broad decline through September; neither May’s Grok connector nor September’s 100 upgrades established a lasting rise. Attention is now up 75.7% over the last 30 days. October’s concrete hook is a practitioner’s account of editable Canva decks built through Claude, with reported production time cut by at least 80%.
Posts to understand this · as of Oct 26
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Ahrefs surged in May and stayed elevated in June, then settled into a July–September plateau above its March–April baseline; share is now down 15.3% over the last 30 days. The posts do not explain the initial surge. They show two later pressures: claims that AI tools can replace SEO dashboards, and Google redirects that temporarily disrupted Ahrefs’ data.
Posts to understand this · as of Oct 24
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier’s spring conversation centered on AI GTM teams and practical trigger-and-action workflows, with May followed by a broad decline through September. The October SpaceX Super Intelligence partnership adds an agent connectivity story across 9,000-plus apps, but the last 30 days remain down 11.2%. The evidence shows continued product relevance without a sustained lift in conversation share.
Posts to understand this · as of Oct 23
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
ZoomInfo’s June bump coincided with Exa Connect’s launch, followed by three months of declining attention. The last 30 days are up 28.2%, with Moltsets’ $27 monthly database pitch supplying a fresh competitive hook. Across Ava 2.0 and Moltsets, the recurring story is challengers naming ZoomInfo as a replacement target, alongside its role as an agent data source.
Posts to understand this · as of Oct 26
Profound measures and improves how brands appear in AI answers.
Profound’s April and July increases coincided with criticism of customer content quality and measurement reliability, while September’s rebound brought a $180 million Series D. The curve reflects alternating scrutiny and funding news, rather than a steady climb. Conversation share is down 17.5% over the last 30 days, despite a modest 90-day gain.
Posts to understand this · as of Oct 23
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
ElevenLabs’ share rose through May, fell unevenly to an August low, then rebounded in September; the last 30 days are up 54.6%. September’s selected post examines its sales playbook and reported $600 million ARR. October’s posts show Adobe promoting ElevenLabs v4 in Firefly and Harvey describing its use in marketing video production, adding concrete product examples to the growth discussion.
Posts to understand this · as of Oct 27
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio’s spring rise coincided with its Fin for Sales story and May’s GTM Atlas launch, before attention declined through September. The last 30 days are up 27.7%, though the 90-day move remains negative. October’s evidence centers on Attio’s shift to “CRM for agentic revenue,” which puts positioning language back in the conversation without establishing a sustained recovery.
Posts to understand this · as of Oct 26
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo’s spring surge coincided with users moving prospecting and enrichment into Claude, with Apollo as the underlying data source. Share peaked in May, held near a lower level through August, then softened; it is down 16.5% over the last 30 days. September’s ApolloNext vision for three connected products has not yet produced a sustained rebound.
Posts to understand this · as of Oct 23
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify rose sharply into May and held near that level through July, with posts demonstrating Claude social analysis and competitor ad research. Those repeatable workflows give the plateau a concrete theme beyond a single launch. Share eased in August and September and is down 31.9% over the latest 30 days, despite a fresh pitch for Apify’s agent tools.
Posts to understand this · as of Oct 23
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Granola’s share fell from roughly 1% in May to 0.4% in July, then stayed below its spring levels through September. The last 30 days show a 23.6% lift, with ClickUp’s Granola connection providing a fresh workflow use case. The posts pair expansion onto Apple Watch and into other tools with concern about competition from Siri; no single event explains the earlier decline.
Posts to understand this · as of Oct 26
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
HeyReach rose into a May-June plateau, then settled lower, with share down 11% over the latest 30 days. The evidence points to recurring inclusion in outbound playbooks rather than a single launch: Voje and Ruha place it in specific GTM stacks, while Masood questions whether an automation-heavy stack actually generates business.
Posts to understand this · as of Oct 21
RB2B identifies the people and companies visiting a website so sales can follow up.
RB2B climbed to a June high after a May post reported $9.1 million-plus ARR, then fell sharply through August. September recovered some ground and the last 30 days are up 28.6%; recent posts put RB2B inside repeatable outbound systems, where website visits trigger outreach, rather than center the company’s own growth story.
Posts to understand this · as of Oct 22
Intercom is a customer messaging platform built around Fin, its AI support agent.
Intercom’s March strength coincided with Fin’s observability launch; the June rebound has no clear explanation in these posts. Conversation settled at a much lower level from July through September, despite Lemkin’s account of a $3B-plus Salesforce exit. Share is down 41.8% over the last 30 days, with Robinson’s Fin-supported, one-employee RB2B offering a concrete operating example.
Posts to understand this · as of Oct 26
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
LangChain held a relatively steady share from June through September before a 43.7% decline over the last 30 days. September supplied fresh discussion through agent evaluation tests and Harrison Chase's admission that the gateway arrived late, but the posts identify no clear cause for the decline. The earlier GTM agent case study supplied concrete revenue and time savings claims.
Posts to understand this
Baseten deploys and runs custom AI models in production.
Baseten’s summer rise reached its highest monthly share in August, alongside its announcement that Inference Engineering was free to read. September brought a pullback despite Harvey’s M&A diligence partnership, and attention is down 34.8% over the last 30 days; CodeRabbit’s October NVIDIA spotlight adds another concrete application without establishing a renewed rise.
Posts to understand this · as of Oct 24
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Nooks’ share climbed from March through July, fell in August, then rebounded in September. May’s Replit example showed continued use for dialing; October posts covered customer research and infrastructure for revenue agents. Those newer topics accompany a softer current trend, with share down 13.4% over the last 30 days.
Posts to understand this · as of Oct 23
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Common Room’s steady climb culminated in July, when Zoom’s acquisition supplied a concrete news event. Share then dropped sharply in August and September; a 2.6% lift over the last 30 days leaves it far below July. The posts trace a shift from competitive replacement claims to acquisition congratulations and questions about consolidation across the GTM stack.
Posts to understand this
Exa.ai is a web search API designed for models and AI agents.
Exa’s share moved unevenly through September, then gained 64.5% over the latest 30 days. The Exa 3.0 launch gives that acceleration a clear product event, with claimed search-quality gains across coding and GTM intelligence. A subsequent CRO interview adds a growth story, while July’s outbound stack example shows an existing use for Exa in semantic prospect research.
Posts to understand this
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly's share climbed from April through July, with HubSpot's acquisition providing a concrete hook at the July high. Share dropped sharply in August and stayed low in September; the last 30 days are down another 28.6%. Later discussion places Warmly alongside Pocus and Common Room as examples of GTM consolidation, rather than supplying a fresh product story.
Posts to understand this
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode’s share rose each month from March through August, then declined in September; the last 30 days are down 18.8%, though the 90-day move remains up 92%. The evidence suggests cumulative ecosystem support rather than a single August trigger: Linear’s issue handoff, DeepSeek’s integration update, and Databricks’ Unity Gateway CLI all include OpenCode among supported coding tools.
Posts to understand this
Gamma turns prompts into presentations, documents, websites and images.
Gamma’s share roughly halved between March and September, despite recurring integration news; the last 30 days show a 44.5% rebound, with the 90-day trend still negative. No supplied October event explains that move, but the consistent thread is presentations inside existing workflows: Claude’s connector, a planned Confluence agent, and September’s two-way Jira and Confluence integration.
Posts to understand this · as of Oct 27
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps’ May spike coincided with AirOps Next and Quill, after April’s Anthropic collaboration announcement. Attention then settled into a much lower July-through-September plateau, so those events did not establish a lasting higher baseline. The last 30 days are up 41.4%, with October’s citation research supplying a practical hook around G2 profiles, buyer prompts and purchase-focused pages.
Posts to understand this · as of Oct 26
 inCitation researchAirOps research recommends separate surface metrics and audits of purchase-focused pagesA
 inAnthropic collaborationAirOps announces Anthropic collaboration and shares Claude productivity and customer resultsTM
 inEvent takeawaysTy Magnin highlights Quill’s lower learning curve after AirOps Next
1mind provides AI sales agents for websites, demos, live calls and customer success.
1mind's share declined from June through September, followed by a 114.7% lift over the last 30 days that still leaves it down 39.9% over 90 days. Its Elite Growth Summit in Napa provides a concrete recent conversation hook, with more than 100 GTM leaders. Earlier posts centered on a year of customer use and a marketing leadership hire.
Posts to understand this
Firecrawl turns websites into clean, structured data for models and agents.
Firecrawl's curve is uneven, with May and July bumps alongside a Claude Code prospecting walkthrough and praise for its free-credit onboarding. August and September settled lower, but share is up 122.1% over the last 30 days. Lovable's October inclusion adds a distribution angle to a conversation previously grounded in hands-on scraping and user acquisition.
Posts to understand this · as of Oct 24
Higgsfield generates video and images for ads and social content.
Higgsfield’s May and June rise held through July before an August drop; September recovered some ground, and the last 30 days are up 7.7%. Creator projects such as PJ Ace’s Pokémon image giveaway accompanied the summer plateau, while the October AI Influencer launch supplies a fresh product hook. Together AI’s August customer announcement did not coincide with a broader rise.
Posts to understand this · as of Oct 25
Grok Bot is an always-on agent that learns routines and completes work across existing software.
Grok Bot entered the conversation with its August early beta, then gained share in September around the promise of work across existing tools. October adds concrete creative integrations from Runway and Krea. The last 30 days are up 9.6%, consistent with a rollout that keeps adding reasons to use the bot beyond its initial pitch.
Posts to understand this · as of Oct 24
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce entered the conversation with its August launch, then gained share in September as Dreamforce put Claude alongside Slack in Salesforce’s interface story. That launch and conference sequence fits the initial rise, but attention is now down 82.7% over the last 30 days, despite Jason Lemkin’s October demo pitch for running Salesforce through agents.
Posts to understand this · as of Oct 23
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
GPT-6 went from barely present to 5.1% of conversation in September, alongside Perplexity’s strong Astra evaluation and reports of higher OpenAI spending on OpenRouter. By midmonth, Cline was already using Astra as a benchmark for a cheaper alternative. Attention is down 60% over the last 30 days after that concentrated burst of evaluation and comparison.
Posts to understand this · as of Oct 26
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Claude Fable jumped into the conversation in June, when Cognition added Fable 5 to Devin, and reached its highest full-month share in July. August’s safeguards update accompanied lower attention; September’s rebound included an Opus 5.5 comparison to Fable 5.1. Attention is now down 74.9% over the last 30 days, consistent with episodic release and comparison interest.
Posts to understand this · as of Oct 26
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
GPT-5 dropped after April and stayed at a low plateau from May through September; its last-30-day share is down 19.6%. The posts do not explain the initial drop, but they show what persists: benchmark comparisons and cost tradeoffs, including Tampa General’s reported 68% savings with GPT-5 mini and a separate critique of GPT-5 pricing.
Posts to understand this · as of Oct 24
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Claude Opus's share jumped in April, held through May, then swung through September's rebound, which coincided with Cursor adding Opus 5.5. Share is down 22.3% over the last 30 days. Recent evidence is mixed: Walker reports Opus 5.5 leading OpenRouter spending, while LILT finds Gemini 3.8 Flash ahead across tested non-English languages at under one-sixth the per-task cost.
Posts to understand this · as of Oct 26
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Grok 4's July spike lines up with Grok 4.5's arrival in Perplexity Computer and a first-place AutomationBench result shared by Zapier. Share eased in August and September, and the last 30 days are down 60.7%. An October post praising Grok 4.7's Frontier V4 result supplies fresh benchmark attention, but the broader conversation continues to contract.
Posts to understand this · as of Oct 24
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Sonnet’s June spike aligns with the Sonnet 5 launch and Legora’s early testing, then attention faded through August despite permanent introductory pricing. September recovered, and the last 30 days are up 221.2%, though the 90-day move remains negative. An October Sonnet 5.5 chess demo adds a build example, but does not alone explain the size of the recent move.
Posts to understand this · as of Oct 26
Muse Spark is Meta's AI model for running coding and other agents.
Muse Spark moved from sparse spring mentions to successive gains from July through September, and the last 30 days are up 62.8%. October supplies several reasons for attention rather than one clean success story: Baseten added Muse Spark Open, Surge compared Spark 1.3 against Mistral, and Arena reported Muse Wonder replacing it as Meta’s top model.
Posts to understand this · as of Oct 22
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Gemini Flash's May spike aligns with the 3.5 Flash release on Databricks and a leading Apex-Agents AA benchmark result. July brought another bump that these posts do not explain, followed by lower share in August and September. Wiz's September security partnership adds a concrete application, but share is down 54% over the last 30 days.
Posts to understand this · as of Oct 24
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
July’s spike coincided with Together AI’s claim that Kimi K3 matched Claude Fable 5 on software engineering tasks at roughly 35% of the price. Harvey’s August Tenet launch supplied a concrete legal use case, but share declined through September. The latest 30 days are down 6%; Arena’s October model teaser signals anticipation, not an established recovery.
Posts to understand this · as of Oct 24
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen’s summer surge topped out in August, then lost ground in September; conversation share is down another 24.7% over the last 30 days. The posts do not explain the August spike with a single event. They show recurring interest across cheaper search answers at Perplexity, local Qwen 3.8 deployments, and the September Qwen-Image-2.1 release.
Posts to understand this
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM moved from near-zero attention to a June-through-August plateau, with June posts emphasizing GLM 5.2’s coding capabilities and free access in Devin. That plateau suggests interest extended beyond one announcement, although the posts cannot explain every month. September softened despite GLM 5.3 Flash leading Bolt’s reported model usage, and attention is down 40.3% over the last 30 days.
Posts to understand this · as of Oct 26
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos shows two bursts, in April and June, followed by much lower share from July through September and a further 30.2% decline over the last 30 days. April discussion linked Mythos to Anthropic's faster product development; the evidence supplies no June trigger. September's Mythos 5.1 announcement and October's Bank of America patching account have not restored that earlier attention.
Posts to understand this
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney’s June spike coincided with Gamma showing its Midjourney-based brand system and discussion of the company’s community-funded model. Share dropped sharply in July and stayed well below June, with the last 30 days down 5.9%. September’s film example puts Midjourney inside a Claude-led workflow, but does not explain the broader decline.
Posts to understand this
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Devin’s April spike coincided with Windsurf 2.0’s launch and cloud delegation to Devin, followed by a June low and another summer rise. Conversation share is up 36.2% over the last 30 days, with Pylon’s support integration and CodeRabbit’s security comparison supplying fresh workflow and evaluation hooks; these posts do not explain the summer rise.
Posts to understand this · as of Oct 27
Runway is an AI platform for generating and editing video and images.
Runway’s share more than doubled in September after a quiet July and August, with the last 30 days up another 11.3%. No supplied post explains the September jump directly. The evidence spans solo ad production, Pika’s price comparison against Runway Dev, and October discussion of 60 Minutes coverage, rather than one identifiable launch.
Posts to understand this · as of Oct 21
Jev is TypeSafe AI's decision model, which returns typed answers such as choices, probabilities and scores instead of text.
Jev rose from no recorded share in March through August to 3.05% in September, alongside LangChain’s evaluation tests and Browser Use’s poker demo. Share is down 34.4% over the last 30 days, though Parallel’s October Decisions API announcement keeps Jev in the conversation as a comparison for fast decisions.
Posts to understand this
Muse is Meta's personal AI agent, which connects to a person's email, calendar and payments to shop, book and schedule for them.
Muse moved from almost no share in August to 1.2% in September as Notion and Stripe announced integrations for workspace updates and business payments. The last 30 days are up 222.9%; October’s discussion also includes Liza Adams’ concerns about personal agents acting without approval, so the conversation now spans both practical capabilities and trust.
Posts to understand this · as of Oct 23
Instinct is a personal AI agent with its own email address that creates accounts, contacts businesses and handles support requests for its user.
Instinct appeared in August and reached 0.8% share in September; its last-30-day gain of 67.9% shows attention continues to build. The evidence pairs September’s reported valuation sprint with October partnerships: participation in Meta and Sierra’s Personal Agent Protocol and collaboration with Decagon give the conversation substance beyond fundraising.
Posts to understand this · as of Oct 27
Muse Wonder is Meta's most capable model series, built for personal and work agents that keep track of goals across long tasks, including coding.
Muse Wonder is new in the last 30 days after no recorded share from March through September. Its early October presence has a concrete distribution story: fal demonstrated image and video connections, Genspark added it across three products, and Cursor announced availability with a CursorBench score. These clustered announcements explain its arrival, but do not yet establish sustained momentum.
Posts to understand this · as of Oct 21
Join 19,600+ GTM leaders and practitioners. Free, unsub anytime.
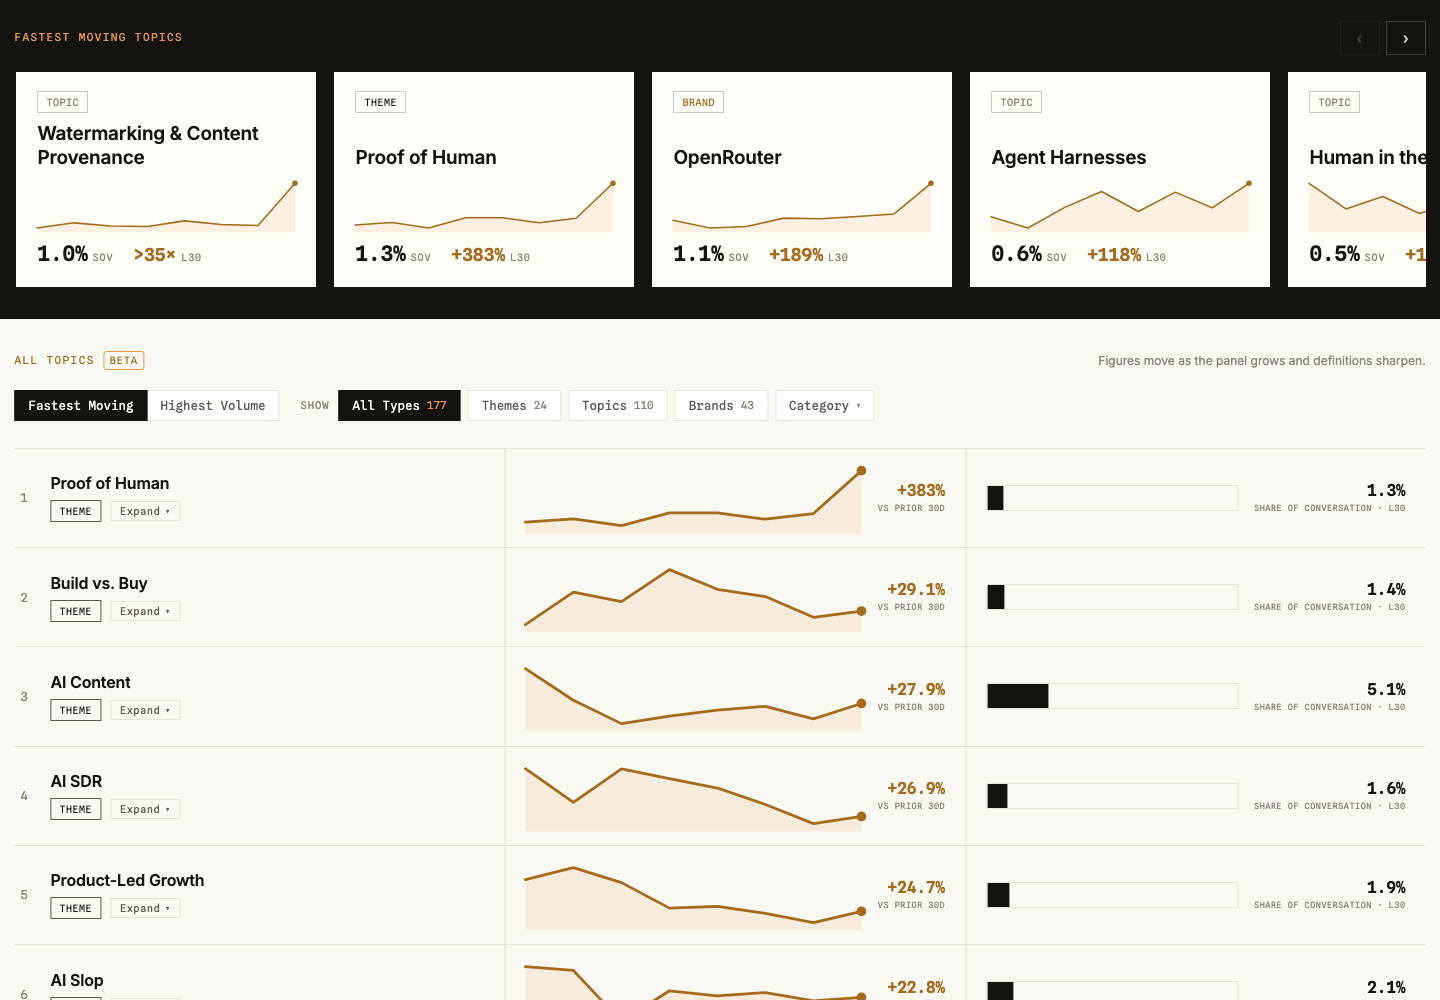
Loading people…
join 19,600+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-10-29.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,600+ gtm leaders, unsub anytime.