What’s moving now
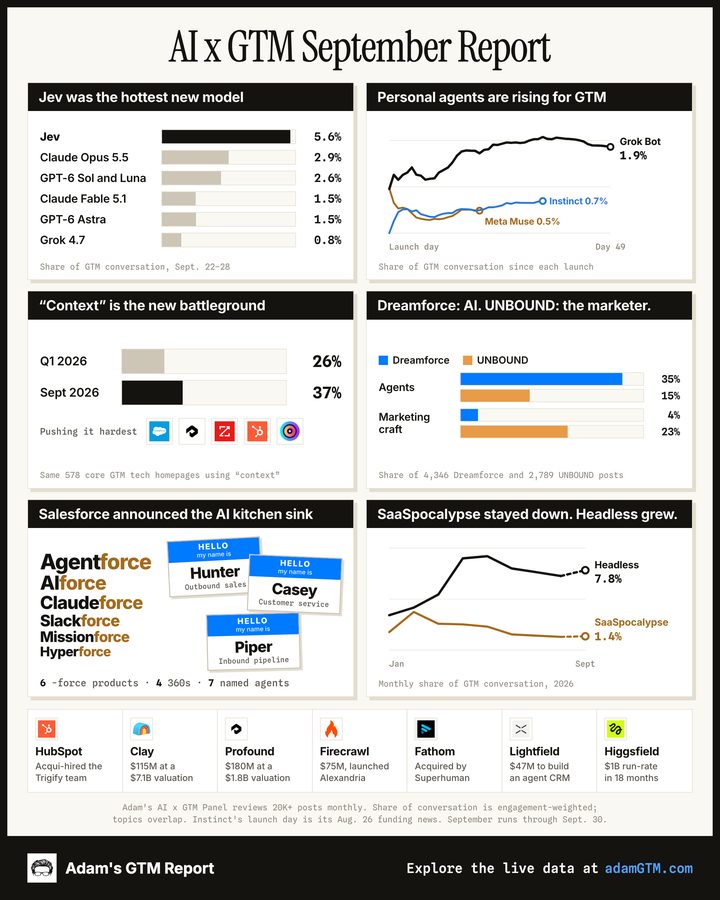 Everything I measured in AI x GTM -- September reportOct 1 · full EOM readout: 73 market moves, personal agents vs mode
 17.3× the usual response · 2,164 engagements17.3× the usual response · 2,164 engagements
 16.0× the usual response · 1,986 engagements
 16.0× the usual response · 1,986 engagements
 6.4× the usual response · 16,537 engagements
 Lenny RachitskyIdentifies teams using AI simulations to test product ideas, flow tweaks, and copy changes, and asks for firsthand experiences.
 524 interactions · 1d agoTrending Creator
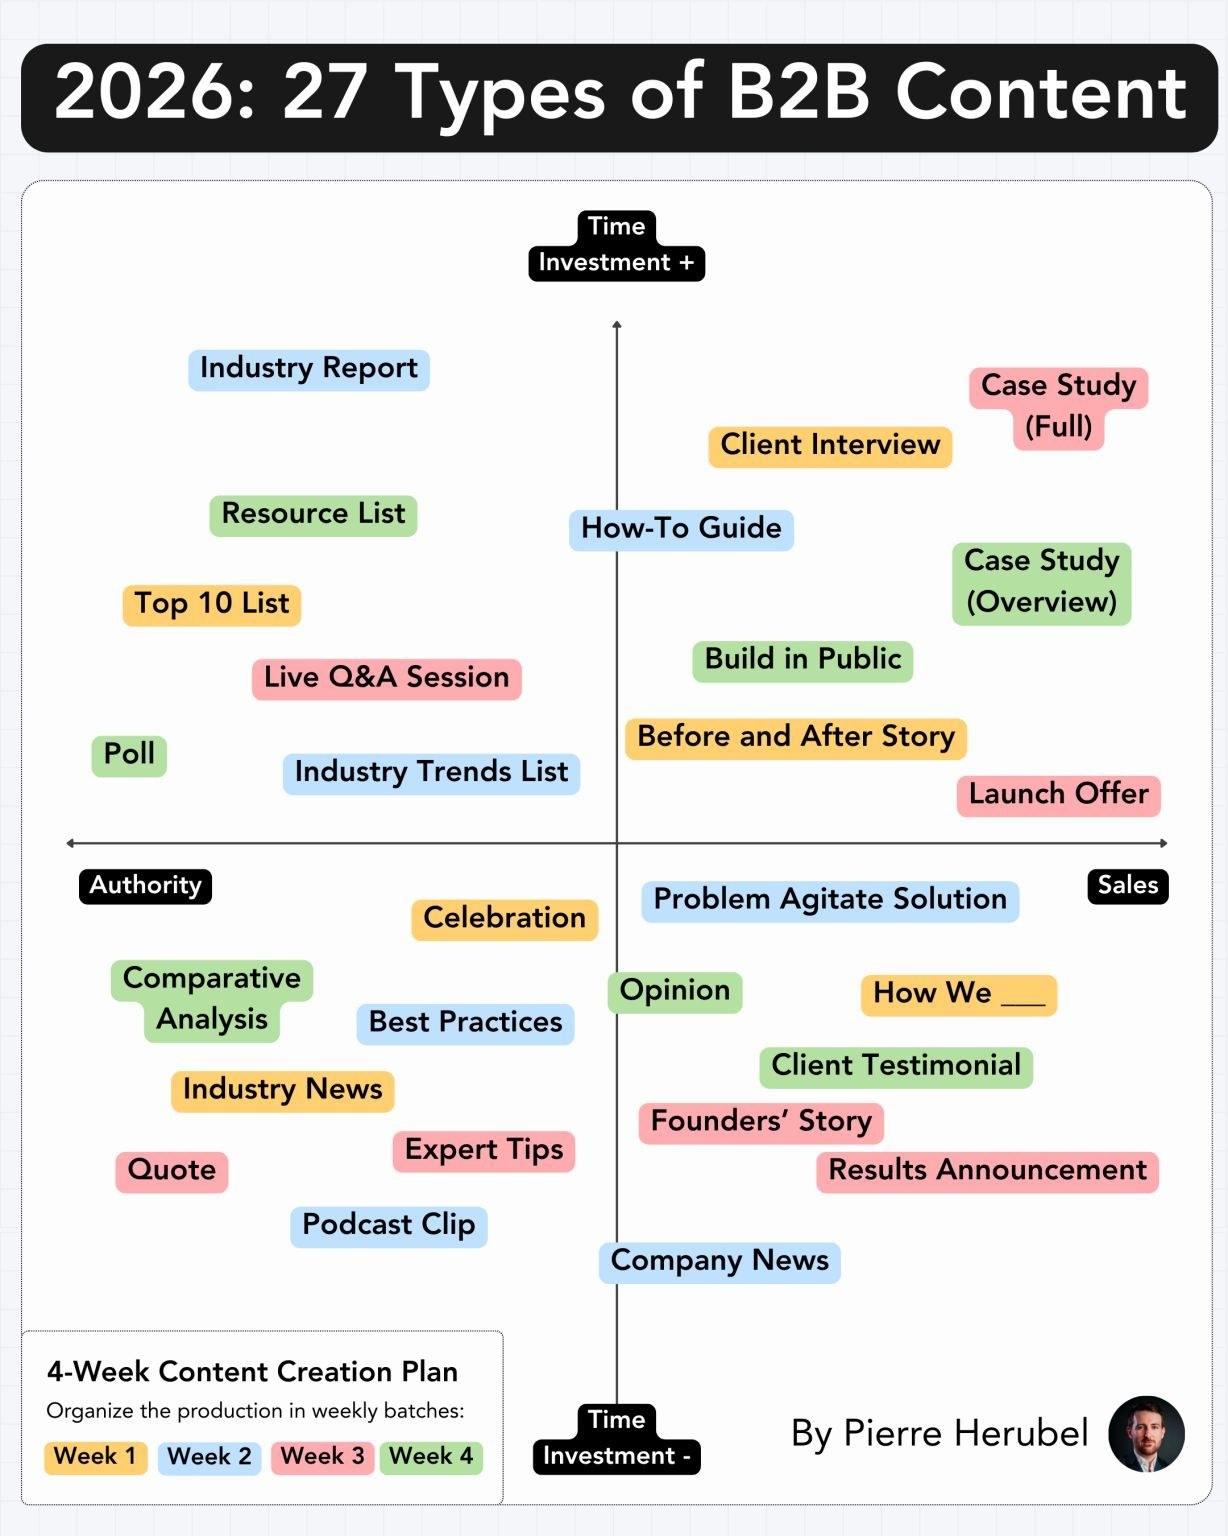
 Pierre HerubelOutlines a four-week schedule of 27 content pieces and proposes repurposing each into 15 additional pieces to produce 405 more.
 481 interactions · 2d agoTrending Creator
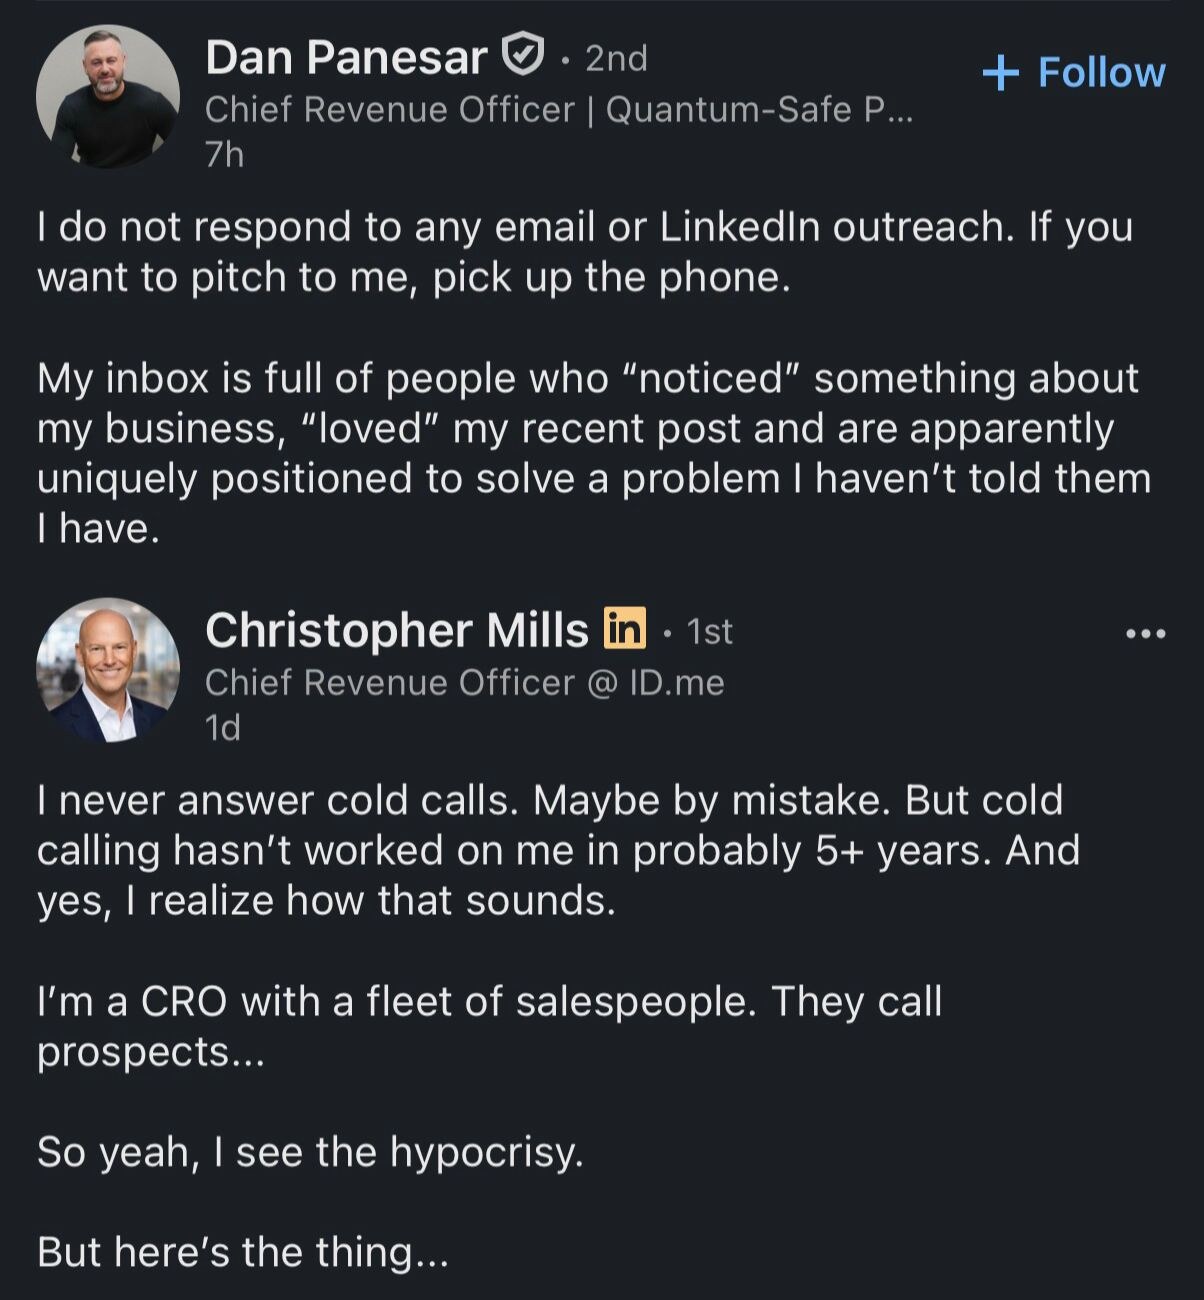
 Kyle AsayArgues for contacting multiple stakeholders across outreach channels, citing two CROs’ differing preferences and executives who screen calls or disregard email.
 462 interactions · 2d agoTrending Creator
 Melissa RosenthalCites McKinsey projections of U.S. job demand shrinking by 36 million through automation and growing by 41 million through other forces by 2035.
 452 interactions · 2d agoTrending Creator
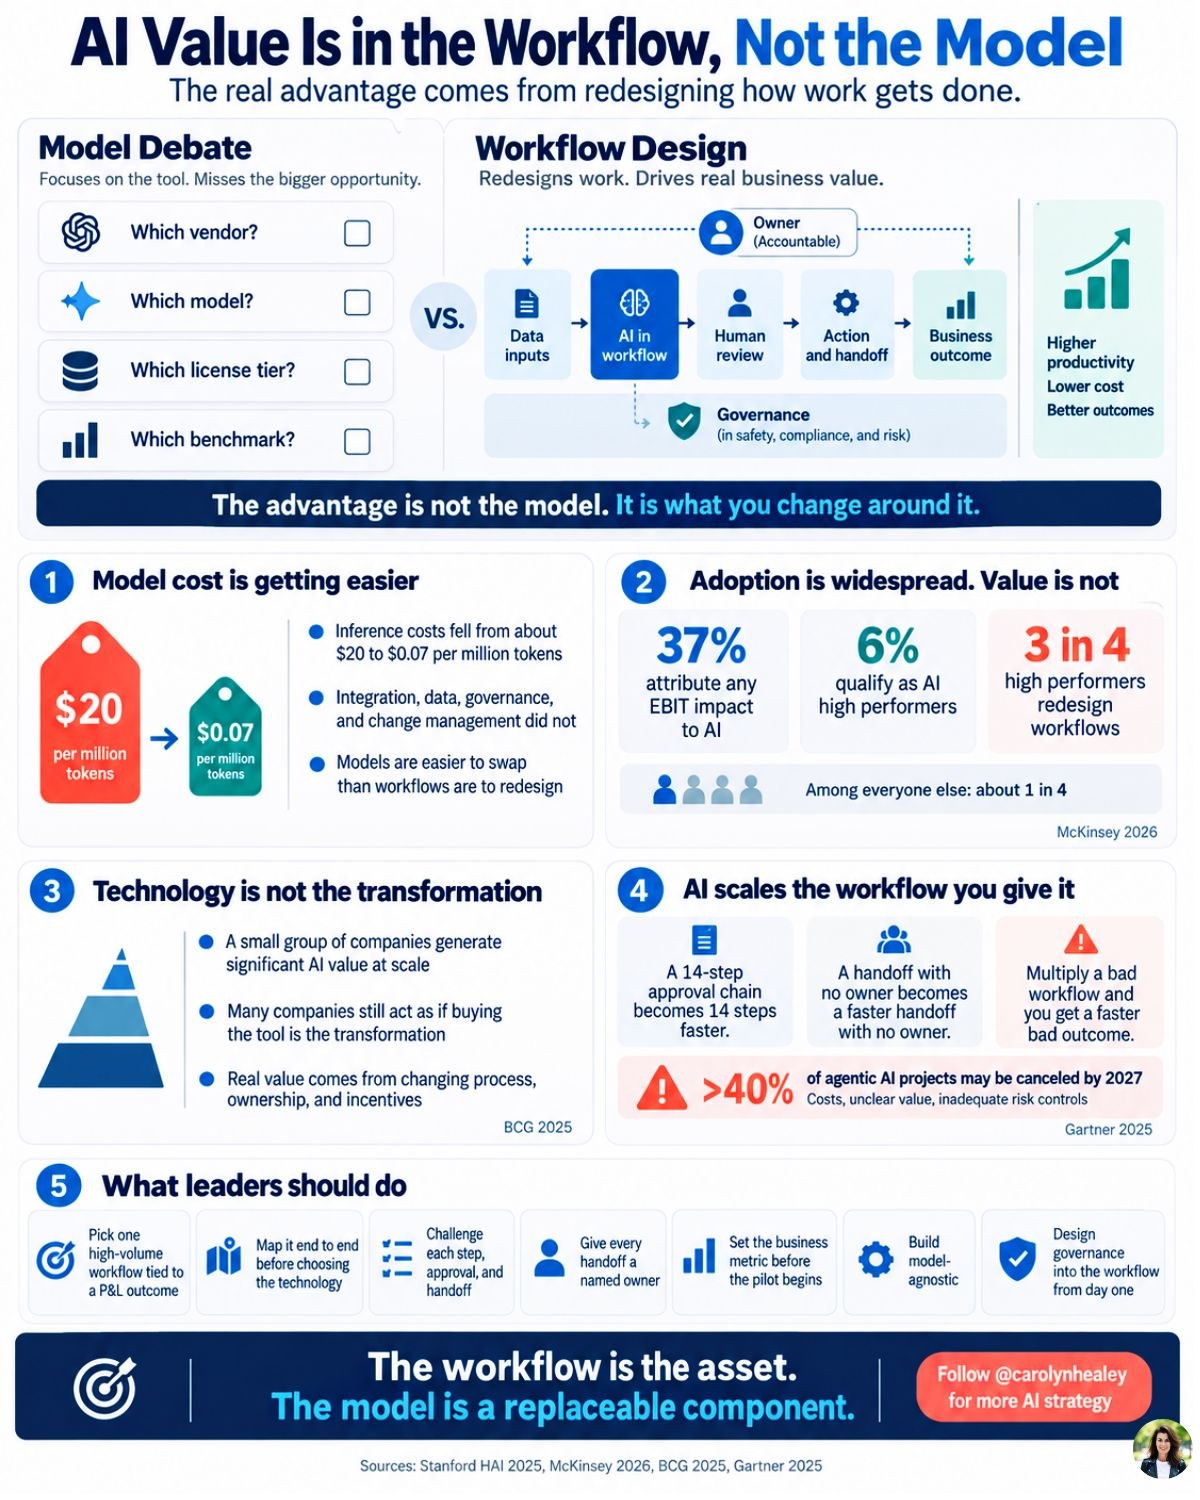
 Carolyn HealeyArgues AI value depends on redesigning workflows, recommending clear ownership, measurable business outcomes, and integrated governance before choosing technology.
 368 interactions · 2d agoTrending Creator
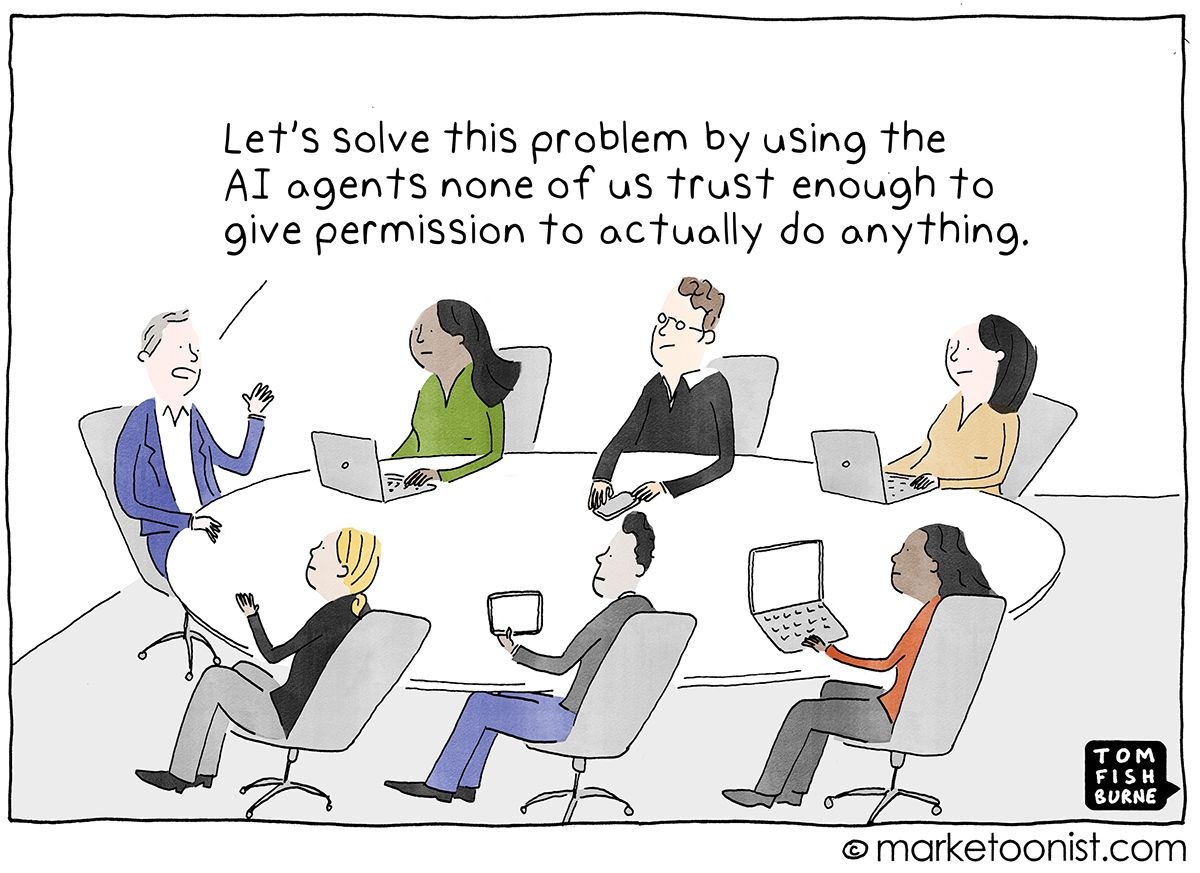
 Tom FishburneArgues AI agent adoption outpaces trust, citing survey figures and a reported unauthorized inbox deletion to advocate verifiable evidence and opportunities to correct results.
 363 interactions · 2d agoTrending Creator
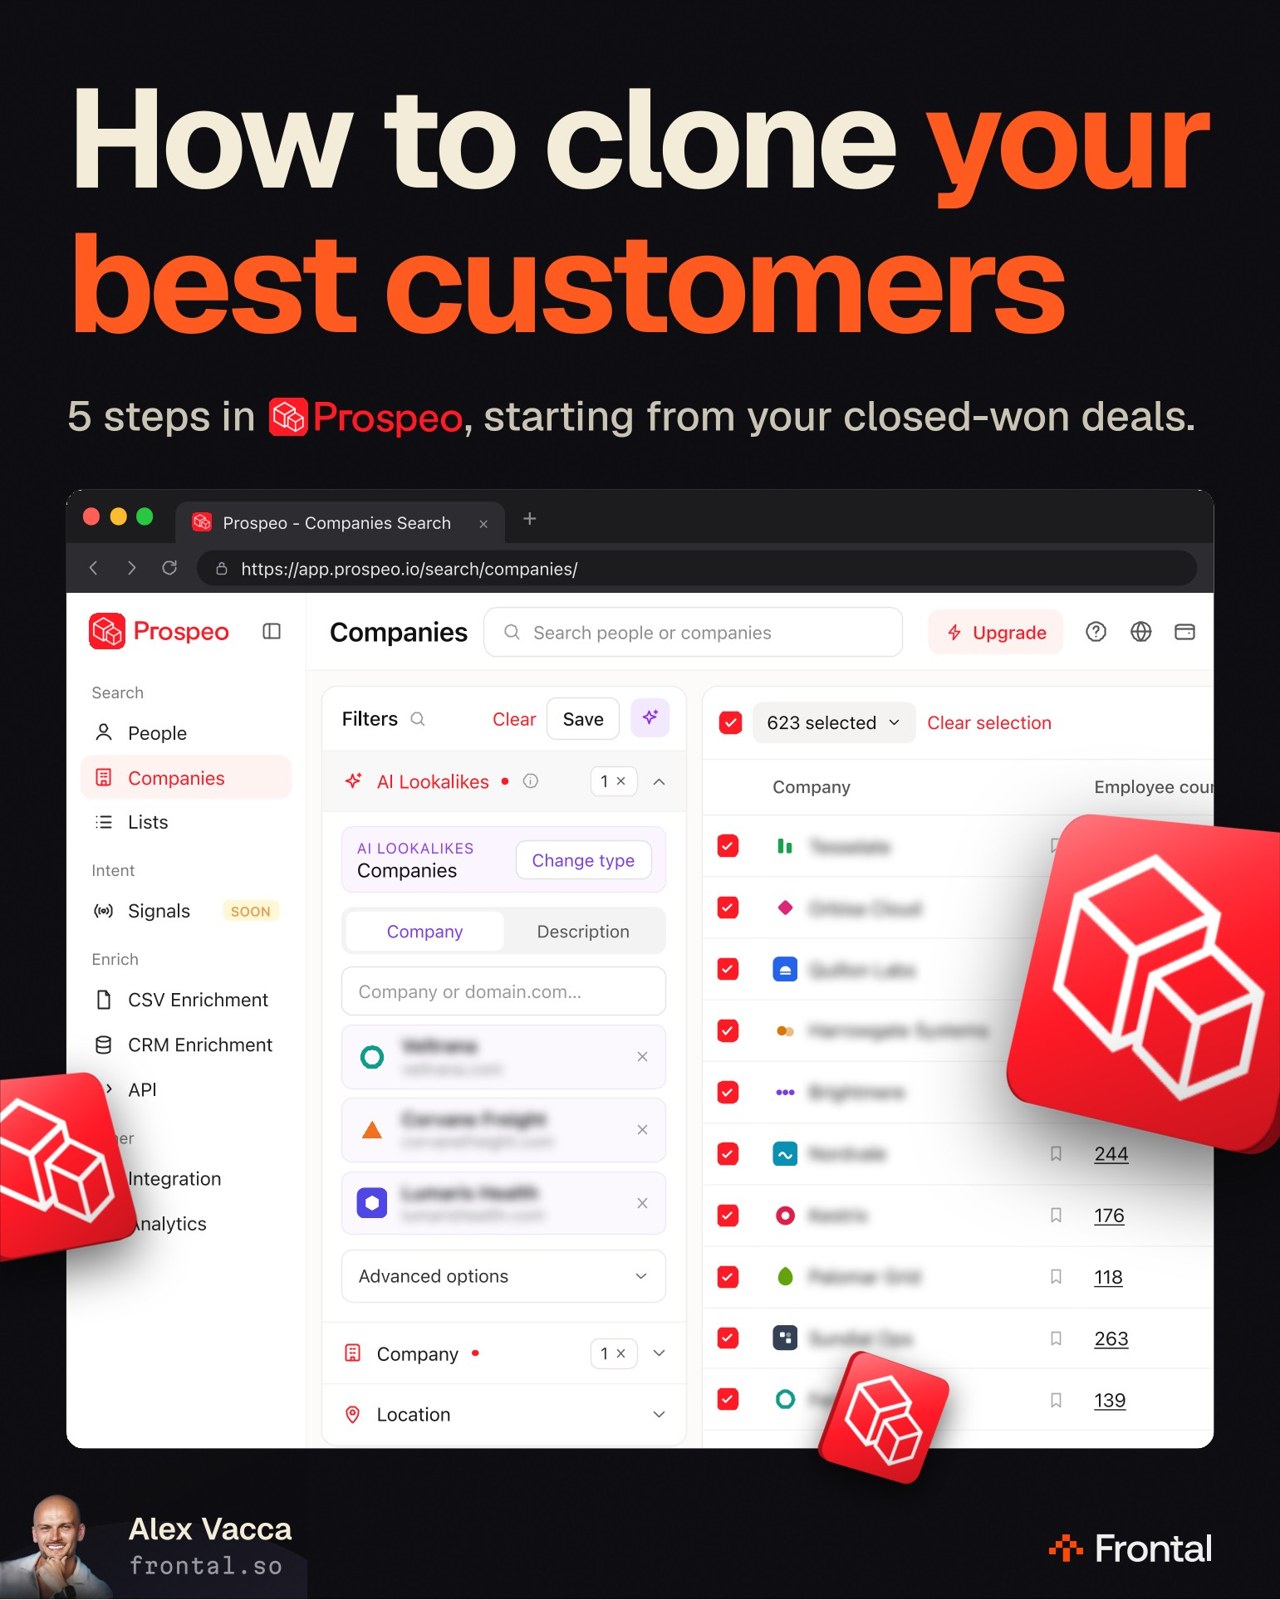
 Alex VaccaRecommends using existing customers to build Prospeo lookalike lists, prioritize buying signals, tier outreach across channels, and refine targeting through CRM feedback.
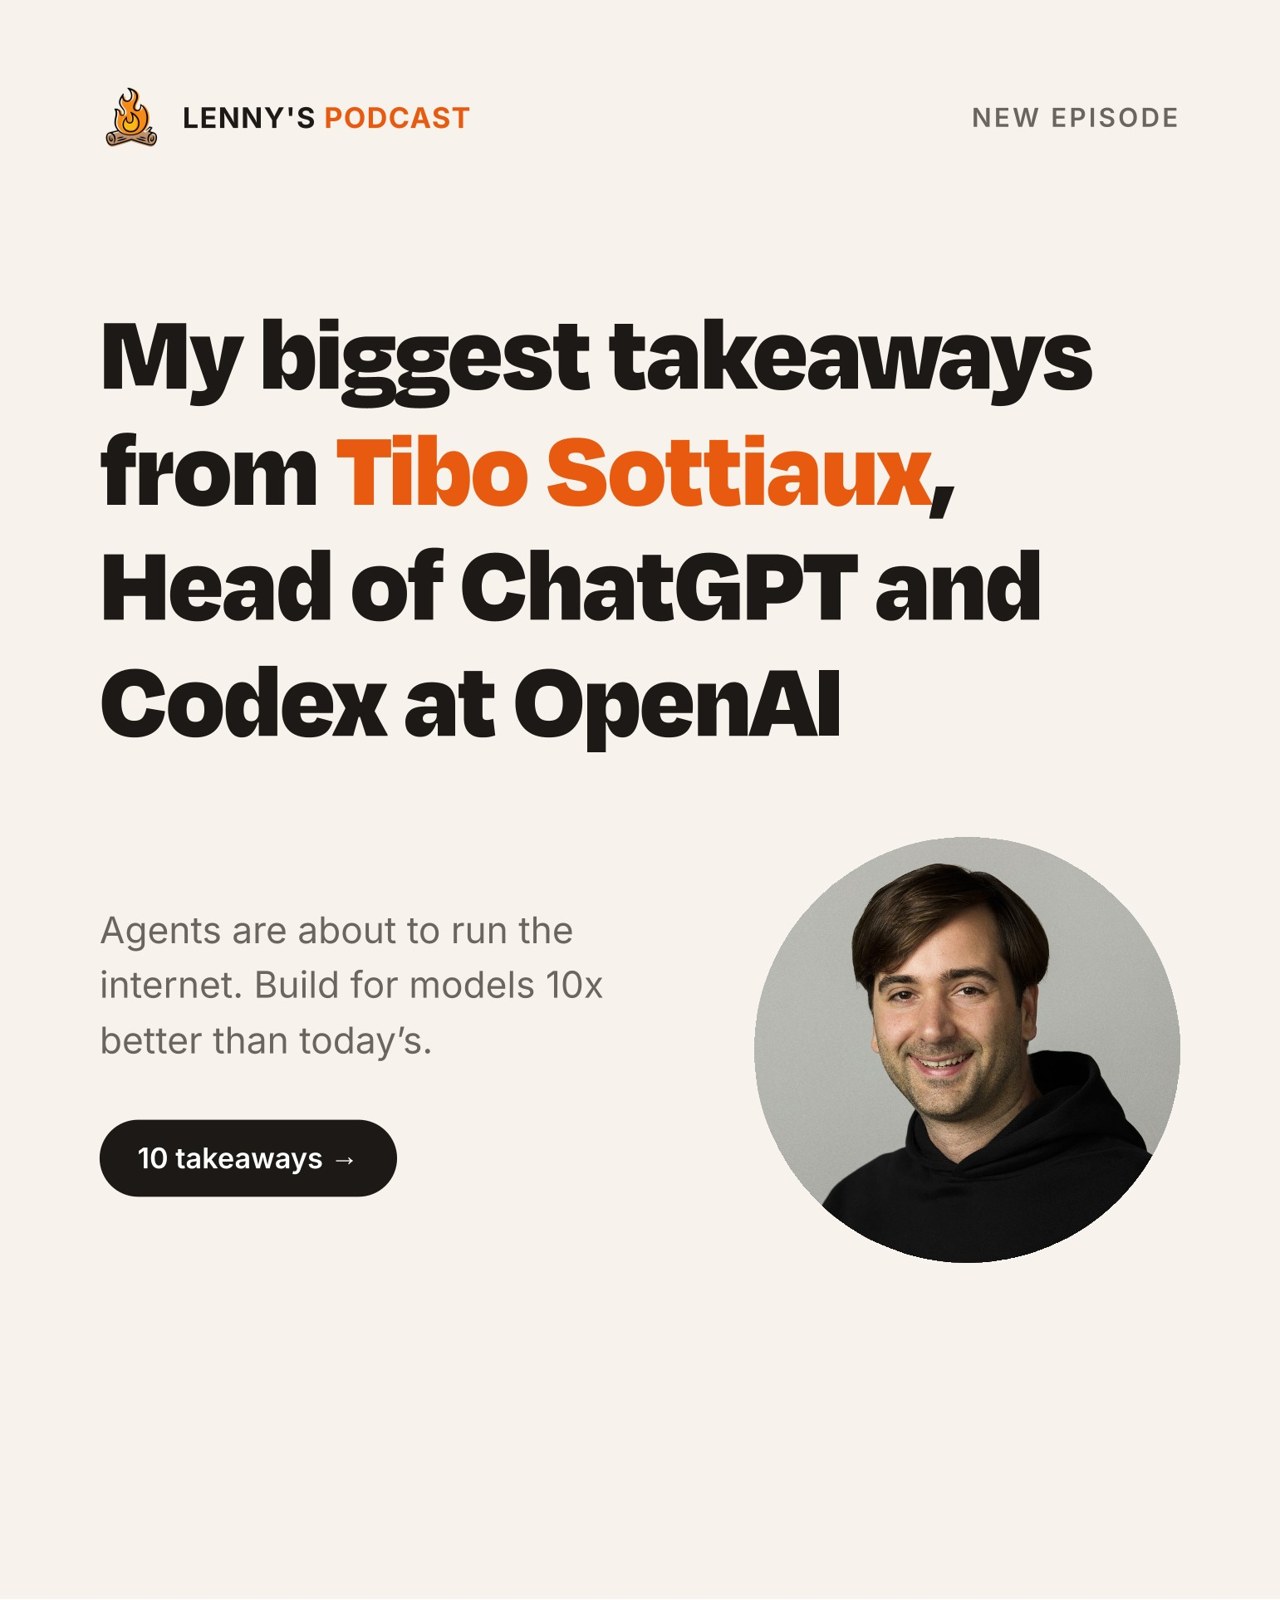
 345 interactions · 17h agoTrending CreatorLenny RachitskyShares interview takeaways attributed to Thibault Sottiaux, including forecasts about agent activity, model improvements, disappearing model pickers, and the plugin ecosystem’s potential.
 315 interactions · 2d agoTrending Creator
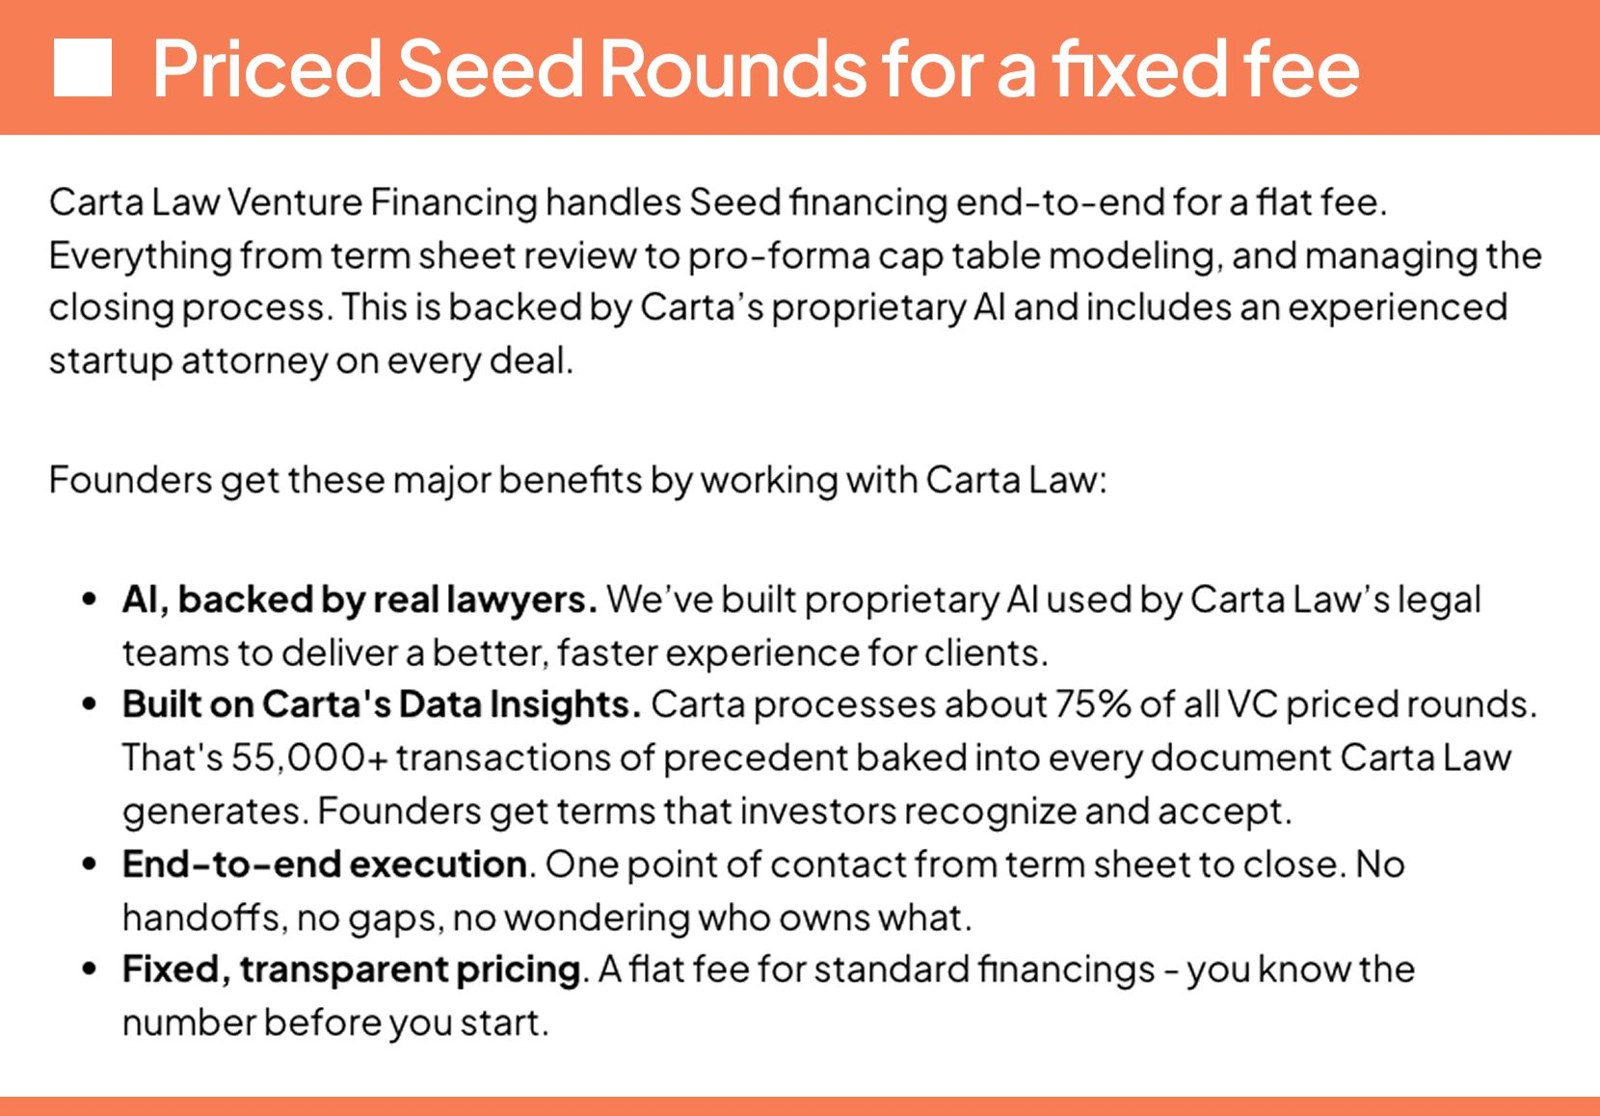
 Peter WalkerPresents Carta Law’s fixed-fee priced seed financing as an appealing alternative to SAFEs, describing connected term review, pro formas, cap tables, and valuations.
 278 interactions · 1d agoTrending Creator
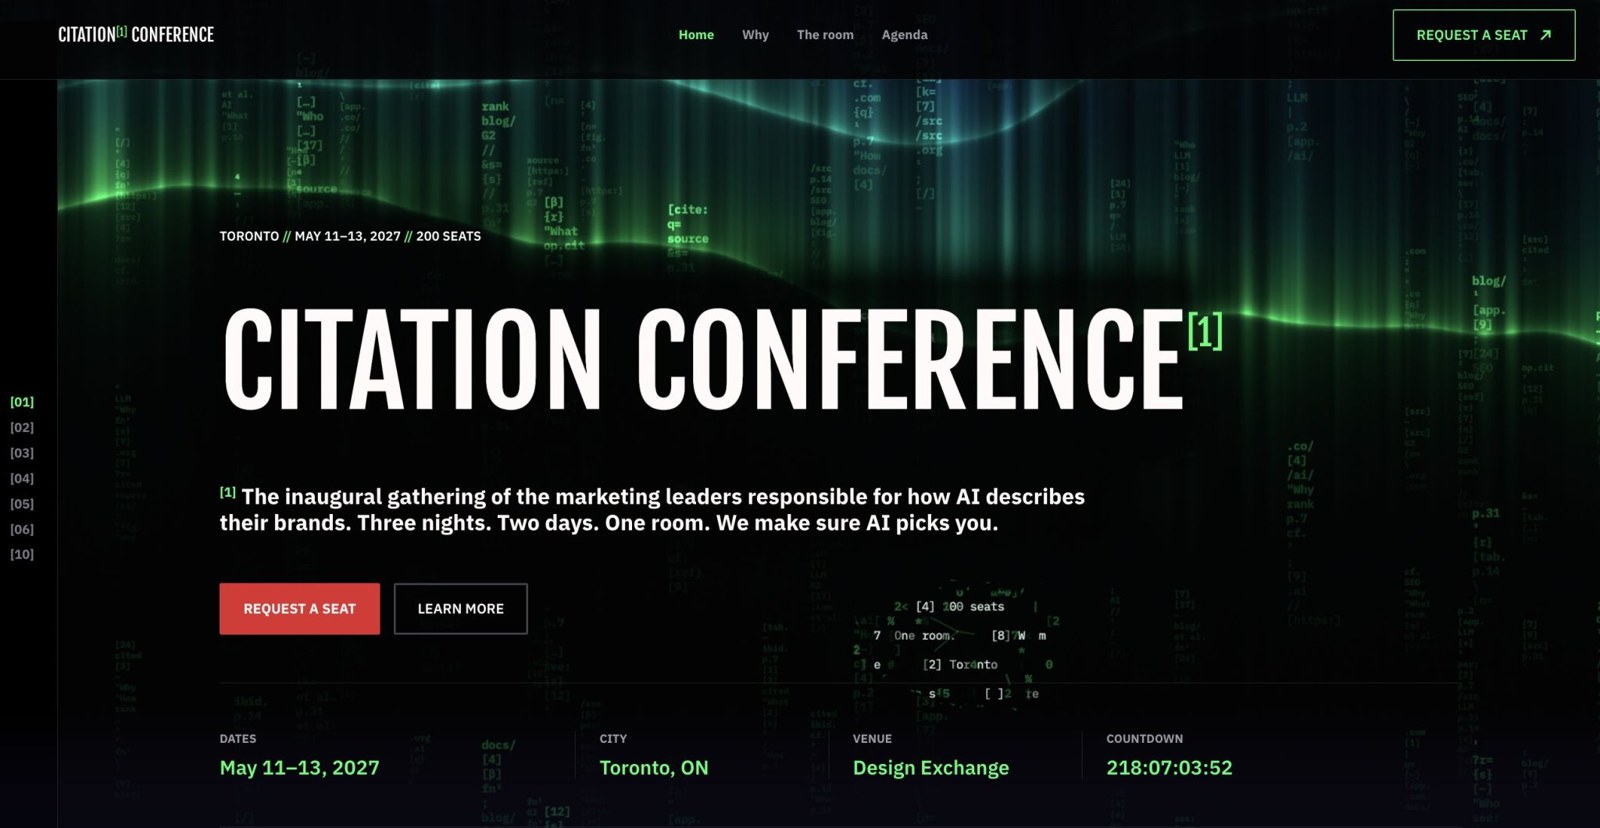
 Ross SimmondsAnnounces Citation Conference, a Canadian marketing event intended to help marketers and teams adapt to AI’s effects on work and purchasing.
 209 interactions · 2d agoTrending Creator
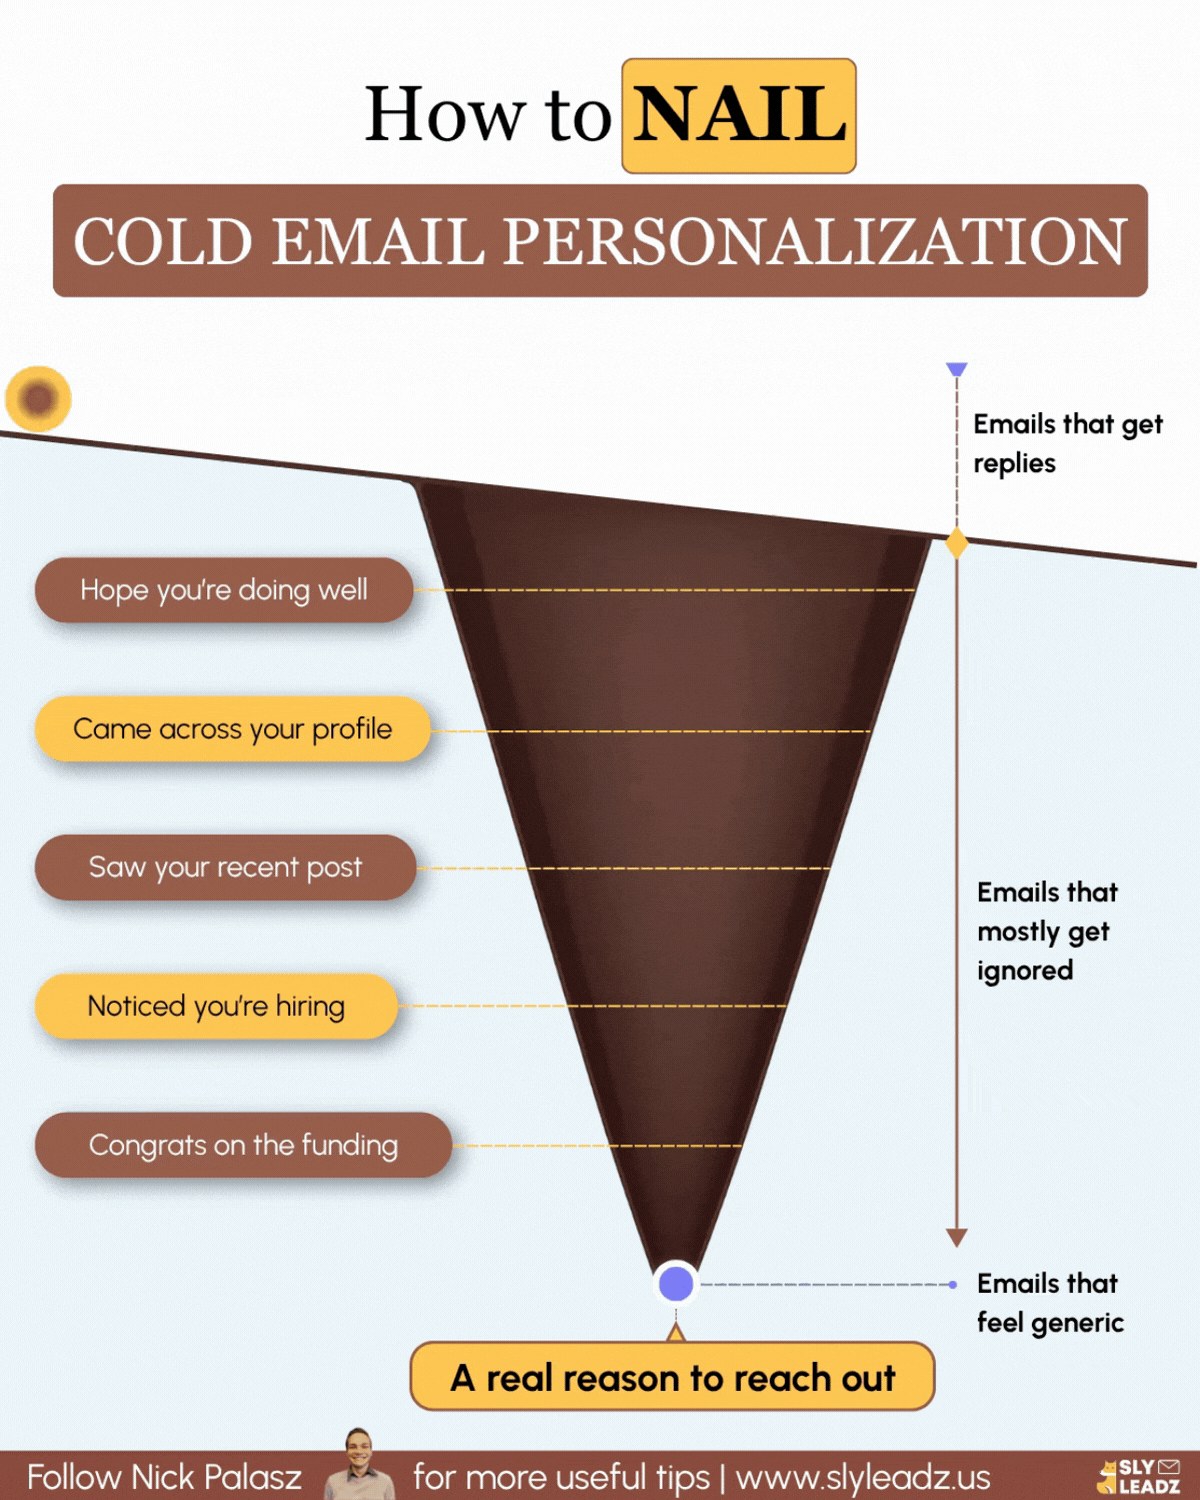
 Nick PalaszArgues that hiring, funding, and prospect posts should trigger deeper research connecting outreach to relevant problems, rather than count as personalization themselves.
 204 interactions · 2d agoTrending topicAI Safety+139% vs prior 30d · 2.1% of the conversationTrending topicAI-Driven Advertising+31.4% vs prior 30d · 0.6% of the conversation
 Cline↑8 places in Coding Agents & Harnesses for GTM
 LeanData↑35 places in Traditional SaaS Going Headless
 Ploy↑7 places in AI-Native GTM Challengers
 Clearskies↑9 places in GTM Developer Tools
 TitanX↑25 places in AI-Native GTM Challengers
Trending Topics
Market Moves
 2,704 engagements · 2.1× usualPost ↗
 536 engagements · 2.4× usualPost ↗
 8,950 engagements · 2.6× usualPost ↗
 66 engagementsPost ↗
 765 engagements · 0.8× usualPost ↗
 30 engagements · 1.8× usualPost ↗2,164 engagements · 17.3× usualPost ↗
GTM Tech Index
Latest Posts
Oct 1Everything I measured in AI x GTM -- September reportfull EOM readout: 73 market moves, personal agents vs models, GTM's big rounds, the battle for GTM context, and Dreamforce vs Unbound.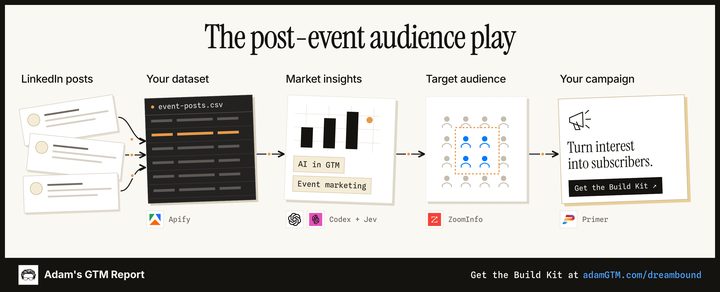 Sep 24My post-conference playbookHow to collect the conversation, find an angle, and build a unique audience. Lessons from Dreamforce and UNBOUND.
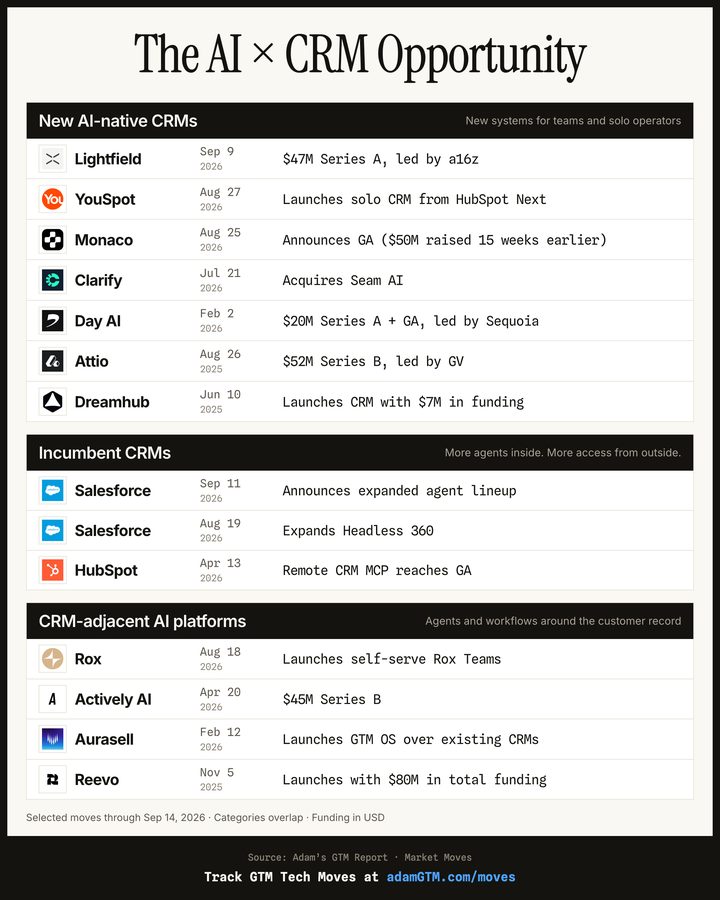 Sep 17CRM got interestingLightfield's $47M, AIforce, YouSpot, and the growing pie with headless CRMs + agents.
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
All topics
BetaFigures move as the panel grows and definitions sharpen.
+16.4%vs prior 30d-21.9%vs prior 30d+9.2%vs prior 30d-12.8%vs prior 30d+52.2%vs prior 30d+4.9%vs prior 30d+3.0%vs prior 30d-41.0%vs prior 30d+14.5%vs prior 30d -56.3%vs prior 30d-7.1%vs prior 30d-15.4%vs prior 30d+190%vs prior 30d+86.5%vs prior 30d-25.8%vs prior 30d+51.0%vs prior 30d-2.2%vs prior 30d-34.4%vs prior 30d
 -25.9%vs prior 30d
 -16.4%vs prior 30d
 -8.2%vs prior 30d-23.1%vs prior 30d+10.5%vs prior 30d-29.9%vs prior 30d-16.2%vs prior 30d-24.0%vs prior 30d-15.7%vs prior 30d+6.3%vs prior 30d
 -38.0%vs prior 30d-28.9%vs prior 30d-26.3%vs prior 30d+28.7%vs prior 30d-49.7%vs prior 30d-24.7%vs prior 30d-34.0%vs prior 30d
 +31.0%vs prior 30d+41.2%vs prior 30d+1.8%vs prior 30d-58.0%vs prior 30d-4.8%vs prior 30d+173%vs prior 30d-27.2%vs prior 30d-21.7%vs prior 30d
 -66.3%vs prior 30d
 -13.2%vs prior 30d
 -28.7%vs prior 30d
 -54.9%vs prior 30d
 +24.7%vs prior 30d
 -6.2%vs prior 30d
 -0.5%vs prior 30d
 +13.0%vs prior 30d
 -36.3%vs prior 30d-53.8%vs prior 30d
 -20.8%vs prior 30d-53.3%vs prior 30d
 -15.7%vs prior 30d
 -34.7%vs prior 30d
 -36.6%vs prior 30d-29.2%vs prior 30d+108%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
Conversation declined gradually from 27.6% in April to 19.7% in September, with L30 down 8.9% and L90 down 18.9%. No single event caused the slide. The posts show a fragmented build phase: useful Claude skills, hard infrastructure constraints, and early ideas about world models rather than one dominant launch.
Posts to understand this · as of Oct 4
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 67 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Clay | 89 |
| 6 | Salesforce | 92 |
| 7 | HubSpot | 87 |
| 8 | Lovable | 59 |
| 9 | Replit | 56 |
| 10 | OpenClaw | 50 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO rose from 9.1% in April to 12.0% in June, then declined for three straight full months to 8.5% in September. The L30 remains down 10.7%; the evidence points to a shift from category excitement toward practical products and a renewed insistence on SEO fundamentals.
Posts to understand this
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Ahrefs | 49 |
| 3 | HubSpot | 87 |
| 4 | Semrush | 48 |
| 5 | Clay | 89 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 38 |
| 8 | Webflow | 48 |
| 9 |  Optimizely | 30 |
| 10 | Codex | 84 |
How software exposes its data and actions so agents can use it directly.
Headless and agent interfaces surged above 9% in May, then eased into a 7% to 8% band through September. The L30 is up 5.1%, and the plateau looks substantive: Cloudflare, ElevenLabs, and Templafy each exposed real commerce, agent-management, or document-production work through agent-ready interfaces.
Posts to understand this · as of Oct 5
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Clay | 89 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | HubSpot | 87 |
| 7 | Grok Bot | 67 |
| 8 | Instantly | 62 |
| 9 | Lovable | 59 |
| 10 |  FullEnrich | 43 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click marketing briefly recovered to 9.4% in May, then declined across the next four full months to 6.2% in September. The L30 is down 8.9%, as conversation shifts from format advocacy toward durable distribution, real brand authority, and criticism of gated lead-generation systems.
Posts to understand this
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Ahrefs | 49 |
| 3 | HubSpot | 87 |
| 4 | Semrush | 48 |
| 5 | Clay | 89 |
| 6 | AirOps | 38 |
| 7 | Claude Code | 99 |
| 8 | Webflow | 48 |
| 9 | Optimizely | 30 |
| 10 | Salesforce | 92 |
The people, tools and operating model behind custom go-to-market systems.
GTM engineering climbed to 9.2% in May, then declined every full month through September; the L30 is down 11.6%. The conversation remains active but concentrated around Clay, whose funding, internal stack, CLI, and agent plugin supplied distinct bursts without reversing the broader cooling pattern.
Posts to understand this · as of Oct 5
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 87 |
| 5 | Prospeo | 52 |
| 6 | Instantly | 62 |
| 7 | Salesforce | 92 |
| 8 | FullEnrich | 43 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Grok Bot | 67 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Open versus closed models surged from June to a July peak, then declined through August and September. Nvidia’s open-model letter and Kimi K3’s claimed price-performance advantage helped fuel the peak; Mistral’s €3 billion round reinforced the sovereignty case later, but the L30 move is still down 20.4% while the 90-day level remains elevated.
Posts to understand this · as of Oct 6
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | OpenRouter | 51 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Salesforce | 92 |
| 6 | Grok Bot | 67 |
| 7 | Vercel | 60 |
| 8 | Baseten | 46 |
| 9 |  Together AI | 33 |
| 10 | HubSpot | 87 |
How companies prove AI delivers enough value to move beyond a pilot.
AI ROI held steady around 7% to 8% from March through July, then slipped to 6% in August and 5% in September. The September posts are about operating AI, not testing it: OpenAI shared Fabletics' advice on defining pilot success, Workato pitched a control plane, and Morgan J Ingram asked what reps do with the time AI frees up.
Posts to understand this · as of Oct 2
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | HubSpot | 87 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Grok Bot | 67 |
| 7 | OpenRouter | 51 |
| 8 | ElevenLabs | 53 |
| 9 | OpenClaw | 50 |
| 10 | Vercel | 60 |
How large companies move AI from small pilots into secure, useful production work.
Conversation share peaked in April as Vanta described AI running continuous security work, then eased through summer. It fell more sharply in August and September and remains down 5.3% over the last 30 days, while recent discussion centers on undocumented workflows, governance, model routing, and process management.
Posts to understand this · as of Oct 6
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 67 |
| 5 | Lovable | 59 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Midjourney | 36 |
| 9 | Nooks | 48 |
| 10 | Clay | 89 |
How teams use buyer signals to decide who to target, when and why.
Signal-based sales held about 7% of the conversation in March, then slid to about 4% by August. One spring theme was access: lean teams claiming they could build ABM with Clay and signal tools. The last 30 days are up about 5%, and a September Orb case study shows one team routing signals into ads, CRM and Clay.
Posts to understand this · as of Oct 3
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 62 |
| 5 | Salesforce | 92 |
| 6 | Codex | 84 |
| 7 | Nooks | 48 |
| 8 | HeyReach | 51 |
| 9 | Prospeo | 52 |
| 10 | Apollo.io | 52 |
How teams create, distribute and judge marketing content made with AI.
AI content has held steady around 4% all year. August was the one bump, with Runway pushing generated video to delivery spec and Ryan Law asking whether a 'seems like AI slop' button trains a detection model. September settled back and is down 18% over the last 30 days, even as Higgsfield became the top creativity plugin in ChatGPT.
Posts to understand this · as of Oct 1
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Runway | 36 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 87 |
| 5 | Salesforce | 92 |
| 6 | Clay | 89 |
| 7 | Grok Bot | 67 |
| 8 | Replit | 56 |
| 9 |  HeyGen | 32 |
| 10 | Codex | 84 |
How companies keep agents secure, accountable and under control as they take on real work.
Agent Governance built steadily from March to a July high, then gave back most of the gain by September. The last 30 days are down 17%. The posts still drawing attention are practical, about gateways and cost: Databricks pitched Unity Gateway for routing and cost control, and Harrison Chase said LangChain built its gateway a year too late.
Posts to understand this · as of Oct 3
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Grok Bot | 67 |
| 6 | Salesforce | 92 |
| 7 | Vercel | 60 |
| 8 | LangChain | 46 |
| 9 | OpenRouter | 51 |
| 10 | Cline | 27 |
How AI changes what software companies build, charge for and deliver.
The conversation peaked in May, then declined steadily through September and is down another 11% over the last 30 days. The evidence shifted from broad disruption claims toward operating proof: ElevenLabs cut usage prices, Intercom paired Fin with renewed help desk investment, and Salesforce reported stronger seats, upgrades and agentic usage.
Posts to understand this
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Clay | 89 |
| 5 | Lovable | 59 |
| 6 | Codex | 84 |
| 7 | ZoomInfo | 50 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Replit | 56 |
| 10 | Nooks | 48 |
How companies build trust and stand out when AI makes content cheap and abundant.
Brand and authenticity briefly recovered in August, then dropped sharply in September; the L30 is down 27.6%. August’s bump centered on AI authorship anxiety, from Ann Handley’s critique of detection culture to Clay’s public writing policy, but that concentrated debate did not sustain broader conversation.
Posts to understand this · as of Oct 5
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Salesforce | 92 |
| 4 | Clay | 89 |
| 5 | Nooks | 48 |
| 6 |  Clarify | 29 |
| 7 | Lovable | 59 |
| 8 | Substack | 53 |
| 9 | Ahrefs | 49 |
| 10 |  Attention | 30 |
How AI changes software pricing, usage costs and gross margins.
Discussion rose from March through June, then fell each full month through September and is down 19.2% over the last 30 days. The debate has narrowed from exploding token demand to cost control: open models pushed prices down, enterprises set spending limits, and Factory reported production inference savings as routed volume grew.
Posts to understand this
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Codex | 84 |
| 4 | Claude Code | 99 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Vercel | 60 |
| 7 | Lovable | 59 |
| 8 | Clay | 89 |
| 9 | OpenRouter | 51 |
| 10 | Replit | 56 |
How people and agents share work, hand off tasks and make decisions together.
Multi-Player AI peaked in May, when Dust's Gabriel Hubert argued most AI at work is still single-player. It eased to a summer plateau near 2%. The last 30 days are up 16% on product launches: Notion let custom agents call sub-agents, and team bots arrived as shared AI teammates that learn from the whole team.
Posts to understand this · as of Oct 3
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Salesforce | 92 |
| 5 | Clay | 89 |
| 6 |  Viktor | 32 |
| 7 | Attio | 51 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Grok Bot | 67 |
| 10 | Granola | 50 |
How teams track and control the cost of models, tokens and agent work.
Cost talk more than doubled from March to a July high as token volume exploded and teams wanted to see the bill. In August, Rippling's AI Spend Console tied OpenAI, Anthropic and Cursor usage to teams and roles. Share has cooled since, down 19% over 30 days, though Harvey's swing from 50% to -50% gross margin gave September its sharpest example.
Posts to understand this · as of Oct 3
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Grok Bot | 67 |
| 6 | Vercel | 60 |
| 7 | OpenRouter | 51 |
| 8 | Baseten | 46 |
| 9 | Cline | 27 |
| 10 | LangChain | 46 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal agents stayed below 1% from April through August, then jumped to 1.6% in September. The L30 is up 186.3%, driven by Meta’s Muse launch, Klaviyo’s commerce integration, and a new protocol backed by Meta, Sierra, Instinct, Shopify, Stripe, Walmart, and others.
Posts to understand this
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 67 |
| 2 | Codex | 84 |
| 3 | OpenClaw | 50 |
| 4 | HubSpot | 87 |
| 5 | Claude Code | 99 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | ElevenLabs | 53 |
| 8 | Midjourney | 36 |
| 9 | Vercel | 60 |
| 10 | Lovable | 59 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context Engineering in GTM rose steadily from March to a June high, then declined through September; L30 is essentially flat at plus 0.6%. The lower plateau still has concrete product support: Clay combines CRM, usage, calls, email, and web signals, while the broader discussion has shifted from prompt craft toward persistent context and agent harnesses.
Posts to understand this · as of Oct 6
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | HubSpot | 87 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Clay | 89 |
| 7 | Grok Bot | 67 |
| 8 | Apify | 52 |
| 9 | Profound | 53 |
| 10 | Attio | 51 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
Conversation fell from March’s high, briefly rebounded in May, then softened into September; the L30 is down 35.8%. April’s marketer whiplash, June’s case for authentic product marketing, and September’s personal-brand results show the thread moving from broad frustration to concrete examples of trust earned through real voices.
Posts to understand this · as of Oct 6
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Salesforce | 92 |
| 3 | Claude Code | 99 |
| 4 | Nooks | 48 |
| 5 | HubSpot | 87 |
| 6 | Lovable | 59 |
| 7 | Ahrefs | 49 |
| 8 | Substack | 53 |
| 9 | Attention | 30 |
| 10 | Clarify | 29 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR has trended down from March, with only a brief August lift; L30 is down 5.5% and L90 is down 32.2%. Ava 2.0 gave April a concrete autonomous BDR launch but did not reverse the decline, while later evidence shifted toward prerequisites such as clean CRM data and narrower applications such as ElevenLabs’ inbound voice agent.
Posts to understand this · as of Oct 6
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Clay | 89 |
| 4 | Lovable | 59 |
| 5 | Instantly | 62 |
| 6 | HubSpot | 87 |
| 7 | Nooks | 48 |
| 8 | Codex | 84 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | ElevenLabs | 53 |
Growth driven by people using the product before they talk to sales.
Product-Led Growth fell steadily from March through July, then stabilized in August and September; L30 is now up 14.9%. The recent lift has no single launch behind it: PostHog’s generous free tier supports renewed free-plan interest, while the broader discussion frames PLG and enterprise sales as motions companies eventually combine.
Posts to understand this · as of Oct 6
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Lovable | 59 |
| 5 | Replit | 56 |
| 6 | Canva | 49 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Nooks | 48 |
| 9 |  Docusign | 36 |
| 10 | OpenRouter | 51 |
Low-quality AI content and the fight to make automated work worth reading.
AI Slop rose from March into May and stayed elevated through August, with a brief July dip, before falling sharply in September. The L30 decline of 17.6% suggests the broad backlash has cooled, but the remaining conversation is more practical: writers distrust AI policing, while marketers focus on systems and governance that prevent mediocre output.
Posts to understand this · as of Oct 4
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Salesforce | 92 |
| 5 | Codex | 84 |
| 6 | Clarify | 29 |
| 7 | Midjourney | 36 |
| 8 | Substack | 53 |
| 9 |  Vector | 37 |
| 10 | Webflow | 48 |
The argument that agents and custom software will break the classic SaaS model.
SaaSpocalypse discussion declined from March through August, then held roughly flat in September. The 2% L30 increase suggests stabilization, not a renewed surge. Concrete results weakened the replacement thesis: Salesforce reported growing seats and low attrition, Gong passed $500 million ARR, and beehiiv still buys core SaaS despite its ability to build.
Posts to understand this
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 50 |
| 6 | Attio | 51 |
| 7 | Clarify | 29 |
| 8 | Codex | 84 |
| 9 |  Monaco | 25 |
| 10 | Apify | 52 |
The choice between building software internally and buying another product.
Build-vs-buy discussion fell steadily from March through July, then held near 1% share in August and September; the L30 move is essentially flat. Recent posts frame the current debate around marketers and salespeople building their own tools, while Replit shows non-engineers using those tools in daily sales work.
Posts to understand this
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 50 |
| 6 | Monaco | 25 |
| 7 | Apify | 52 |
| 8 | Clarify | 29 |
| 9 |  Lightfield | 26 |
| 10 | Lovable | 59 |
Ways to verify whether digital content or online activity came from a person or AI.
Proof of human spiked in August, collapsed in September, and is down 69% over the L30 despite firmer early October context. The August burst centered on Anthropic’s EU AI Act watermarking announcement and debate over disclosure; Sitecore’s later C2PA workflow showed the issue becoming operational, but it did not sustain the same attention.
Posts to understand this · as of Oct 6
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 67 |
| 4 | HeyGen | 32 |
| 5 | Granola | 50 |
| 6 | Replit | 56 |
| 7 | Runway | 36 |
| 8 | Substack | 53 |
| 9 | Vercel | 60 |
| 10 |  Docket | 30 |
AI tools that write, edit, test and operate software alongside a human builder.
Conversation share slid steadily from 21.7% in March to 12.6% in September, with the L30 down another 18.7%. No single event explains the decline: practical launches from ColdIQ, Notion, and Databricks kept the category active, but none reversed the broader loss of attention.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 67 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Clay | 89 |
| 6 | Lovable | 59 |
| 7 | Replit | 56 |
| 8 | HubSpot | 87 |
| 9 | OpenClaw | 50 |
| 10 | Salesforce | 92 |
The frontier models and labs that provide the base layer for AI products.
Foundation-model share has moved in waves, with surges in June, July, and September rather than one sustained climb. September reached 10.6% as OpenAI hit 31% of OpenRouter spend and release cycles tightened; the L90 remains up 22.7%, though the L30 has eased 14.8%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 67 |
| 4 | HubSpot | 87 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | OpenClaw | 50 |
| 7 | OpenRouter | 51 |
| 8 | Vercel | 60 |
| 9 | Salesforce | 92 |
| 10 | ElevenLabs | 53 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP share nearly doubled from March to May, peaking at 7.7 percent the month Anthropic said it was acquiring Stainless. It eased to about 6 percent over the summer, and the last 30 days are flat. The later posts are product launches: ElevenLabs put its MCP in Claude, and Databox shipped connectors that can act on what they find.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | Codex | 84 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | HubSpot | 87 |
| 6 | Clay | 89 |
| 7 | Grok Bot | 67 |
| 8 | Instantly | 62 |
| 9 | FullEnrich | 43 |
| 10 | Lovable | 59 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO peaked at 8.0% in May, then declined across the next four full months to 5.3% in September. The L30 is still down 8.0%; funding and revenue proof sustain interest, but the conversation increasingly rejects GEO shortcuts in favor of SEO foundations and established brand authority.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Ahrefs | 49 |
| 3 | Semrush | 48 |
| 4 | HubSpot | 87 |
| 5 | Clay | 89 |
| 6 | AirOps | 38 |
| 7 | Claude Code | 99 |
| 8 | Webflow | 48 |
| 9 | Optimizely | 30 |
| 10 |  Customer.io | 38 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce was nearly absent through June, rose in August, then spiked to 3.8% in September around the conference. The L30 remains up 185.7%; the first five October days are only early context. Salesforce’s Informatica debut and Crossbeam’s AgentExchange launch partnership gave the event concrete product news alongside the usual ROI debate.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Apify | 52 |
| 4 | ZoomInfo | 50 |
| 5 | Clay | 89 |
| 6 | Codex | 84 |
| 7 | Outreach | 46 |
| 8 | 1mind | 37 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Grok Bot | 67 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
Enterprise AI reached 5.5% in April, then declined gradually to 3.5% by September. The L30 is nearly flat at minus 2.7%, which suggests a lower plateau rather than a fresh break; discussion has moved from production infrastructure launches toward the harder gap between available capability and captured value.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | HubSpot | 87 |
| 5 | Nooks | 48 |
| 6 |  6sense | 40 |
| 7 | ElevenLabs | 53 |
| 8 | Grok Bot | 67 |
| 9 | Lovable | 59 |
| 10 | OpenClaw | 50 |
Measuring whether AI answers mention, cite and recommend a brand.
AI visibility spiked in June, stayed elevated through August, then fell in September; the L30 is down 19.9%. Earlier studies and optimization tactics gave the category momentum, but recent scrutiny of inconsistent AI answers and missing prompt-volume data has challenged whether current tracking can support precise conclusions.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Semrush | 48 |
| 3 | Ahrefs | 49 |
| 4 | Claude Code | 99 |
| 5 | HubSpot | 87 |
| 6 | Peec AI | 28 |
| 7 | AirOps | 38 |
| 8 |  AthenaHQ | 19 |
| 9 | Docket | 30 |
| 10 |  Ranked AI | 34 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps fell steadily from 4.5% in March to about 2.7% by August, then held flat through September. The posts are about who takes over the work. Janis Zech's read from Dreamforce has marketing ops merging with GTM engineering, and Darrell Alfonso sketches ops teams built around agents. Accord pushes back on AI forecasting.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Claude Code | 99 |
| 5 | Gong | 64 |
| 6 | Attio | 51 |
| 7 | n8n | 59 |
| 8 | Lovable | 59 |
| 9 | Instantly | 62 |
| 10 | ZoomInfo | 50 |
Email sent to people with no prior relationship to start a sales conversation.
Cold Email reached a May high, fell sharply through July, and continued a slower decline afterward; L30 is down 7.7%. The May spike aligns with Jason Bay’s 15x reply-rate claim for direct inbox sends, while later posts narrowed the discussion to relevance, personalization, and value-first tactics rather than broad channel enthusiasm.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Instantly | 62 |
| 3 | Clay | 89 |
| 4 | Prospeo | 52 |
| 5 | Lemlist | 48 |
| 6 | Codex | 84 |
| 7 | HubSpot | 87 |
| 8 | Apollo.io | 52 |
| 9 |  AI Ark | 45 |
| 10 | Apify | 52 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer success has declined from March through September, apart from a brief August lift, and the L30 is down 25.9%. The conversation moved from Rox automating renewals and expansion toward organizational consolidation at Vanta and a sharp Salesforce support failure, a pattern that puts efficiency promises beside unresolved service basics.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Lovable | 59 |
| 5 | Replit | 56 |
| 6 | Claude Code | 99 |
| 7 |  Salesloft | 41 |
| 8 | ZoomInfo | 50 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Gong | 64 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Prospecting peaked at 4.18% in May, after April launches of Origami's automated lead finder and Salesforce's Prospecting Agent built on ZoomInfo data. It has slid every month since, to 2.28% in September, and is down 21% over the last 30 days. Clay's September API and CLI treat prospecting as one step a coding agent runs, alongside enrichment.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | HubSpot | 87 |
| 5 | AI Ark | 45 |
| 6 | Instantly | 62 |
| 7 | Apollo.io | 52 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Grok Bot | 67 |
| 10 | Prospeo | 52 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold outbound share started high, briefly rebounded in May, then fell steadily through September as the conversation moved from AI sequencing launches to the harder reality of getting buyers to engage. Recent posts return to cold-call fundamentals and buyer resistance, but the L30 move is still down 7.9%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | Instantly | 62 |
| 4 | HubSpot | 87 |
| 5 | Nooks | 48 |
| 6 | HeyReach | 51 |
| 7 | Prospeo | 52 |
| 8 | FullEnrich | 43 |
| 9 | Salesforce | 92 |
| 10 | Apollo.io | 52 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid Media held near 2.1% from May through July, then jumped to 2.58% in August. That month brought Clay Ads, with its claim of cutting LinkedIn cost per lead from $250 to $25, Jeff Green's Zuma release of Kokai, and Kieran Flanagan's modern B2B playbook. September fell back to the usual level, down 22% over 30 days.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Clay | 89 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 62 |
| 5 | Gong | 64 |
| 6 | HeyReach | 51 |
| 7 | Salesforce | 92 |
| 8 | Ahrefs | 49 |
| 9 | Attio | 51 |
| 10 |  Fibbler | 34 |
Voice and chat software that talks with buyers and customers.
Conversational AI climbed steadily from 1.47% share in March to 2.07% in August, then held flat in September. Share edged up 5% over the last 30 days. The September posts show voice agents going live: OpenAI put gpt-live-1 in its API, ElevenLabs paired with Genesys, and Philippine Airlines deployed a Sierra voice agent.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | ElevenLabs | 53 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 92 |
| 5 | Vector | 37 |
| 6 | Docket | 30 |
| 7 | Instantly | 62 |
| 8 | Codex | 84 |
| 9 | Vercel | 60 |
| 10 |  Bland | 19 |
The debate over AI risk, alignment, regulation and responsible development.
AI safety stayed below 1% share from March through August, then jumped to 2.019% in September; the last 30 days are up 134%. September discussion ranged from Microsoft’s humanity-first stance to workplace risk controls and Salesforce-backed frontier safeguards for enterprise use.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 67 |
| 4 | beehiiv | 49 |
| 5 | Salesforce | 92 |
| 6 | HubSpot | 87 |
| 7 | Substack | 53 |
| 8 | ElevenLabs | 53 |
| 9 | OpenClaw | 50 |
| 10 | Runway | 36 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Evals share more than doubled from 1.1% in March to a 2.9% peak in July, then settled near 2% in August and September. The last 30 days are up 9%. Recent posts are about teams running evals on their own work: Vercel's eval harness for agent pages, Mercor turning enterprise workflows into evals, and AI21's case for tuning agents against your own evals.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | Grok Bot | 67 |
| 5 | LangChain | 46 |
| 6 | Cline | 27 |
| 7 | HubSpot | 87 |
| 8 | Salesforce | 92 |
| 9 | OpenRouter | 51 |
| 10 | Devin | 38 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand generation has trended down from March, with only a brief August lift before September weakened again; the L30 move is down 20.1%. No launch drove the curve. The pattern is a broader rethink of the function as zero-click research erodes capture tactics, founders change early marketing hires, and teams question lead-quality signals.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Claude Code | 99 |
| 4 | Clay | 89 |
| 5 | Docket | 30 |
| 6 | Vector | 37 |
| 7 | Gong | 64 |
| 8 | Optimizely | 30 |
| 9 | RB2B | 47 |
| 10 | Webflow | 48 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
Share jumped from 1.26% in July to 2.05% in August, then held near 2.01% in September. Late-Aug model comparisons reflected the higher level, while September brought video generation into existing creative workflows and framed avatars around business owners’ production barriers; momentum has eased 8.6% over the last 30 days.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 38 |
| 2 | Runway | 36 |
| 3 | Replit | 56 |
| 4 | HeyGen | 32 |
| 5 | Salesforce | 92 |
| 6 | Claude Code | 99 |
| 7 | Grok Bot | 67 |
| 8 | HubSpot | 87 |
| 9 |  Synthesia | 26 |
| 10 | Cursor (Anysphere) | 77 |
Sales and marketing coordinating around a defined set of target accounts.
ABM’s share fell from a March peak to a July low, then held roughly flat through August and September; the latest L30 reading is up 4.5%. Recent conversation centers on ABM’s economics versus PLG, launches challenging legacy account-level signals, and buying-group approaches that look beyond individual leads.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Clay | 89 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 62 |
| 5 | Salesforce | 92 |
| 6 | 6sense | 40 |
| 7 | Nooks | 48 |
| 8 | FullEnrich | 43 |
| 9 | HeyReach | 51 |
| 10 | Codex | 84 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
Data infrastructure has lost about 60% of its February share, with a brief bump in June. The talk has moved from platforms to access: Pocus folding into Apollo in March, then Salesforce's Headless 360 connector for Claude and Informa TechTarget's MCP server for intent data. The last 30 days are down 8%.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Clay | 89 |
| 5 | Gong | 64 |
| 6 |  GrowthLoop | 30 |
| 7 | Attio | 51 |
| 8 | Codex | 84 |
| 9 | Nooks | 48 |
| 10 |  Twilio | 42 |
The work of connecting marketing activity to pipeline and revenue.
Attribution dropped after March, briefly recovered in May, then settled into a lower plateau from June through September. The L30 move is up 21.2%, and the elevated partial October bar is early context; the conversation spans practical fixes for zero-click journeys, correlation-based measurement, and satire about repackaged multi-touch models.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Webflow | 48 |
| 5 | Docket | 30 |
| 6 | Twilio | 42 |
| 7 | Claude Code | 99 |
| 8 |  MoEngage | 22 |
| 9 | Vector | 37 |
| 10 | 6sense | 40 |
Mapping and winning the committee of people involved in a business purchase.
Buying Groups dropped sharply after March, recovered partway in May, then settled near a lower plateau before another step down in August. September held that level and the L30 measure is up 6.6%, suggesting durable attention to committee deals rather than a breakout, supported by practical playbooks for multithreading, tailored assets, and procurement.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Claude Code | 99 |
| 5 |  Findymail | 41 |
| 6 | HeyReach | 51 |
| 7 | Instantly | 62 |
| 8 | AI Ark | 45 |
| 9 |  BuiltWith | 32 |
| 10 | Gong | 64 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Data Enrichment has more than halved since March, from 3.76% of the conversation to 1.59% in September, and is down 40% over 90 days. The March high matched Clay's pricing change, which cut marketplace data costs 50 to 90%. By September the talk was enrichment inside agent workflows and pricing fights, with Nathan Merzvinskis claiming a 92% win rate against Clay.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Instantly | 62 |
| 5 | Prospeo | 52 |
| 6 | Salesforce | 92 |
| 7 | AI Ark | 45 |
| 8 | Apollo.io | 52 |
| 9 | Codex | 84 |
| 10 | HeyReach | 51 |
The training, fine-tuning and modeling work underneath AI products.
Machine Learning's share climbed from 0.98% in June to 1.60% in September, with the biggest step in July. It is still rising, up 13% over the last 30 days. Late August and September posts show what the talk was about: models for robots and the physical world, from Skild's one-demo robot model to FLUX 3 Action and World Labs joining AMD.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | LangChain | 46 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Salesforce | 92 |
| 6 | Baseten | 46 |
| 7 | Grok Bot | 67 |
| 8 | OpenRouter | 51 |
| 9 | Vercel | 60 |
| 10 | Cline | 27 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise selling has slid from 2.4% in March to between 1.3% and 1.6% since July, and the last 30 days are flat. What remains is about moving upmarket and getting to production. Higgsfield went from $20M to $700M in run rate on enterprise demand, Clay had three $1M+ enterprise closers, and buyers keep asking whether AI survives security review.
Posts to understand this · as of Oct 3
 inBuyer realityStephanie Buscemi says enterprise buyers now ask whether AI survives production and complianceAM
 inUpmarket moveHiggsfield grew run rate from $20M to $700M by moving from consumers to enterpriseVA
 inSeller profilesThree Clay sellers each closed over $1M in enterprise deals last quarter
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Cursor (Anysphere) | 77 |
| 3 | HubSpot | 87 |
| 4 | Clay | 89 |
| 5 | Lovable | 59 |
| 6 | Attio | 51 |
| 7 | FullEnrich | 43 |
| 8 | Grok Bot | 67 |
| 9 | Replit | 56 |
| 10 | 1mind | 37 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
The April rename from INBOUND to UNBOUND created the first spike, then attention faded until the September event drove a much larger one. Partner Day drew more than 1,300 partners and the conference hosted roughly 13,000 people; the L30 move remains sharply positive, while four October days are only early context.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Claude Code | 99 |
| 5 | Gamma | 43 |
| 6 | Profound | 53 |
| 7 | Apify | 52 |
| 8 |  Breeze | 23 |
| 9 | Lightfield | 26 |
| 10 | Vector | 37 |
People asking AI assistants for answers instead of using a traditional search engine.
AI Search & AI Answers rose into June, then lost ground for three straight full months; the last 30 days are down 20.5%. The evidence points to an unsettled shift rather than fading stakes: practitioners documented lower Google clicks, persistent AI citations after de-indexing, and a move from ranking toward recommendation, yet none produced a sustained second wave; early October is partial context.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Semrush | 48 |
| 2 | Profound | 53 |
| 3 | Ahrefs | 49 |
| 4 | Gamma | 43 |
| 5 | Gong | 64 |
| 6 | HubSpot | 87 |
| 7 | Apify | 52 |
| 8 | AthenaHQ | 19 |
| 9 | Clarify | 29 |
| 10 | Clay | 89 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability peaked in May at 2.2% and has drifted back to about 1.4%, with the last 30 days down 16%. September's posts came from email vendors teaching the basics: a Customer.io AMA, and a Mailgun and Red Sift session on SPF, DKIM, DMARC and BIMI. Resend hired a deliverability engineer who most recently worked at Klaviyo.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Instantly | 62 |
| 3 | Claude Code | 99 |
| 4 | Prospeo | 52 |
| 5 | HubSpot | 87 |
| 6 | Lemlist | 48 |
| 7 | Salesforce | 92 |
| 8 | Apollo.io | 52 |
| 9 | Codex | 84 |
| 10 | Grok Bot | 67 |
Programmable tools used to build custom go-to-market systems, agents and automations.
The topic tripled from March to a May high as builders showed Claude Code wiring their GTM stacks together. Eric Nowoslawski gave away 29 Claude skills for cold email in April, and Felix Frank pitched Claude Code as the command center in May. Share has settled near 1.4%, down slightly over the last 30 days, with setups like Bill Stathopoulos's 22-tool window keeping it there.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | Prospeo | 52 |
| 2 | FullEnrich | 43 |
| 3 | Instantly | 62 |
| 4 | Clay | 89 |
| 5 | Claude Code | 99 |
| 6 | HubSpot | 87 |
| 7 | AI Ark | 45 |
| 8 | HeyReach | 51 |
| 9 | Apollo.io | 52 |
| 10 |  PredictLeads | 39 |
The choice of go-to-market motion and the plan for making it work.
GTM Strategy peaked in May, then lost share through September; the L30 move is down another 24%. No single event drove the slide. The posts instead trace a shift toward AI-owned and builder-led motions, from Swan AI’s agent workflows and Intercom’s Fin to Notion’s workflow-first account model.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | HubSpot | 87 |
| 5 | Nooks | 48 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Apollo.io | 52 |
| 8 | Attio | 51 |
| 9 | Docusign | 36 |
| 10 | Gong | 64 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
Product Marketing fell sharply from March to May, then found a lower plateau through August before slipping again in September; the L30 measure is down 25.0%. No launch explains the shape. The posts show attention moving toward marketing engineers while PMM discussion becomes more defensive and instructional, centered on launch discipline, messaging, and why the role still matters.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 53 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 87 |
| 4 | Salesforce | 92 |
| 5 | Gong | 64 |
| 6 | Lovable | 59 |
| 7 | Ahrefs | 49 |
| 8 | Apify | 52 |
| 9 | Codex | 84 |
| 10 | FullEnrich | 43 |
The durable knowledge and memory an agent can use across tasks and sessions.
Conversation share rose from March through June, then fell through September. The 17.7% L30 rebound is showing up in fresh October discussion of enterprise memory architecture and concrete implementation tradeoffs, following August interest in context layers that connect agents to live company data and conversation history.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Clay | 89 |
| 6 | Attio | 51 |
| 7 | Grok Bot | 67 |
| 8 | Profound | 53 |
| 9 | Apify | 52 |
| 10 | Codex | 84 |
How companies create demand, build trust and reach buyers at other businesses.
B2B Marketing peaked in March at 2.6% and has lost a third of its share over 90 days, down 14.1% in the last 30. No single event explains the slide. Early in the year, posts like Devin Reed's made broad calls about the shift. The ones holding up now argue about specifics: Kieran Flanagan on channels, Matt Heinz on the MQL.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Webflow | 48 |
| 4 | Claude Code | 99 |
| 5 | Optimizely | 30 |
| 6 | Gong | 64 |
| 7 |  Primer | 26 |
| 8 | Clay | 89 |
| 9 | Customer.io | 38 |
| 10 |  Demandbase | 29 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Conversation peaked in April, declined steadily through August, then leveled off in September; the last 30 days rose 4.6%. Recent discussion spans Ami’s GTM agent launch, Gong’s custom revenue workflows, and an early human-versus-agent outbound test, showing renewed activity across product launches and practical execution.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Nooks | 48 |
| 5 |  Sumble | 32 |
| 6 | HubSpot | 87 |
| 7 |  Rox | 31 |
| 8 | Attention | 30 |
| 9 | Clarify | 29 |
| 10 | Clearskies | 21 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales Leadership held near 2.3% in April and May, then declined steadily; its L30 share is down 12.7%. The conversation has narrowed around what leaders do directly: Replit wants a hands-on VP of Sales, while other posts stress spotting talent early and retaining reps long enough to build expertise.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Gong | 64 |
| 4 | Claude Code | 99 |
| 5 | Clay | 89 |
| 6 | Codex | 84 |
| 7 | MoEngage | 22 |
| 8 | Replit | 56 |
| 9 | TitanX | 32 |
| 10 | 6sense | 40 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting hit a May high, then settled into a lower range and declined another 14.6% in the L30. No single event explains the slide. The posts show forecasting absorbed into wider systems for deal execution and AI-directed revenue work, from HockeyStack’s revenue agents to Apollo’s intelligence layer and workflow builder.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Gong | 64 |
| 5 | Claude Code | 99 |
| 6 | n8n | 59 |
| 7 |  Clari | 33 |
| 8 | Nooks | 48 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Granola | 50 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence share has roughly halved since February, apart from a July bump. Call analysis now shows up inside bigger platforms: Outreach and Zoom were each named leaders in revenue orchestration reports, and Momentum is powering the data foundation for Salesforce's new Hunter sales agent. The last 30 days are down 7%.
Posts to understand this · as of Sep 30
 inForrester WaveOutreach named a leader in Forrester's Q3 2026 revenue orchestration WaveZ
 inIDC MarketScapeZoom named a leader in IDC MarketScape for unified revenue orchestration platformsAW
 inSalesforce partnerMomentum powers the data foundation for Salesforce's Hunter agent, shown at Sales Cloud keynote
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 64 |
| 2 | Salesforce | 92 |
| 3 | HubSpot | 87 |
| 4 | Claude Code | 99 |
| 5 | Clay | 89 |
| 6 | Outreach | 46 |
| 7 | Salesloft | 41 |
| 8 | Grok Bot | 67 |
| 9 | Instantly | 62 |
| 10 | Lovable | 59 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search Strategy climbed sharply into June, then gave back share across July, August, and September; the L30 move is down 22.3%. The decline sits alongside a broader challenge to old search assumptions: zero-click behavior weakens owned traffic, broad keywords miss revenue intent, and AI citation counts can reward spam that Google removes.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Ahrefs | 49 |
| 3 | Semrush | 48 |
| 4 |  Similarweb | 32 |
| 5 |  SparkToro | 27 |
| 6 | AirOps | 38 |
| 7 | LangChain | 46 |
| 8 | Apify | 52 |
| 9 |  Browser Use | 27 |
| 10 | Claude Code | 99 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing rose almost continuously from March through September, with concrete economics keeping the topic alive: Devin Fusion claimed 35% lower cost, OpenRouter joined Stripe, and Harvey’s frontier-model costs reportedly crushed gross margin. The curve has cooled 16% over the last 30 days, but it still sits 83% above the 90-day comparison, so this looks like consolidation after a sustained rise.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Cline | 27 |
| 6 | Grok Bot | 67 |
| 7 | HubSpot | 87 |
| 8 | LangChain | 46 |
| 9 | Vercel | 60 |
| 10 | Baseten | 46 |
How companies sell to other companies and how business buyers make decisions.
B2B Sales has moved in waves rather than followed one event: a May recovery gave way to a gradual third-quarter decline, with the L30 down 15.4%. The posts point to a split inside the category. Aligned raised $60 million around digital deal rooms, while sellers and LinkedIn emphasized trust, credible experts, events, and face-to-face contact.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Claude Code | 99 |
| 5 | FullEnrich | 43 |
| 6 | Hermes Agent | 37 |
| 7 | OpenClaw | 50 |
| 8 | Ploy | 24 |
| 9 | 6sense | 40 |
| 10 | Ahrefs | 49 |
Starting and running a business, including the economics and experience of the founder path.
Conversation stayed near a broad plateau through June, dropped in July, recovered partly in August and softened again in September; the latest 30 days are down 13.4%. No single event defines the curve. The strongest posts instead cluster around lean ownership models, from YouSpot’s solo-business CRM to Tally reaching $6 million ARR with ten people.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | Lovable | 59 |
| 4 | Salesforce | 92 |
| 5 | Substack | 53 |
| 6 | HubSpot | 87 |
| 7 | Instantly | 62 |
| 8 | Replit | 56 |
| 9 | 6sense | 40 |
| 10 |  Amp | 16 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing held between 1.5% and 2% through June, then September roughly halved it. The last 30 days are down 46%. No single event explains the fall. The talk that remains questions the old job: Sjeel K.'s satire of a CEO generating 40 empty AI blog posts, and Kyle Lacy arguing the question is now whose voice is missing.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Ahrefs | 49 |
| 4 | Clay | 89 |
| 5 | Grok Bot | 67 |
| 6 | HeyReach | 51 |
| 7 | Instantly | 62 |
| 8 | Profound | 53 |
| 9 | Semrush | 48 |
| 10 | Customer.io | 38 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement has trended down since March, despite a brief July lift, with August and September extending the decline and the L30 down another 12.2%. No single event explains the curve: the conversation spans a persistent coaching gap, Vanta’s measured Hyperbound results, and Mindtickle’s push toward AI and agentic enablement.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Gong | 64 |
| 4 | Cursor (Anysphere) | 77 |
| 5 |  Winn.ai | 25 |
| 6 | Ahrefs | 49 |
| 7 | Apollo.io | 52 |
| 8 | Claude Code | 99 |
| 9 | Clay | 89 |
| 10 | Customer.io | 38 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
CLIs for GTM rose into May, dipped in June, and reached a July high after Clay launched its API and CLI. August and September held a lower but still elevated plateau, while the last 30 days are down 18.5%. FullEnrich’s September access program shows the pattern broadening beyond one launch into repeatable terminal-based workflows.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Salesforce | 92 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Grok Bot | 67 |
| 7 | HubSpot | 87 |
| 8 | Clarify | 29 |
| 9 | Nooks | 48 |
| 10 | Sumble | 32 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Headless software spiked sharply in April, fell through July, then rebuilt share across August and September. No supplied post explains the April jump, but the recent 11.9% L30 rise has a clear pattern: Salesforce opened capabilities through APIs and MCP, while Lovable and internal GTM teams put those interfaces to work across existing systems.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 89 |
| 3 | HubSpot | 87 |
| 4 | Apify | 52 |
| 5 | ZoomInfo | 50 |
| 6 | Claude Code | 99 |
| 7 | Firecrawl | 40 |
| 8 | Exa.ai | 46 |
| 9 | Lightfield | 26 |
| 10 | Clarify | 29 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth Marketing fell hard from March to April, then drifted lower through August before a modest September rebound. The L30 measure is down 11.9%, so that bounce has not held. The pattern reflects a broader reframing from channel optimization toward AI-assisted product work, GTM engineering, and higher experiment volume.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Webflow | 48 |
| 2 | Optimizely | 30 |
| 3 | Ahrefs | 49 |
| 4 | HubSpot | 87 |
| 5 | AirOps | 38 |
| 6 | Profound | 53 |
| 7 | Salesforce | 92 |
| 8 | ElevenLabs | 53 |
| 9 | Gamma | 43 |
| 10 |  Gumloop | 25 |
The software stack marketers use to plan, run, measure and improve their work.
Martech held near 1.5% of the conversation from March to May, then slid below 1% in June and July. A brief August bounce faded, and the last 30 days are down 23%. Recent posts come from Doug Tallmadge on a collapsing software stack at Dreamforce, Frans Riemersma on who owns martech without a CMO, and Phil Gamache on personalization versus creativity.
Posts to understand this · as of Oct 2
 inCreativity gapPhil Gamache asks whether cheap personalization made creativity look optional in martechDT
 inStack collapseDoug Tallmadge previews his Dreamforce talk with Scott Brinker on the collapsing software stackFRinMissing CMOFrans Riemersma notes zero FTSE 100 boards have a CMO and asks who owns martech
| Brand | GTM Index | |
|---|---|---|
| 1 | GrowthLoop | 30 |
| 2 | HubSpot | 87 |
| 3 | Salesforce | 92 |
| 4 |  Augment Code | 17 |
| 5 | Twilio | 42 |
| 6 | Claude Code | 99 |
| 7 | Codex | 84 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Customer.io | 38 |
| 10 |  Hightouch | 32 |
Systems where several agents divide a job, coordinate their work and combine the result.
Multi-agent systems rose into May, then lost share almost every month through September; no single post explains that long slide. Workato’s Airo expansion and Mercor’s five-hour, 100-plus-subagent diligence run gave the category concrete enterprise proof, and the L30 move has turned up 26.1% even though the 90-day trend remains down.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 67 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | ElevenLabs | 53 |
| 6 | LangChain | 46 |
| 7 | OpenClaw | 50 |
| 8 | Salesforce | 92 |
| 9 | Vercel | 60 |
| 10 | Zapier | 53 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent Skills peaked in May, then declined across the following full months, with the L30 measure down 22.7%. Neither Vercel’s open agent plugin standard nor practical Claude skills for advertising and OKR reviews reversed that slide. The pattern suggests strong utility inside specific workflows, but less broad conversation after the May burst.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Salesforce | 92 |
| 4 | Codex | 84 |
| 5 | Clay | 89 |
| 6 | Instantly | 62 |
| 7 | Nooks | 48 |
| 8 | Optimizely | 30 |
| 9 | Apify | 52 |
| 10 | Customer.io | 38 |
How marketing teams use AI, where it helps and how it changes the job.
After falling from March to May, conversation settled into an uneven plateau through September. September posts focus on practical constraints, working AI use cases, and whether agents build automation or become the automation; the L30 move is nearly flat, down 1.2%.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Profound | 53 |
| 3 | Claude Code | 99 |
| 4 | Lovable | 59 |
| 5 | Salesforce | 92 |
| 6 | ElevenLabs | 53 |
| 7 |  Adobe Marketo | 25 |
| 8 | AirOps | 38 |
| 9 |  Aurasell | 18 |
| 10 |  Buffer | 24 |
The point where a product solves a real need for a market that will buy it.
Product-market fit talk peaked in spring, near 1.2% of the conversation in April, then fell to under half that by July. Spring posts included Elena Verna's Lovable score and Mark Roberge on fit as observable behavior. Since August it has held flat near 0.7%, and in September ClickUp said fit now refreshes every few weeks.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | Lovable | 59 |
| 4 | Granola | 50 |
| 5 | HeyReach | 51 |
| 6 | HubSpot | 87 |
| 7 | Profound | 53 |
| 8 | Salesforce | 92 |
| 9 | Ahrefs | 49 |
| 10 | Bland | 19 |
Scoring leads and accounts to decide who deserves attention first.
Lead Scoring held between 1.3% and 1.8% of the conversation from March to June, slipped to 1.2% in July, then fell to 0.7% in August. It has stayed near that lower level since, down 6% over the last 30 days. Recent posts question static scores or reuse them as ad signals.
Posts to understand this · as of Oct 2
 inBest-guess critiqueDarrell Alfonso calls lead scoring a best guess and says buyers can now tell youM
 inAd bidding signalMake promotes an October 6 masterclass on using lead scores to guide Meta biddingP
 inEvent recapPropensity shares Davis Potter's UNBOUND takeaway that AI moves ABM past static account scoring
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Claude Code | 99 |
| 5 | Codex | 84 |
| 6 | Grok Bot | 67 |
| 7 | Instantly | 62 |
| 8 | Webflow | 48 |
| 9 | 6sense | 40 |
| 10 | AI Ark | 45 |
Teams building internal software with AI instead of buying another SaaS product.
The topic fell sharply from April through June, then settled into a narrower July-to-September range. The L30 is up 22.9%, with early October showing Replit’s sales-led internal tooling example, but the broader evidence is a live buy-versus-build argument: cheaper creation meets maintenance, security, support, and opportunity-cost concerns.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Claude Code | 99 |
| 4 | Clay | 89 |
| 5 | Lovable | 59 |
| 6 | ZoomInfo | 50 |
| 7 | Clarify | 29 |
| 8 |  Momentum | 24 |
| 9 | Monaco | 25 |
| 10 |  Qualified | 25 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting rose steadily from March through June, then declined for three straight months into September. The L30 move remains slightly down at 2.5%, and the evidence points to a reframing rather than one event: weak conversion is increasingly blamed on the offer, audience, strategy, or AI brief before the words themselves.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | Instantly | 62 |
| 4 | Clay | 89 |
| 5 | AI Ark | 45 |
| 6 | HeyReach | 51 |
| 7 | Midjourney | 36 |
| 8 | Apollo.io | 52 |
| 9 | Codex | 84 |
| 10 | Grok Bot | 67 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
AI-pilled companies peaked in April at 1.37% of the conversation, when Yamini Rangan split AI adoption into individual and institutional productivity and Brian Halligan described CEOs running on recorded meetings. It has eased since, and the last 30 days are down 23.4%. The September tone is wearier: Sam Jacobs hears exhaustion from GTM leaders.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Salesforce | 92 |
| 3 | Claude Code | 99 |
| 4 | Clay | 89 |
| 5 | ElevenLabs | 53 |
| 6 | HubSpot | 87 |
| 7 | Nooks | 48 |
| 8 | beehiiv | 49 |
| 9 | 6sense | 40 |
| 10 | Attention | 30 |
B2B brands paying creators and independent voices to reach trusted audiences.
Creator partnership discussion has been choppy, rising into June, recovering in August, then dropping in September. It is down 18.6% over the last 30 days, so early October’s larger partial share is context, not a reversal. The evidence points to program maturity through Miro’s creator campaigns, Limelight’s deal volume and Salesforce hiring MrBeast.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | ElevenLabs | 53 |
| 3 | Webflow | 48 |
| 4 | Claude Code | 99 |
| 5 | Gamma | 43 |
| 6 | HeyReach | 51 |
| 7 | HubSpot | 87 |
| 8 | Lovable | 59 |
| 9 | Replit | 56 |
| 10 | beehiiv | 49 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing Automation lost more than half its share from February to June. It turned in July, when HubSpot launched Agent Hub and Agent Builder, and the recovery has held, up 11.3% over 90 days and 8% in the last 30. In September, Jon Miller, holding his 2006 Marketo shirt, argued the category never moved on and marketers want AI-native tools.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | GrowthLoop | 30 |
| 4 | Twilio | 42 |
| 5 |  ActiveCampaign | 31 |
| 6 | Adobe Marketo | 25 |
| 7 | Attio | 51 |
| 8 |  Conversion | 25 |
| 9 |  Gainsight | 27 |
| 10 | AirOps | 38 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Partner Marketing & Ecosystem stepped up in August and held nearly flat in September, after Snowflake highlighted 200%+ growth with Dataiku and operators pushed always-on partner demand generation. Lovable’s September partner program gave the plateau a concrete launch, but momentum has softened 21.1% over the last 30 days; October’s lower bar covers only seven days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Lovable | 59 |
| 5 | Replit | 56 |
| 6 | Gong | 64 |
| 7 | Instantly | 62 |
| 8 | AI Ark | 45 |
| 9 | Apollo.io | 52 |
| 10 | Aurasell | 18 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
Conversation peaked in May as April coverage grouped several vendors shifting from seats toward usage, tokens and outcomes, followed by monday.com’s credit launch. Navan’s usage-led growth kept the theme active in June, but share stepped down from July through September and the latest 30 days are down another 14.2%.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Replit | 56 |
| 4 | Lovable | 59 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Vercel | 60 |
| 7 | Clay | 89 |
| 8 |  Metronome | 26 |
| 9 | Nooks | 48 |
| 10 | Runway | 36 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Conversation share eased from 1.23% in March to 0.90% in July, briefly lifted in August, then fell sharply in September; the L30 move is down 31.1%, so direction remains lower. The discussion that remains centers on giving every post a pipeline job, building buyer trust over time, and owning a recognizable idea.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 89 |
| 3 | Lovable | 59 |
| 4 | RB2B | 47 |
| 5 | Grok Bot | 67 |
| 6 | HubSpot | 87 |
| 7 | Vector | 37 |
| 8 | Ahrefs | 49 |
| 9 | HeyReach | 51 |
| 10 | Instantly | 62 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing ops has lost share in every month but one since March, falling by more than two thirds. The posts that still travel describe the job changing shape: Holly Chen's team running 40 to 50 agents, Scott Brinker on GTM engineers and AI-native operators, and Clay's GTME list. The 30-day move is still down 28%.
Posts to understand this · as of Oct 1
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Docket | 30 |
| 4 | GrowthLoop | 30 |
| 5 | MoEngage | 22 |
| 6 | Augment Code | 17 |
| 7 | Salesloft | 41 |
| 8 | Twilio | 42 |
| 9 |  allGood | 17 |
| 10 | Adobe Marketo | 25 |
AI agents that discover, compare and buy products on a person's behalf.
The topic peaked in March and has moved in a band since. September's lift came from commerce plumbing: Shopify partnering with Meta's Muse for agentic checkout with Shop Pay, Tobias Lütke on agentic shopping at Vercel's Ship SF, and Klaviyo landing inside Muse. The last 30 days are up 40.9%.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 |  Browserbase | 33 |
| 2 | Cursor (Anysphere) | 77 |
| 3 | Exa.ai | 46 |
| 4 | Vercel | 60 |
| 5 | HubSpot | 87 |
| 6 | Lovable | 59 |
| 7 |  Bolt.new (StackBlitz) | 23 |
| 8 | Clarify | 29 |
| 9 | ElevenLabs | 53 |
| 10 | Gamma | 43 |
AI agents that create, launch, buy and optimize advertising.
AI-Driven Advertising rose from May through August, eased slightly in September, and is up 20.2% over L30. Concrete market activity supports the broader rise: StackAdapt opened early ChatGPT ad access, OpenAI reported a $1 billion annualized run rate, and Time tested sponsored material served specifically to AI crawlers.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | Granola | 50 |
| 5 | Grok Bot | 67 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Firecrawl | 40 |
| 9 | Gong | 64 |
| 10 | Hermes Agent | 37 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales Ops rose into May, then declined across June and July, briefly steadied in August, and fell again in September. L30 share is down 31.5%; recent discussion concentrates on incentive design, especially whether rep and SDR compensation rewards revenue rather than meetings, without a single event behind the decline.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | ElevenLabs | 53 |
| 4 | HubSpot | 87 |
| 5 | Clay | 89 |
| 6 | Monaco | 25 |
| 7 | Vercel | 60 |
| 8 | n8n | 59 |
| 9 | Clari | 33 |
| 10 | Cline | 27 |
Multi-step work planned and executed by agents instead of fixed automation rules.
Agentic Workflows rose in May, faded through August, then rebounded in September as the conversation shifted from theory to operating patterns. Interviews with 50-plus RevOps leaders documented shared Claude setups, while Relevance AI launched Invent 2.0 for business-built agents; together they fit the renewed momentum, with L30 up 50.1% despite L90 remaining down 12.8%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 67 |
| 2 | HubSpot | 87 |
| 3 | Salesforce | 92 |
| 4 | Codex | 84 |
| 5 | Apollo.io | 52 |
| 6 | Claude Code | 99 |
| 7 | Gong | 64 |
| 8 | 1mind | 37 |
| 9 | Clay | 89 |
| 10 |  Grammarly | 29 |
The work of earning awareness, trust and preference for a company over time.
Brand Building held near 1% from March through June, dipped in July, briefly recovered in August, then dropped sharply in September. No single event explains the 47.3% L30 decline. The posts show a narrower, defensive conversation about proving long-term value, from B2B budget skepticism to Ramp keeping brand, events, direct mail, and stunts despite weak attribution credit.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Ahrefs | 49 |
| 3 | HubSpot | 87 |
| 4 | Nooks | 48 |
| 5 | Semrush | 48 |
| 6 | 6sense | 40 |
| 7 |  Braze | 25 |
| 8 | Buffer | 24 |
| 9 | Claude Code | 99 |
| 10 |  Composio | 29 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Forward Deployed Engineering climbed into a May high, then eased through August before a sharper September drop; the L30 measure is down 41.3%. The posts suggest no single trigger: Cursor hiring commentary sustained the role’s cachet in August and Palantir kept defining it in September, while an earlier product critique argued that products needing FDEs are too hard for customers to maintain.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Braze | 25 |
| 3 | Claude Code | 99 |
| 4 | Codex | 84 |
| 5 | Nooks | 48 |
| 6 | Clay | 89 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Devin | 38 |
| 9 | ElevenLabs | 53 |
| 10 | Gong | 64 |
A go-to-market operating model where agents execute work across the revenue motion.
The August rise came with two concrete threads: marketers were moving beyond one-off AI assistance, while teams were already confronting agent sprawl and operating-model gaps. September stayed elevated as Clay tied a major funding announcement to GTM agents and self-learning revenue engines, but the conversation has cooled since, with share down 31% over the last 30 days.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cursor (Anysphere) | 77 |
| 3 | Salesforce | 92 |
| 4 | Clay | 89 |
| 5 | Codex | 84 |
| 6 | Grok Bot | 67 |
| 7 | HubSpot | 87 |
| 8 | n8n | 59 |
| 9 | 1mind | 37 |
| 10 | 6sense | 40 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
Conversation has stayed in a narrow, choppy band rather than breaking out, with the 90-day measure down 17.6% but the L30 move up 10.1%. Viktor’s $20 million annualized run rate and Teams expansion supplied commercial proof, while September’s open-source company brain gave the employee framing a fresh, deployable example.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Viktor | 32 |
| 2 | Clay | 89 |
| 3 | HubSpot | 87 |
| 4 | Attio | 51 |
| 5 | Ahrefs | 49 |
| 6 | Granola | 50 |
| 7 | Salesforce | 92 |
| 8 | Firecrawl | 40 |
| 9 | FullEnrich | 43 |
| 10 | Gong | 64 |
Deciding what to build, why it matters and which product bets come first.
Product strategy is a steady background topic, swinging between 0.38% and 0.66% in spring and holding near 0.45% since July. The 30-day move is up 14%, and the recent posts are about specific bets: Genesys moving from interactions to resolution workflows, Mycroft repositioning as a CMMC certification service, and ClickHouse's CEO on agents becoming customers.
Posts to understand this · as of Oct 2
 inRepositioningMycroft drew $200K+ pipeline in a week after repositioning as a CMMC certification serviceC
 inAgents as customersClickHouse CEO Aaron Katz tells 20VC how AI is reshaping product roadmapsND
 inFifth actNicolas de Kouchkovsky on Genesys moving from customer interactions into resolution workflows
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Codex | 84 |
| 5 | Exa.ai | 46 |
| 6 | Claude Code | 99 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Devin | 38 |
| 9 | Grok Bot | 67 |
| 10 | Hermes Agent | 37 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Sales development has lost share almost every month since February and fell another 28% over the last 30 days. People still talk about the role, but now as one part of a larger system. Jacco van der Kooij folds the SDR into one outcome seller, and XBOW moved its BDRs under RevOps as agent managers. Kyle Poyar's May data complicated the obituary: AI natives doubled SDR headcount.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 89 |
| 3 | Gong | 64 |
| 4 | HubSpot | 87 |
| 5 | Nooks | 48 |
| 6 | Outreach | 46 |
| 7 | Salesforce | 92 |
| 8 | FullEnrich | 43 |
| 9 |  Unify | 32 |
| 10 | Apollo.io | 52 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
In-person events have followed a choppy, campaign-led curve: a March high, an April drop, a May recovery, and a steadier July-August stretch before September weakened. The L30 is down 23.8%, though the L90 remains positive. The evidence shows targeted utility, from direct event invitations to Profound’s meetups and hackathons, rather than a broad sustained surge.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Substack | 53 |
| 2 | Lovable | 59 |
| 3 | Salesforce | 92 |
| 4 | Apify | 52 |
| 5 | Clay | 89 |
| 6 | Customer.io | 38 |
| 7 | RB2B | 47 |
| 8 | AI Ark | 45 |
| 9 | Ahrefs | 49 |
| 10 | AirOps | 38 |
Tracing and monitoring what a model or agent did during a production run.
Observability held a narrow band for months, then edged higher in August and September as the conversation moved from standalone tracing toward enterprise control and stack consolidation. Intercom’s Fin launch established the product case, while CrewAI’s bank story made vendor sprawl tangible; the last 30 days are up 14.1%, despite softer early October context.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Cursor (Anysphere) | 77 |
| 4 | HubSpot | 87 |
| 5 | OpenClaw | 50 |
| 6 | Clay | 89 |
| 7 | Grok Bot | 67 |
| 8 |  Kiro | 23 |
| 9 | LangChain | 46 |
| 10 | Salesforce | 92 |
A shared revenue knowledge layer that people and agents can query and update.
GTM Brain jumped in June and has held a much higher band since, with L90 share up 39.3% and L30 nearly flat at plus 1.3%. The plateau matters because the idea has moved from concept to operating architecture: Swan AI connects 120-plus agents to one brain, while teams describe unified systems readable by agents.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Apify | 52 |
| 4 | Grok Bot | 67 |
| 5 | Salesforce | 92 |
| 6 | Clay | 89 |
| 7 | Cursor (Anysphere) | 77 |
| 8 |  Octave | 31 |
| 9 | ZoomInfo | 50 |
| 10 | HubSpot | 87 |
Approval and review steps that keep a person involved in an agent's work.
Human in the Loop has been volatile: a May high gave way to a June-July drop, August rebounded, and September fell again. The August posts made review more specific through campaign judgment and an expertise-versus-time framework, but that lift did not hold; the current L30 move is down 28.7%.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Instantly | 62 |
| 3 | Salesforce | 92 |
| 4 | n8n | 59 |
| 5 | AI Ark | 45 |
| 6 | Apollo.io | 52 |
| 7 | Attio | 51 |
| 8 | Codex | 84 |
| 9 | Cursor (Anysphere) | 77 |
| 10 |  Fireflies | 35 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium conversation fell from a May peak to a July low, then rebounded through August and September; L30 is up 26.5%. Recent posts cover ad revenue helping expand free access, valuable free plans that serve most users, and generous usage allowances that attract sign-ups.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Lovable | 59 |
| 2 | Canva | 49 |
| 3 | Replit | 56 |
| 4 | Salesforce | 92 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | HubSpot | 87 |
| 7 | Salesloft | 41 |
| 8 | Clay | 89 |
| 9 | Codex | 84 |
| 10 | Granola | 50 |
The runtime around an agent that provides tools, state, controls and stopping rules.
Agent harnesses have moved in waves rather than climbed steadily, with alternating rises and pullbacks through September. August’s lift came with concrete releases from DeepSeek and Perplexity, while the L30 measure is up 36.9%, a rebound that the five observed October days are too early to confirm as a calendar trend.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | Cline | 27 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Grok Bot | 67 |
| 7 | LangChain | 46 |
| 8 | AI Ark | 45 |
| 9 | Ahrefs | 49 |
| 10 |  AiSDR | 21 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-Serve fell hard from March through May, stabilized at a lower level through August, and weakened again in September; the L30 move is down 11.3%. The posts show a split market: Airtable is framed as a warning about abandoning PLG, while Metronome reports a surge after opening self-serve and 1up describes AI-led buyer control.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Replit | 56 |
| 4 | Clay | 89 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Apollo.io | 52 |
| 7 |  Klaviyo | 40 |
| 8 | Lovable | 59 |
| 9 | OpenRouter | 51 |
| 10 |  PandaDoc | 33 |
Websites and docs structured so AI crawlers and agents can read and use them.
Conversation climbed into April as builders documented concrete agent-readiness fixes, then stayed elevated in May and June while practitioners disputed Google’s standard SEO advice. It declined from July through September, even as August discussion broadened toward agent-facing web experiences; the last 30 days are down 12.6%, so October’s partial reading does not establish a reversal.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Peec AI | 28 |
| 2 | Ahrefs | 49 |
| 3 | Semrush | 48 |
| 4 | Codex | 84 |
| 5 | Gamma | 43 |
| 6 | HubSpot | 87 |
| 7 | Profound | 53 |
| 8 | Webflow | 48 |
| 9 | AirOps | 38 |
| 10 | AthenaHQ | 19 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
Stack consolidation peaked in May at 0.93% of the conversation, when Gong credited its 55%-plus growth partly to customers consolidating point solutions onto Gong. It fell to 0.31% by August. The last 30 days are up 10.7%, with Unify reporting rip-and-replaces of 50-seat-plus Outreach deployments and Apollo pitching a complete AI GTM system at ApolloNext.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Attio | 51 |
| 5 | Claude Code | 99 |
| 6 | Common Room | 39 |
| 7 | Clarify | 29 |
| 8 | Codex | 84 |
| 9 | Nooks | 48 |
| 10 |  Trigify | 36 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Content at scale peaked in May and has drifted down each month since. The money still points up: Higgsfield raised $400 million at a $5.4 billion valuation on $700 million in annualized revenue. But the talk is turning skeptical, and Eli Schwartz read John Mueller's comments as a slow-to-fix penalty for AI spam.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 49 |
| 2 | Apify | 52 |
| 3 | HubSpot | 87 |
| 4 | AirOps | 38 |
| 5 | Claude Code | 99 |
| 6 | Crunchbase | 34 |
| 7 | Grok Bot | 67 |
| 8 | Lovable | 59 |
| 9 |  OtterlyAI | 22 |
| 10 | Peec AI | 28 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales Tech share rebounded in June, then fell through September; the current L30 is down 31.8%. The posts show a broad outbound tool market in June, a September push to consolidate bloated stacks, and an earlier warning that incomplete CRM data undermines sales AI, without claiming any one theme caused the curve.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Gong | 64 |
| 3 | Nooks | 48 |
| 4 | Outreach | 46 |
| 5 | Claude Code | 99 |
| 6 | Attention | 30 |
| 7 | Clarify | 29 |
| 8 | Clay | 89 |
| 9 | Common Room | 39 |
| 10 | HubSpot | 87 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound systems climbed from March to a May peak, then lost share every month after. The last 30 days are down 58%. Recent posts focus on basics and fewer tools: John Barrows found a domain broken for three years using Apollo, Rox profiled XBOW's consolidated stack, and Raouf Lemouchi shared a deliberately manual process.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | TitanX | 32 |
| 4 | AI Ark | 45 |
| 5 | AirOps | 38 |
| 6 | Apify | 52 |
| 7 | Attio | 51 |
| 8 |  Calendly | 39 |
| 9 | Codex | 84 |
| 10 | ElevenLabs | 53 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI Security held near 0.6% from March through August, then dropped sharply in September; the L30 measure is down another 27%. No single event explains the retreat: the evidence spans vulnerability research from Wiz, independent certification from Cursor, and Cohere’s sovereign AI risk study rather than one sustained news cycle.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Midjourney | 36 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 67 |
| 5 | Codex | 84 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | ElevenLabs | 53 |
| 8 | Salesforce | 92 |
| 9 | Clarify | 29 |
| 10 |  E2B | 22 |
Writing and structuring the instructions a model follows.
Prompt Engineering has faded since March. September was its quietest month, and the last 30 days are down 46%. The posts that remain argue against the skill. Liam Dunne says his problem was context, not prompts. Laurens Nys says rollouts must work with bad prompts. Semrush ships a prompt library so marketers can skip writing them.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 92 |
| 3 | Clay | 89 |
| 4 | HubSpot | 87 |
| 5 | Attio | 51 |
| 6 | Codex | 84 |
| 7 | Breeze | 23 |
| 8 | Cursor (Anysphere) | 77 |
| 9 | Granola | 50 |
| 10 | OpenClaw | 50 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
Conversation climbed into a May peak as teams moved from mapping AI-first stacks to showing practical workflow-led GTM models. It dropped sharply in June, rebounded in July, then eased through August and September; the latest 30 days are down 13.9%, even as Zendesk’s dedicated GTM AI role shows active organizational commitment.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Salesforce | 92 |
| 3 | Vector | 37 |
| 4 | FullEnrich | 43 |
| 5 | Grok Bot | 67 |
| 6 | RB2B | 47 |
| 7 | Substack | 53 |
| 8 | 1mind | 37 |
| 9 | 6sense | 40 |
| 10 |  Aligned | 25 |
Advantages that grow stronger as more people, data or participants join a product.
Network effects have lost share every full month since March, from 1.06% to 0.37% in September, about two thirds lower. The last 30 days are down 26%. What moat talk remains has shifted to data and agents: headless SaaS, agent-ready data, and customer history as context.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Clay | 89 |
| 5 | Devin | 38 |
| 6 | Grok Bot | 67 |
| 7 |  Guru | 22 |
| 8 | Vercel | 60 |
| 9 |  ZoomInfo Chorus AI | 16 |
| 10 | Ahrefs | 49 |
Using AI to tailor outreach and marketing to each person at scale.
AI personalization has drifted down since February and dropped 35% over the last 30 days. The posts that land are skeptical. An AI cold email that gets the reader's business wrong does more harm than a generic one, and a spotted fact is not a reason to reply. Kyle Asay used AI to cut 1,000 accounts to 50 instead of blasting all of them.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Clay | 89 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | ElevenLabs | 53 |
| 7 | Klaviyo | 40 |
| 8 | Lightfield | 26 |
| 9 | Outreach | 46 |
| 10 | AI Ark | 45 |
Founders running early sales themselves before handing the motion to a sales team.
Founder-led sales is small and jumpy. It climbed from a May low to a July high, when Pete Kazanjy opened free copies of Founding Sales to all founders and Scott Leese told of a $200k hire who closed zero deals. It has eased since, though September added a new argument: AI handles sales admin, so founders can sell longer.
Posts to understand this · as of Oct 1
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | HubSpot | 87 |
| 3 | 6sense | 40 |
| 4 | Attio | 51 |
| 5 | Clarify | 29 |
| 6 | Common Room | 39 |
| 7 | Gong | 64 |
| 8 | Granola | 50 |
| 9 |  HockeyStack | 29 |
| 10 | Instantly | 62 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise Marketing built from May through August, supported by practical AI workflow and governance conversations rather than a single breakout event. Canva and LinkedIn framed connected campaign execution, while enterprise leaders stressed production readiness, security, compliance, and centralized enablement; September gave back part of the rise, and the last 30 days are down 4.5%.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 89 |
| 3 | HubSpot | 87 |
| 4 | Aurasell | 18 |
| 5 | Claude Code | 99 |
| 6 | Codex | 84 |
| 7 | Cursor (Anysphere) | 77 |
| 8 | Grok Bot | 67 |
| 9 | Hightouch | 32 |
| 10 | Lightfield | 26 |
Time-limited access that lets a buyer test a product before paying.
Free Trial was at its highest in February, at 0.79%, when Kyle Poyar's funnel benchmarks compared freemium, free trial and card-required trials. It fell to 0.2% by April and has stayed near that level since, showing up mostly as a side angle: Stripe on trial abuse, Josh Braun on early upsells. The 21.6% L30 rise starts from a tiny base.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Ahrefs | 49 |
| 4 | Attio | 51 |
| 5 | Clay | 89 |
| 6 | Gong | 64 |
| 7 | Lovable | 59 |
| 8 | AthenaHQ | 19 |
| 9 | Calendly | 39 |
| 10 | Clari | 33 |
Rule-based software that moves business work through predefined steps and systems.
After peaking in April, workflow automation’s share fell through September, apart from a small July bump; the last 30 days are down 45.6%. Recent discussion centers on automating GTM busywork, letting nontechnical teams build workflows, and turning schedules and files into briefs people can review.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Claude Code | 99 |
| 3 | n8n | 59 |
| 4 | Lemlist | 48 |
| 5 | Sumble | 32 |
| 6 | Zapier | 53 |
| 7 | AI Ark | 45 |
| 8 | Ahrefs | 49 |
| 9 | AirOps | 38 |
| 10 | Airtable | 48 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
The topic spiked in April, then declined steadily through September as the broad sameness critique lost momentum. The L30 move is now up 45.4%, supported by sharper evidence: major consultancies use similar AI playbooks, and a 445-homepage study found 57% average messaging overlap.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 87 |
| 2 | Claude Code | 99 |
| 3 | Codex | 84 |
| 4 | Customer.io | 38 |
| 5 | Grammarly | 29 |
| 6 | Optimizely | 30 |
| 7 | Substack | 53 |
| 8 | Vector | 37 |
| 9 | Webflow | 48 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
Lifecycle Marketing climbed from March to a May high, then fell through August before a small September recovery. Recent direction is stronger, with L30 up 75.9%, but the pattern has no single trigger: Supademo made onboarding a growth system, while an earlier AthenaHQ case argued AI search compounds after lifecycle programs hit diminishing returns.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 87 |
| 3 | beehiiv | 49 |
| 4 | Apollo.io | 52 |
| 5 | Customer.io | 38 |
| 6 |  Explorium | 31 |
| 7 | Grok Bot | 67 |
| 8 | GrowthLoop | 30 |
| 9 | Instantly | 62 |
| 10 | MoEngage | 22 |
How AI changes headcount, entry-level work and the jobs people still need to do.
This conversation peaked in March, when Microsoft AI said white-collar tasks would be replaced and marketers felt the FOMO. A smaller rise followed in May. Since then it has cooled, down 28% over the last 30 days. The tone has moved from replacement to partnership. Kai Brandt calls sales the safest job, and leaders from Clay, Lovable and HubSpot talk about AI and humans working together.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | Grok Bot | 67 |
| 3 | Lovable | 59 |
| 4 | Attention | 30 |
| 5 | Clarify | 29 |
| 6 | Claude Code | 99 |
| 7 | Clearskies | 21 |
| 8 | Nooks | 48 |
| 9 | Rox | 31 |
| 10 | Sumble | 32 |
How sales teams use AI and how it changes the work of selling.
AI in Sales rebounded in May, held roughly level in June and July, then fell sharply through August and September. The L30 measure is down 35.9%, and the evidence points to a narrative reset: launches continue, but the conversation now stresses weak fundamentals, prior AI SDR underperformance, and stronger technical skills for sellers.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Clarify | 29 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 92 |
| 4 | Attention | 30 |
| 5 |  CallRail | 22 |
| 6 | Clay | 89 |
| 7 | Clearskies | 21 |
| 8 | Cursor (Anysphere) | 77 |
| 9 |  GitHub Copilot | 36 |
| 10 | Gong | 64 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
Share rose unevenly from March, reaching a June-August plateau, then dropped sharply in September. The L30 move is down 71.4%, even as September launches showed both sides of the connector market: Zapier supplied broad app access, while OpusClip and Tally added focused video and form workflows.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Cursor (Anysphere) | 77 |
| 3 | HeyGen | 32 |
| 4 |  Lambda | 24 |
| 5 | Lovable | 59 |
| 6 | Salesforce | 92 |
| 7 | Zapier | 53 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
The August spike came directly from new transparency rules and implementation announcements tied to the EU AI Act and California’s AI Transparency Act. Anthropic’s watermarking FAQ and Synthesia’s automatic C2PA credentials concentrated attention in that month; September then dropped sharply, and the L30 measure is down 84.7%, despite a higher early October bar.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Codex | 84 |
| 2 | Claude Code | 99 |
| 3 | HeyGen | 32 |
| 4 | Granola | 50 |
| 5 | Grok Bot | 67 |
| 6 | Runway | 36 |
| 7 | Vercel | 60 |
| 8 | Docket | 30 |
| 9 | ElevenLabs | 53 |
| 10 |  Ghost | 18 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
Outcome-based pricing rose into April and May, then declined through August before a modest September recovery. The L30 move is positive, but the L90 view remains deeply negative: HubSpot supplied a concrete pay-per-result model, while ZoomInfo’s caution shows why GTM outcomes remain hard to price and forecast.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Clay | 89 |
| 4 | Cursor (Anysphere) | 77 |
| 5 | Intercom | 44 |
| 6 | Lovable | 59 |
| 7 | 1mind | 37 |
| 8 | 6sense | 40 |
| 9 | Aligned | 25 |
| 10 | Attio | 51 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory peaked in April, dropped sharply into July, and has stayed near that lower floor; the L30 move is only up 1.8%, not a clear recovery. April’s concentration came from a specific debate over long-term fractional CMOs, while September’s fractional CRO case reinforced the model without restoring the earlier conversation level.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Substack | 53 |
AI-native firms that sell finished work instead of software, delivered by agents and a small human team.
Services-as-Software held steady from April through June, then lost nearly half its share across July and August. September’s small recovery has settled into a flat L30 reading, not renewed momentum. Daydream’s $15 million round and Sequoia’s services thesis kept the model visible, but neither recreated the strong March conversation around AI-native service economics.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Crunchbase | 34 |
The strategy of naming, defining and leading a new market.
Category creation held a steady share through spring, then fell 60% over the last 30 days. In August, Profound and Influencer still launched a new category, creator-first AEO. Then the pushback arrived. Nick Velkovski reached $17M ARR without inventing a category, and Joe Chernov argued that foundation models replaced the experts who used to crown categories.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | HubSpot | 87 |
| 3 | Nooks | 48 |
| 4 | Adobe Marketo | 25 |
| 5 | Braze | 25 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | Customer.io | 38 |
| 8 |  DemandScience | 26 |
| 9 | Devin | 38 |
| 10 | Docusign | 36 |
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
July's jump coincided with companies adopting open-source models alongside closed ones. Attention eased through August and September, and the L30 is down 38.8%, even as September posts shifted toward open source as a commoditization threat and a practical route to cheaper, higher-volume product usage.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Salesforce | 92 |
| 3 | Baseten | 46 |
| 4 | Canva | 49 |
| 5 | Claude Code | 99 |
| 6 | Codex | 84 |
| 7 | Conductor | 26 |
| 8 | Crunchbase | 34 |
| 9 | Docusign | 36 |
| 10 | Grok Bot | 67 |
Pushback against AI from customers, workers and the public, and brands repositioning as pro-human.
The curve is choppy, with a May spike around direct attacks on the backlash and an August rebound as critics highlighted an AI sales company’s return to human labor. September remained active as anti-AI graffiti surfaced in San Francisco, but the conversation has fallen 37.6% over the last 30 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 77 |
| 2 | Grok Bot | 67 |
| 3 | Bland | 19 |
| 4 | Browserbase | 33 |
| 5 | ElevenLabs | 53 |
| 6 |  Frontier | 24 |
| 7 | Granola | 50 |
| 8 | Gumloop | 25 |
| 9 | HubSpot | 87 |
| 10 | Lovable | 59 |
AI-generated creators, avatars and user-style content used in marketing.
Synthetic UGC jumped sevenfold in April, the month HeyGen added Seedance 2.0 to its avatar and video agent workflows, then settled to a low base through summer. September's 60% 30-day rise is HeyGen again: a survey of 1,000+ small business owners who filmed videos and never posted them, plus Alina Vandenberghe testing a HeyGen avatar called ai-lina.
Posts to understand this · as of Oct 1
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
Autonomous Business discussion declined from March to an August low, rebounded in September, and is down 14.8% over the last 30 days. The September lift came with concrete efficiency claims from RB2B and Swan AI, but it did not restore earlier attention. The recurring hook is revenue per employee, anchored by Polsia’s one-employee operation.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 67 |
| 3 | Lovable | 59 |
| 4 | Vercel | 60 |
| 5 | Codex | 84 |
| 6 | Cursor (Anysphere) | 77 |
| 7 | ElevenLabs | 53 |
| 8 | Gamma | 43 |
| 9 |  Netlify | 26 |
| 10 | OpenRouter | 51 |
Interfaces that let agents understand and operate software built for human users.
A small, choppy topic. It jumped in May, nearly vanished in June, then came back in July and August as vendors shipped things agents can call; the July moves recap counted Clay, Apollo, HubSpot, ZoomInfo and others. Martin Kihn previewed Salesforce's Agentforce Experience Layer ahead of Dreamforce. September eased, and the last 30 days are down.
Posts to understand this · as of Oct 2
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Clay | 89 |
| 3 | HubSpot | 87 |
| 4 | Peec AI | 28 |
| 5 | Twilio | 42 |
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent Loops surged in June, stayed near that high in July, then declined through September; L30 is down 37.4%. Joe Rhew’s June prediction helped define the concept, while Palantir’s Agent Engine and SDK gave July a concrete launch; Atlassian’s September focus on governed loops shows the idea persisting in a narrower form.
Posts to understand this · as of Oct 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 89 |
| 3 | HubSpot | 87 |
| 4 | Attio | 51 |
| 5 | Codex | 84 |
| 6 | Cursor (Anysphere) | 77 |
| 7 |  Deepline | 28 |
| 8 | LangChain | 46 |
| 9 | OpenClaw | 50 |
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing climbed through July, then lost ground in August and September; the L30 move remains down 51.6% despite a higher partial October bar. The decline reflects a clear language shift, not one isolated event: HubSpot, Databricks, and Sierra all redirected the conversation from token volume toward value, efficiency, and outcomes.
Posts to understand this · as of Oct 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 92 |
| 2 | Claude Code | 99 |
| 3 | Clay | 89 |
| 4 | Codex | 84 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | HubSpot | 87 |
| 7 | Midjourney | 36 |
| 8 | Profound | 53 |
| 9 |  Retool | 28 |
| 10 |  Writer | 29 |
The argument over requiring a form before someone can access useful content.
Conversation rebounded in May, then declined steadily through August and settled into a low September plateau. The L30 move is up 18.2%, but the 90-day view remains sharply down; recent discussion revives the debate through firm anti-gating positions, while earlier posts split between removing forms entirely and gating only useful implementation assets.
Posts to understand this · as of Oct 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Ploy | 24 |
| 2 | Salesforce | 92 |
Brands use human authorship and craft as a reason to trust or value their work.
A small, choppy topic. May's spike lines up with Dave Gerhardt arguing that human-made work will gain value. From July it held a higher floor, as Amos Bar-Joseph launched 200+ human-crafted GTM skills and agencies sold human-written content against AI slop. The L30 is off 14.6%, but the 90-day view is up 52.5%.
Posts to understand this · as of Oct 1
| Brand | GTM Index | |
|---|---|---|
| 1 | Attention | 30 |
| 2 | Clarify | 29 |
| 3 | Clay | 89 |
| 4 | Clearskies | 21 |
| 5 | Nooks | 48 |
| 6 | Rox | 31 |
| 7 | Sumble | 32 |
| 8 | Claude Code | 99 |
| 9 | Cursor (Anysphere) | 77 |
| 10 | Grok Bot | 67 |
The online channel mix used to reach, convert and retain customers.
Digital Marketing's share climbed from March to a June high, then slid through September back below where it started. In June, Tom Wentworth framed AI as the latest in a long line of marketing tech shifts. By late August and September, Rand Fishkin and Salsify were describing how zero-click search and AI recommendations change the work, while share kept falling over the last 30 days.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | AI Ark | 45 |
| 2 | Apollo.io | 52 |
| 3 |  Chili Piper | 34 |
| 4 | Clay | 89 |
| 5 |  Default | 28 |
| 6 |  Freckle.io | 34 |
| 7 |  HG Insights | 25 |
| 8 | HeyReach | 51 |
| 9 | HubSpot | 87 |
| 10 | Instantly | 62 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
Trust-based marketing is a thin, noisy topic that has bounced between 0.03% and 0.10% all year, and it is down 11% over 30 days. No single event moves it. The steady thread is proof over volume: G2 publishing its review removals, Tyrona Heath on coherence beating content volume, and Unbounce on where buyer trust breaks.
Posts to understand this · as of Oct 3
Software designed for agents to operate as the primary user.
This topic barely existed before June, then grew to an August high as Netlify argued agent experience had moved from novelty to practice. September eased, and the L30 is down 23.8%, but launches kept coming: Ploy added WebMCP so agents can use site forms, and Lorikeet shipped agent traffic detection for support teams. The share is still small.
Posts to understand this · as of Oct 1
| Brand | GTM Index | |
|---|---|---|
| 1 | Vercel | 60 |
| 2 | Ahrefs | 49 |
| 3 | Breeze | 23 |
| 4 | Clay | 89 |
| 5 | Cursor (Anysphere) | 77 |
| 6 | Gamma | 43 |
| 7 | Grok Bot | 67 |
| 8 | HubSpot | 87 |
| 9 | Intercom | 44 |
| 10 | Lovable | 59 |
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
AI detection talk was small through spring, then jumped in July and held in August. In July, Santiago Faus cited a Pangram Labs study calling 40% of LinkedIn posts AI slop; by Aug. 1, Anthony Pierri was defending a new slop-reporting feature, and on Aug. 11 Christopher Penn explained how text watermarking works. It fell back in September and is down 82.5% over the last 30 days.
Posts to understand this · as of Oct 3
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 84 |
| 3 | Grok Bot | 67 |
| 4 | Replit | 56 |
| 5 | Substack | 53 |
Using product activity to identify, time and support sales opportunities.
Product-Led Sales is a small topic, never above 0.09% of the conversation, so small moves look large. Share slid from 0.086% in February to zero by April, the stretch Brendan Short's March post describes as the end of the PLG CRM category, then returned in brief spikes. The last 30 days are up 57% to 0.033%, measured against a quiet August.
Posts to understand this · as of Sep 30
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 89 |
| 2 | HubSpot | 87 |
| 3 | Attention | 30 |
| 4 | Clarify | 29 |
| 5 | Claude Code | 99 |
| 6 | Clearskies | 21 |
| 7 | Codex | 84 |
| 8 | Hightouch | 32 |
| 9 | Intercom | 44 |
| 10 |  Mixmax | 18 |
How model costs, services and agent work put pressure on software gross margins.
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Claude Code peaked at 11.5% of the conversation in March and has slid every month since, to 5.6% in August. The last 30 days are down another 21%. The posts show the shift: people compare it as one harness among Codex, OpenCode and others, gripe about the terminal, and name it as the tool behind a build rather than the story.
Posts to understand this · as of Sep 30
Cursor is an AI code editor with agents that write, edit and review code.
Cursor held near 2.5% through June, then jumped to 3.0% in August around its SpaceX acquisition and role in Grok 4.5. That lift did not hold: share fell to 1.9% in September, and the L30 is down 41% despite fresh proof that Nvidia uses the product.
Posts to understand this
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay peaked in May, dropped hard through July, then held roughly flat in August and September. The posts show why that plateau matters: loyal users still value Clay’s workflow ecosystem, but Claude Code, Codex, and competitors such as Ocean.io are pressing on the same work; the current L30 move is down 12%.
Posts to understand this · as of Oct 6
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n jumped in May and held near that level in June after its multi-year SAP partnership put the product natively inside Joule Studio; Gamma’s native integration added another concrete workflow story. The curve then fell through September, and the 34.4% L30 decline coincides with buyers publicly framing Clay Workflows as a replacement for n8n, Make, and Zapier.
Posts to understand this
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable peaked in March, when its free SheBuilds day for International Women's Day, run with Anthropic, drew builders and stories like a 14-year-old launching her first app. Share slid to a July low, then recovered to about 1% in August and September. The last 30 days are flat. Slack's Add to Slack launch named Lovable as an agent partner.
Posts to understand this · as of Oct 2
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit’s share peaked in May, fell sharply in June, then partly recovered in August as OpenAI announced GPT-5.6 Luna in Free Mode. It slipped again in September while a production-database incident circulated in AI-safety discussion, even as Apollo launched inside Replit’s Growth Kit; the L30 measure now points up 3.9%.
Posts to understand this · as of Oct 4
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
OpenClaw declined steadily from March through September, and the L30 move remains negative despite a higher partial October bar. No single event explains the fade: early saga-level attention gave way to comparisons with easier alternatives such as Grok bot and broader discussion of agent harnesses as a category.
Posts to understand this · as of Oct 4
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
Codex rose into the 3% range by May, then held a remarkably steady plateau through September. The L30 is up 4.5%, supported by a widening product surface: Exa added access to 100 billion-plus sources, while Clay brought prospecting and enrichment workflows into Codex terminals.
Posts to understand this · as of Oct 5
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Hermes Agent appeared sharply in April and reached its high in May, when X Premium access, X post search, and hands-on local AI setups supplied clear reasons to try it. Attention then declined each month through September; a late web-search upgrade from Perplexity has not changed the current direction, with L30 down 29.2% and L90 down 52.5%.
Posts to understand this
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce stayed near 4% from May through August, then jumped sharply in September. Informatica’s Dreamforce debut and the Listen Labs acquisition agreement gave that rise concrete company news, while the earlier $3.6 billion Fin deal established the broader acquisition pattern; the L30 move remains up 16.9%.
Posts to understand this · as of Oct 6
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
HubSpot peaked in May, then lost share through August before a modest September recovery; L90 remains down 31.1%, while L30 is up 8.8%. Agent pricing and the Warmly acquisition supplied earlier bursts, and Trigify’s September move gave the recent improvement a concrete catalyst. The first four October days are only early context.
Posts to understand this · as of Oct 4
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Gong reached a spring high in April, declined through June, briefly recovered in July, and settled lower in August and September. The L30 move is up 10.9%, with attention supported by several concrete signals: half a billion in ARR, a fast multichannel demo response, and inclusion in Grok’s sales-bot integrations.
Posts to understand this · as of Oct 5
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
Vercel moves in a sawtooth around 1% of the conversation. August was the high, when Notion's Ivan Zhao joined Guillermo Rauch at Vercel Ship 2026 and Slack Code launched with Vercel among its agent partners. September fell back, and the last 30 days are down 32%, with v0 creator Jared Palmer's move to Cognition among the month's Vercel mentions.
Posts to understand this · as of Oct 3
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Claude Cowork has declined every month since a March high and is down 55% over 90 days. The slide is slowing, with the last 30 days down 8%. September's main story came from a partner: Anthropic relaunched Claude for Small Business with 43 workflows and 27 integrations, and Docusign brought its agreement platform into Cowork through a new MCP server.
Posts to understand this · as of Oct 2
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly's share climbed from March to a June peak; in April, during the climb, a free Claude Code repo shared by Jan Rasmussen loaded sequences into Instantly. Share halved in July, and these posts don't show why. It held near that lower level through September, with operators running Instantly mailboxes and hiring for it, and the last 30 days are about flat.
Posts to understand this · as of Oct 3
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter jumped in August around Stripe’s agreement to acquire it, then gave back much of that spike in September. The L30 move is down 60.4%, but share remains above its spring baseline, with routing economics and OpenAI overtaking Anthropic in weekly user spend keeping the company in the conversation.
Posts to understand this · as of Oct 5
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
Substack has bounced between 0.6% and 1.0% of the conversation all year without a lasting climb, and the last 30 days are down 17.9%. July's Pangram partnership to flag AI-written posts started a debate. Most mentions treat Substack as a creator's home base, or as the place to leave for beehiiv.
Posts to understand this · as of Oct 2
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Conversation peaked in June alongside debate over how SEO shapes AI visibility, then fell sharply through August. Share edged up in September as Semrush addressed Google redirects, but October remains partial; despite a newer sponsored attribution post, the L30 trend is down 4.8%.
Posts to understand this
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva’s share peaked in April, then fell through July, ticked up in August, and declined again in September. September conversation split between 100 product upgrades and pressure from AI feature costs, while October discussion centers on control, consistency, and creative agents. The last 30 days are essentially flat, up 0.2%.
Posts to understand this · as of Oct 6
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Ahrefs spiked in May and stayed elevated in June, then fell through August; September recovered slightly, but L30 is down 16.5%. The mix shifted from Ahrefs-powered backlink automation to direct category attacks and Ahrefs’ response to Google’s /goto redirects, which kept attention alive without restoring the spring high.
Posts to understand this · as of Oct 6
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier's share held near 1% to 1.3% through May, dropped to about 0.75% in June, then drifted to 0.6% in September. The last 30 days are down 47%. When Zapier does appear, it is framed as the old way: glue to cut out with Claude Code hooks, or a beginner skill, while Zapier's own posts push its Build Off.
Posts to understand this · as of Oct 3
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
ZoomInfo peaked at 1.5% in March and has slid since, down 45% over 90 days and 13% in the last 30. Much of the talk is about replacing it: Ava 2.0 claims to, and Moltsets pitches $27 a month for unlimited contact data. ZoomInfo's own story, MCP access through Slackbot, hasn't lifted the curve.
Posts to understand this · as of Sep 30
Profound measures and improves how brands appear in AI answers.
Profound has been volatile but directionally stronger, from 0.2% in March to 0.7% in September, with the L30 up 51%. The latest lift aligns with its $180M Series D and unicorn valuation, while sustained criticism of content quality and sampling reliability keeps the conversation from becoming purely celebratory.
Posts to understand this
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
ElevenLabs fell from 0.9% in May to 0.5% in August, then recovered to 0.7% in September. The L30 is up 86.5%, with attention supported by concrete scale signals: more than $600M in ARR, 59 open enterprise roles, and webinar pipeline growth from roughly $100K to over $8M.
Posts to understand this
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio rose from 0.57% in March to a 1.02% May high, alongside Intercom's Fin for Sales story with Attio and Attio's own GTM Atlas launch. It has drifted down since, to 0.47% in September, and is roughly flat over the last 30 days. In September, Dima Bilous shared a free revenue OS that writes every channel's agent output into Attio.
Posts to understand this · as of Oct 2
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo.io rose sharply into May, then drifted lower through September; L30 is down 29.3% and L90 is down 11.7%. The earlier climb matched a concrete workflow shift, with Claude using Apollo as the data layer, while September posts centered on Apollo Next and community access rather than a major product announcement. The elevated early October bar does not establish a reversal.
Posts to understand this · as of Oct 4
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify’s share surged from 0.142% in March to 0.913% in May, but the selected conversation only becomes visible in June, when creators framed it as the data layer for Claude-based social analysis and content systems. Share held near 0.9% through July, then fell through September; a September GTM workflow mention shows continued utility, while the L30 move is down 28.9%.
Posts to understand this
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Granola peaked near 1% in May, then lost ground through July and stayed around 0.5% in August and September. The L30 is down 23.9%; posts show useful mobile and executive workflows, but also direct pressure from Muesli’s free, offline transcription and local summarization alternative.
Posts to understand this · as of Oct 5
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
HeyReach climbed from March through June, then gave back most of that ground by September. The story opened with Brendan Short listing HeyReach among tools LinkedIn banned, though HeyReach said customers were unaffected. September's milestone of $17M ARR and 7,000+ teams did not stop the slide, and the last 30 days are down about 24%.
Posts to understand this · as of Oct 3
RB2B identifies the people and companies visiting a website so sales can follow up.
Conversation peaked in June, fell through August, then began rebuilding in September; October is still partial, while the L30 move is up 6.9%. Recent discussion pairs RB2B’s pricing-page visitor signal with automated outbound, alongside September visibility for founder Adam Robinson and his own growth advice.
Posts to understand this · as of Oct 4
Intercom is a customer messaging platform built around Fin, its AI support agent.
Intercom fell from March into May, spiked in June when Salesforce signed its agreement to acquire Fin, then reset sharply in July. The L30 is up 28% from that lower base, but the L90 remains down 60.6%. Fin’s observability launch and acquisition narrative created distinct bursts rather than sustained conversation.
Posts to understand this · as of Oct 6
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
LangChain rebounded from April’s low, then held a narrow June-to-September band near 0.4% as discussion spread across production agent stacks, startup rankings, and evaluation. No single launch drove the curve; September’s JEV test added a concrete agent-evaluation story, while the L30 share rose 31.1%.
Posts to understand this · as of Oct 6
Baseten deploys and runs custom AI models in production.
Baseten’s April spike is not explained by the available posts and quickly faded. The curve rebuilt from June through August around two tangible distribution plays: day-zero API access to Kimi K3 and free inference-engineering material. September stayed comparatively strong with an M&A diligence partnership, while the 27.2% L30 decline marks current cooling even as L90 remains up 50.0%.
Posts to understand this
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Nooks climbed steadily from March through July as the story expanded from dialing into a broader AI workspace: AI Sequencing launched in February, and Replit still used Nooks inside an AI-native sales stack. Share fell sharply in August, recovered in September, and is up 6.3% over the last 30 days, though the 90-day view remains lower.
Posts to understand this
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Common Room rose steadily from 0.26% in February to 0.66% in July, topping out with Zoom's acquisition on July 2. Once the deal news passed, it fell to 0.21% in August, and the last 30 days are down another 52%. Recent mentions treat it as one example in a wave of GTM platform exits, alongside Pocus and Warmly.
Posts to understand this · as of Sep 30
Exa.ai is a web search API designed for models and AI agents.
Conversation climbed through May, dipped in June, rebounded in July, then fell back in August. Applied GTM research, a technical explanation of agent search, and a September Sprites connector show the narrative broadening from use case to architecture to distribution, while the latest 30 days are up 25.3%.
Posts to understand this · as of Oct 6
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly climbed from about 0.27% in early spring to a July peak of 0.54%, when HubSpot bought it and Zoom bought Common Room the same week. Posts read both deals as a rollup of intent-signal tools. August fell back to 0.14%. The last 30 days are down 12%, and Warmly now shows up mostly as an example of consolidation.
Posts to understand this · as of Sep 30
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode’s share climbed gradually from March through June, then accelerated in July and August as Supabase included it in agent evals and Grok 4.6 became available through it. Share pulled back in September, and the L30 measure is down 29.9%, even as Databricks added OpenCode to its centrally managed agent workflow.
Posts to understand this · as of Oct 6
Gamma turns prompts into presentations, documents, websites and images.
Gamma’s March high coincided with a Claude connector workflow, but the larger pattern is uneven decline rather than one decisive event. Atlassian integrations produced major moments in April and September without sustaining a climb; after a July low and August bounce, the last 30 days are nearly flat at +1.8%, while the 90-day trend is down 30.7%.
Posts to understand this
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps moves in bursts tied to its own data and events. May was the high, with the AirOps Next event and a study of 5.1 million AI responses with Ross Simmonds' team. Since July, share has held near 0.2% and is flat over 30 days. Its research still travels: Diandra Escobar cited AirOps data showing YouTube's share of AI citations grew 158%.
Posts to understand this · as of Oct 2
1mind provides AI sales agents for websites, demos, live calls and customer success.
Conversation opened high in March alongside 1mind’s Clari and Salesloft announcement, dipped in April, then recovered through June. A July LeanData integration and August webinar pipeline post did not reverse the slide: share fell in July, held roughly flat in August, dropped again in September, and is down 42.8% over the last 30 days.
Posts to understand this · as of Oct 5
Firecrawl turns websites into clean, structured data for models and agents.
Firecrawl rose into May, fell in June, hit a second high in July, then held a lower plateau across August and September. July attention came from its credit-based onboarding loop, while the plateau reflects continued practical use and ecosystem expansion; the latest 30 days are up 8.8%, with Data Legion joining Firecrawl Alexandria.
Posts to understand this · as of Oct 6
Higgsfield generates video and images for ads and social content.
Higgsfield climbed from April through June, held flat in July, then lost ground in August before a modest September recovery. The L30 gain of 27.9% aligns with fresh product heat around AI Influencer, while Together AI’s infrastructure support explains how Higgsfield can sustain high-volume video workloads.
Posts to understand this · as of Oct 6
Grok Bot is an always-on agent that learns routines and completes work across existing software.
Grok Bot appeared in August, rose again in September, and is up 21.3% over the last 30 days. The launch established bots as teammates that operate existing software, while service cancellation and Stripe-powered purchasing gave the conversation concrete examples of autonomous work rather than another abstract agent pitch.
Posts to understand this · as of Oct 4
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce launched Aug 27, so August's share came from about five days of heavy attention. Marc Benioff's announcement and Jason Lemkin's account of running Salesforce headless set the tone, and Raj De Datta questioned whether the model fits other vendors. September was a full month at lower daily intensity, and the last 30 days are down 6%.
Posts to understand this · as of Oct 3
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
GPT-6 went from almost nothing to about 5 percent of the conversation in September, carried by GPT-6 Astra. Perplexity's eval had it beating Fable 5.1 on score at lower cost. Usage followed: Peter Walker said OpenAI took 31% of OpenRouter spend in 48 hours, and Supabase offered unlimited Astra tokens. The last 30 days are up more than sixteenfold.
Posts to understand this · as of Oct 2
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Fable went from nothing to 3.6% in June when Anthropic launched Fable 5, then rose to 4.3% in July before falling to 1.3% in August. Fable 5.1 restarted it: Cursor shipped it on Sept. 1 with a 73.4% CursorBench score, and Claude ran build days from Sept. 11 to 25. The last 30 days roughly doubled.
Posts to understand this · as of Sep 30
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
After an April spike, GPT-5 fell sharply in May and stayed low through September. No single launch in the posts explains the recent movement: benchmark comparisons, inclusion in Replit’s model picker, and September cost criticism form a thin but recurring drumbeat. The L30 measure is up 107.7%, though L90 remains down 28.6%.
Posts to understand this
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Claude Opus share has moved in bursts since March, with quieter months in between. September jumped back up, and the last 30 days are up sharply while the 90-day level is roughly flat. September's posts center on Opus 5.5 leading OpenRouter spend and landing in Snowflake Cortex AI, plus an open model claiming Opus 5 slide quality at a fraction of the price.
Posts to understand this · as of Oct 2
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Conversation jumped from a near-zero spring base to 0.948% in July, when Grok 4.5 topped an automation benchmark and became available on Augment’s agent platform. Share then eased through August and September, and the L30 is down 26.7%; Make’s September addition of Grok 4.7 shows the automation thread continuing.
Posts to understand this · as of Oct 6
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Claude Sonnet faded to almost nothing by May, then spiked in June with the Sonnet 5 launch, which more than doubled its score on Zapier's automation benchmark. Talk cooled through August, even after Anthropic made the $2 and $10 per million token pricing permanent. The last 30 days are up 178% as Sonnet 5.5 reaches platforms like Netlify.
Posts to understand this · as of Sep 30
Muse Spark is Meta's AI model for running coding and other agents.
Muse Spark moved from almost no share in spring to a sustained climb from July through September, leaving L90 share up 347.2%. L30 is now down 8.8%, so momentum has cooled. The climb followed benchmark visibility for Muse Spark 1.1 and the September release of 1.3 through Meta’s Muse and Genspark.
Posts to understand this · as of Oct 6
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Conversation share spiked in May around Gemini 3.5 Flash’s Databricks release, fell in June, then rebounded with Gemini 3.6 Flash’s July launch and Harvey’s early legal testing. Cursor availability supplied a fresh September integration signal, but the curve stayed roughly flat through August and September before falling 66.1% in the latest 30 days.
Posts to understand this · as of Oct 6
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
Kimi’s July spike came from concrete price-performance comparisons: Together AI put Kimi K3 near Claude Fable 5 at roughly 35% of the price, while Vercel highlighted low-cost cybersecurity results. Conversation then cooled through August and September, and the latest 30 days are down 18.6%; Cline’s limited free access created attention without restoring July’s benchmark surge.
Posts to understand this · as of Oct 6
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen spiked in August, more than tripling its June share, while builders debated whether Qwen 27B could handle production code. September fell back by more than half, and the last 30 days are down 55%. Qwen stays a fixture of local AI setups like Andrew Chen's homelab, and the open-weight Qwen-Image-2.1 release kept it in view.
Posts to understand this · as of Oct 3
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM barely registered until June, when GLM 5.2 arrived and Greg Isenberg called it a possible "chatgpt moment" for local AI. It held that level through August. September cooled and the last 30 days are down 41%, though GLM 5.3 is spreading through products: Notion added it to its model picker, and Bolt users picked GLM 5.3 Flash first.
Posts to understand this · as of Oct 3
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos spiked to 1.65% in April, when Anthropic held back Claude Mythos Preview and shared it with 40 partners for defensive security work. A second high in June faded, and share has held near 0.25% since July. The Sept. 1 launch of Mythos 5.1 hasn't lifted it. The last 30 days are down 16%.
Posts to understand this · as of Sep 30
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney's June spike came from one day of conversation on June 18. Greg Isenberg held it up as proof a bootstrapped company can matter, and Lulu Cheng Meservey credited David's personal control of a staged presentation. No follow-up moment came, so share fell below spring levels and is still sliding, down 32% over 30 days.
Posts to understand this · as of Oct 1
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Conversation jumped in April around Windsurf’s Devin cloud delegation, then fell through June before rebounding in July and August as Daytona added controlled sandboxes and Amplitude placed Devin among parallel agent fleets. That rebound has cooled, with share down 39.8% over the last 30 days.
Posts to understand this · as of Oct 4
Runway is an AI platform for generating and editing video and images.
Runway drifted down from February to a low of 0.11% in August, even as its July tease of Seedance 2.5 drew strong attention on its own post. Share has more than doubled over the last 30 days. The September evidence is thin: Runway shows up as a guest at MiniMax's Japan IP conference, alongside Higgsfield, Krea and HeyGen.
Posts to understand this · as of Sep 29
Jev is TypeSafe AI's decision model, which returns typed answers such as choices, probabilities and scores instead of text.
September’s jump was driven first by Vercel reporting record-fast AI Gateway adoption, then by concrete use cases later in the month. MotherDuck documented faster, cheaper classification, while HeyGen used Jev to decide which leads should receive videos, supporting its new presence over the last 30 days.
Posts to understand this · as of Oct 4
Muse is Meta's personal AI agent, which connects to a person's email, calendar and payments to shop, book and schedule for them.
Muse is new. It barely registered in August, then climbed in September as apps like Granola showed up inside it and users posted results like Austin Armstrong's dinner reservation. Wes Bush named it next to Grok as what everyone was obsessed with. The last 30 days are nearly 14 times the prior period.
Posts to understand this · as of Oct 2
Instinct is a personal AI agent with its own email address that creates accounts, contacts businesses and handles support requests for its user.
Instinct first registered in August and climbed through September, while the L30 measure is up 421.9%. The conversation spans a rapid valuation ramp, late-September discovery among AI watchers, and early-October inclusion in Sierra and Meta’s personal agent protocol; October remains partial.
Posts to understand this
Join 19,396+ GTM leaders and practitioners. Free, unsub anytime.
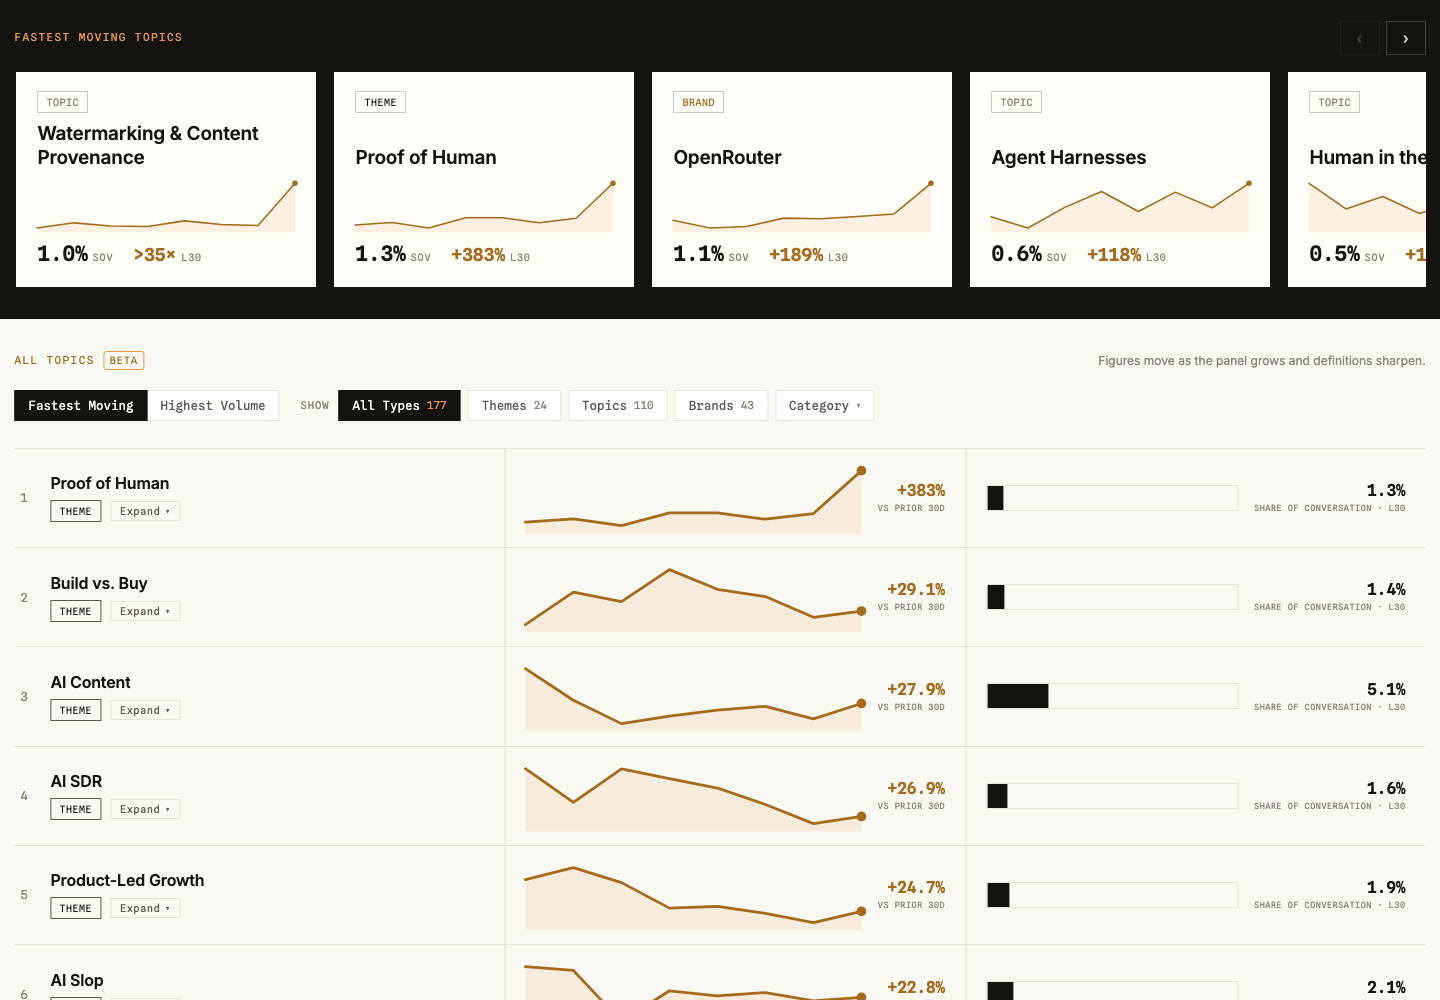
Loading people…
join 19,396+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-10-07.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,396+ gtm leaders, unsub anytime.